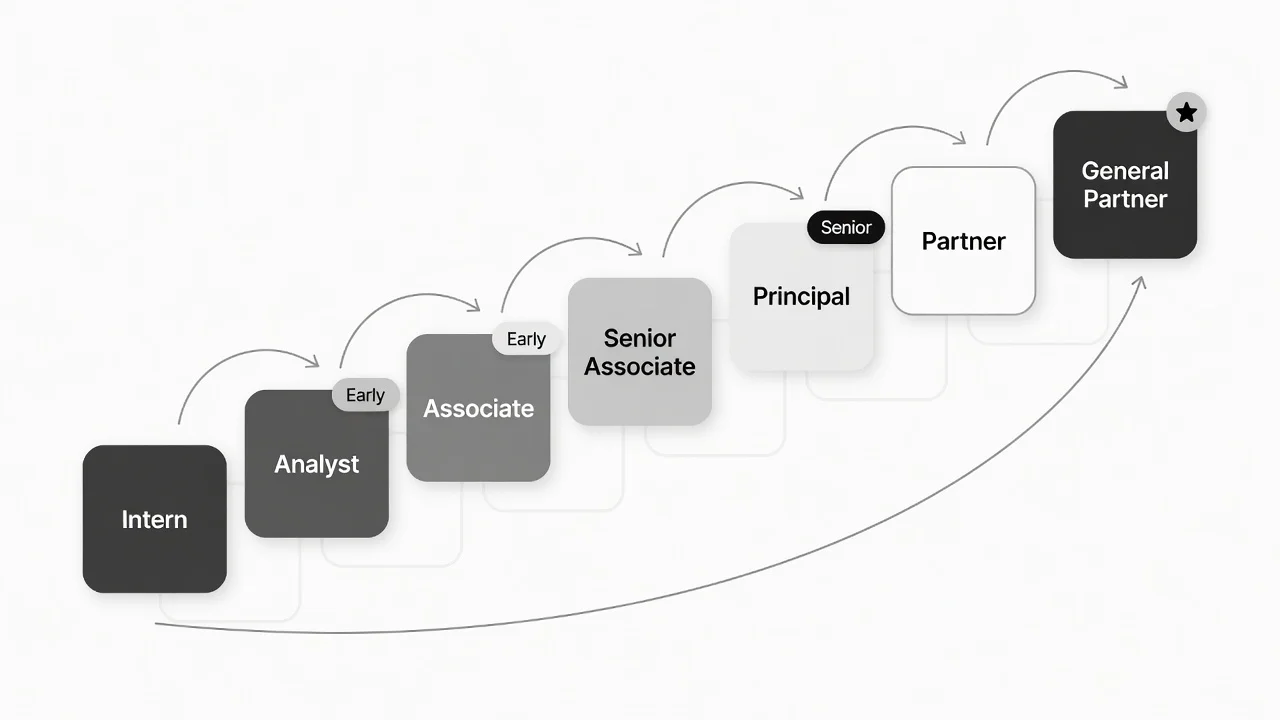
The venture capital career path runs analyst, associate, senior associate, principal, partner, and general partner. Each seat typically lasts two to five years, so a full climb from a first junior role to general partner usually takes 10 to 15 years. Most people do not climb it from the bottom. Many junior seats are fixed two-year terms with no promotion built in, and a large share of partners join mid-ladder after careers as founders, operators, bankers, or engineers, or skip the ladder by raising their own fund.
Two facts shape every decision on this path. Cash pay is modest relative to finance peers until the principal level, because the real economics are carried interest that pays out over a fund's ten-plus-year life. And promotion depends less on tenure than on attribution: deals you sourced or led that the partnership funded.
The venture capital career path at a glance
| Level | Typical time in seat | Main job | Carry | What usually moves you up |
|---|---|---|---|---|
| Intern | One summer or semester | Sourcing lists, market maps, research support | None | A return offer into an analyst class |
| Analyst | 2 to 3 years, often a fixed term | Market maps, first-pass screening, data rooms, memo support | None | Internal promotion is uncommon; most move to an associate seat elsewhere, an MBA, or an operating role |
| Pre-MBA associate | 2 to 3 years | First meetings, screening, diligence, models, memos | Rare | Usually not promoted directly; an MBA or more operating depth comes next |
| Senior or post-MBA associate | 2 to 3 years | Leads diligence, presents at investment committee, board observer seats | Small, if any | Sourcing a deal the partnership funds and running the process end to end |
| Principal or VP | 3 to 5 years | Runs deals from first meeting to close, first board seats | Yes, well below partners | Deals with traction, founder references, and a seat opening in the partnership |
| Partner | 3 to 5 years before full GP status at firms with two partner tiers | Sponsors deals, sits on several boards, joins LP meetings | Meaningful | A track record limited partners will underwrite in the next fund |
| General partner or managing partner | Open-ended | Final investment authority, fundraising, firm strategy | Core economics | Raising the next fund |
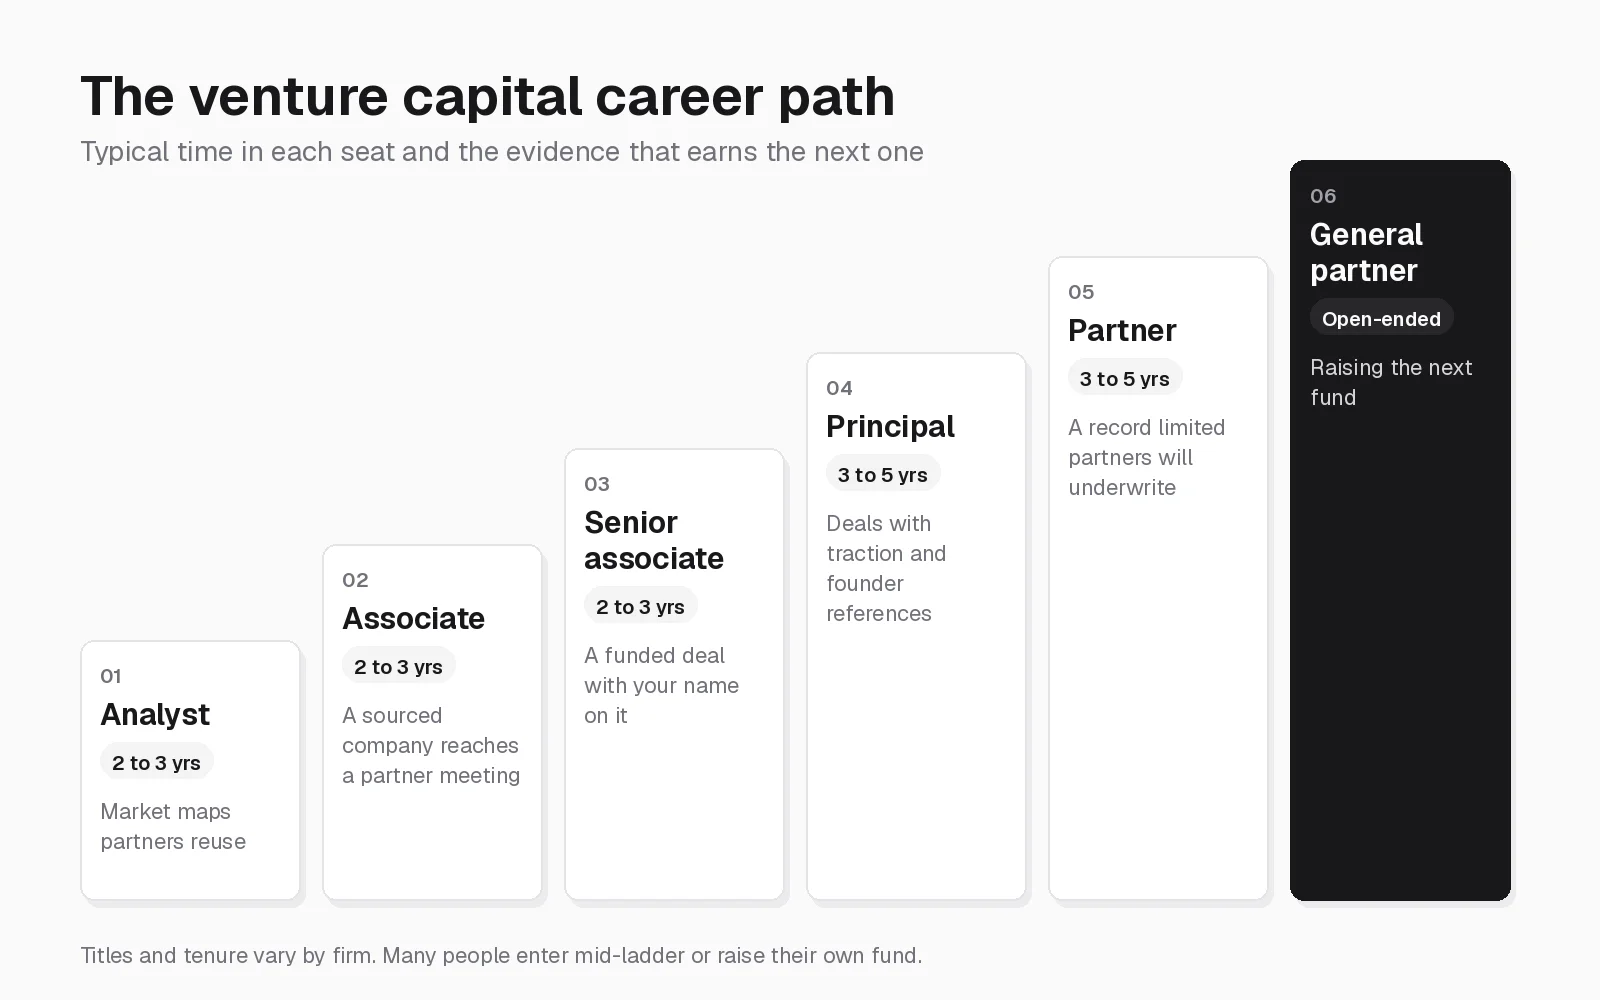
Treat the table as a map, not a schedule. Some firms have no analysts. Some call every investor below partner a "principal." Some have one partner tier, others three. Read the responsibilities behind a title before comparing it to anything on this ladder.
Venture capital roles by level
Analyst and intern
Analysts join out of undergrad or after one to two years in banking, consulting, or a startup. The work is research and funnel-building: market maps, sourcing lists, first-pass screens, data-room work, and sections of memos that senior investors use to decide whether to take a meeting. Hugh Bowen, an analyst at SOSV, described a typical week as roughly 40% ad hoc tasks, 40% research, and 20% networking and development.
Most analyst programs at larger U.S. funds run two years. Union Square Ventures' 2026 analyst program, for example, hired two analysts on a fixed two-year term with full investment-team participation. Structured classes like that are the exception; most funds hire one analyst when a partner leaves or a new fund closes. Internships, usually 10 to 12 weeks in summer, mirror analyst work at lighter scope and feed full-time offers. The venture capital analyst job description covers duties in detail, and how to get a venture capital internship covers the internship search.
Pre-MBA associate
Pre-MBA associates arrive after two to four years in investment banking, consulting, product management, or a startup. They are the front-line filter: Balderton partner Suranga Chandratillake describes associates as the people who decide which inbound companies reach principals and partners. At early-stage firms the seat skews toward sourcing; at later-stage firms it skews toward models and diligence. Many pre-MBA associate roles are two- to three-year terms, after which the associate leaves for an MBA, a portfolio company, or another fund. See the venture capital associate job description and the analyst vs associate comparison.
Senior associate and post-MBA associate
At most firms that use the title, the senior or post-MBA associate is the first partner-track seat. The work looks similar to the associate role, but with more ownership: leading a diligence process end to end, presenting at investment committee, taking board observer seats, and starting to source companies the partnership actually funds. Senior associates who do not reach principal within two to three years usually move to a smaller fund at a higher title or into an operating role.
Principal and vice president
Principals, sometimes titled VP or director, run deals from first meeting to close, negotiate terms, and take their first board seats. They still cannot approve an investment alone. This is the first level where carry is common, though the allocation is a fraction of a partner's. Entry here comes from internal promotion or from outside: an MBA plus three to five years of operating experience, or roughly seven to ten years of operating or product experience without one. The principal job description sets out the job, and how to become a venture capital principal covers the promotion.
Partner and general partner
Partners sponsor deals at the partner meeting, sit on several boards, and help raise the next fund. Firms with two partner tiers separate partners who can champion or block a deal from general partners who hold final authority, ownership of the management company, and the largest share of carry. General partners are also expected to put personal money into the fund: Carta's Fund Economics Report 2025 found a median GP commitment of 1.7% of fund size across venture funds on its platform. The venture capital partner job description and limited partner vs general partner cover the role and the LP relationship.
Venture capital roles outside the investing ladder
A venture firm employs more than investors, and several of these seats are real career paths in their own right. The question that matters for career planning is whether a seat builds investing attribution or a separate functional ladder.
| Role | What the seat does | Typical hire | Carry | Path back to an investing seat |
|---|---|---|---|---|
| Venture partner | Part-time or deal-by-deal sourcing and sponsoring | Senior operators, repeat founders | Often deal-by-deal or fund-specific | Sometimes converts to partner after a strong deal |
| Operating partner | Functional help for portfolio companies (go-to-market, talent, engineering) | Senior functional leaders | Varies by firm | Occasional; most stay functional |
| Entrepreneur in residence | Advises portfolio, explores a next company for a set period | Founders between companies | Rare | Usually ends in a new company, sometimes in a partner seat |
| Platform or portfolio operations | Community, events, content, portfolio support programs | Marketers, community builders, operators | Small or none | Possible when the seat produces sourced deals with your name on them |
| Talent partner | Executive recruiting for portfolio companies | Executive recruiters | Small, if any | Rare; the ladder is head of talent |
| Investor relations | LP communications, reporting, fundraising support | Capital-raising and IR professionals | Sometimes at senior levels | Rare; the ladder is head of IR or COO |
| Fund finance and operations | Fund accounting, capital calls, reporting, compliance | Accountants, fund administrators | Sometimes for a CFO | Separate ladder to CFO or COO |
| Scout | Part-time sourcing with a small check allocation | Founders, operators, students | Deal-level share of upside | Sometimes leads to an analyst or associate offer |
| Fellow | Structured program of a few months to a year | Students, career switchers | None | Sometimes leads to a junior seat |
Platform and operations seats are a legitimate way into a firm, but they do not automatically convert. The people who move from platform into investing usually brought in companies the partnership funded while doing the platform job.
How long each step takes
An illustrative climb for someone who stays in venture, with wide variance between firms:
- Years 0 to 2. Analyst or intern at a fund, or two to four years in banking, consulting, or a startup before a pre-MBA associate seat.
- Years 2 to 5. Associate, then an MBA and a post-MBA associate seat, or a direct move to senior associate at a firm that promotes.
- Years 5 to 9. Senior associate to principal. First board seats and first meaningful carry.
- Years 9 to 15. Principal to partner, then general partner, often at a different firm or a new fund you help raise.
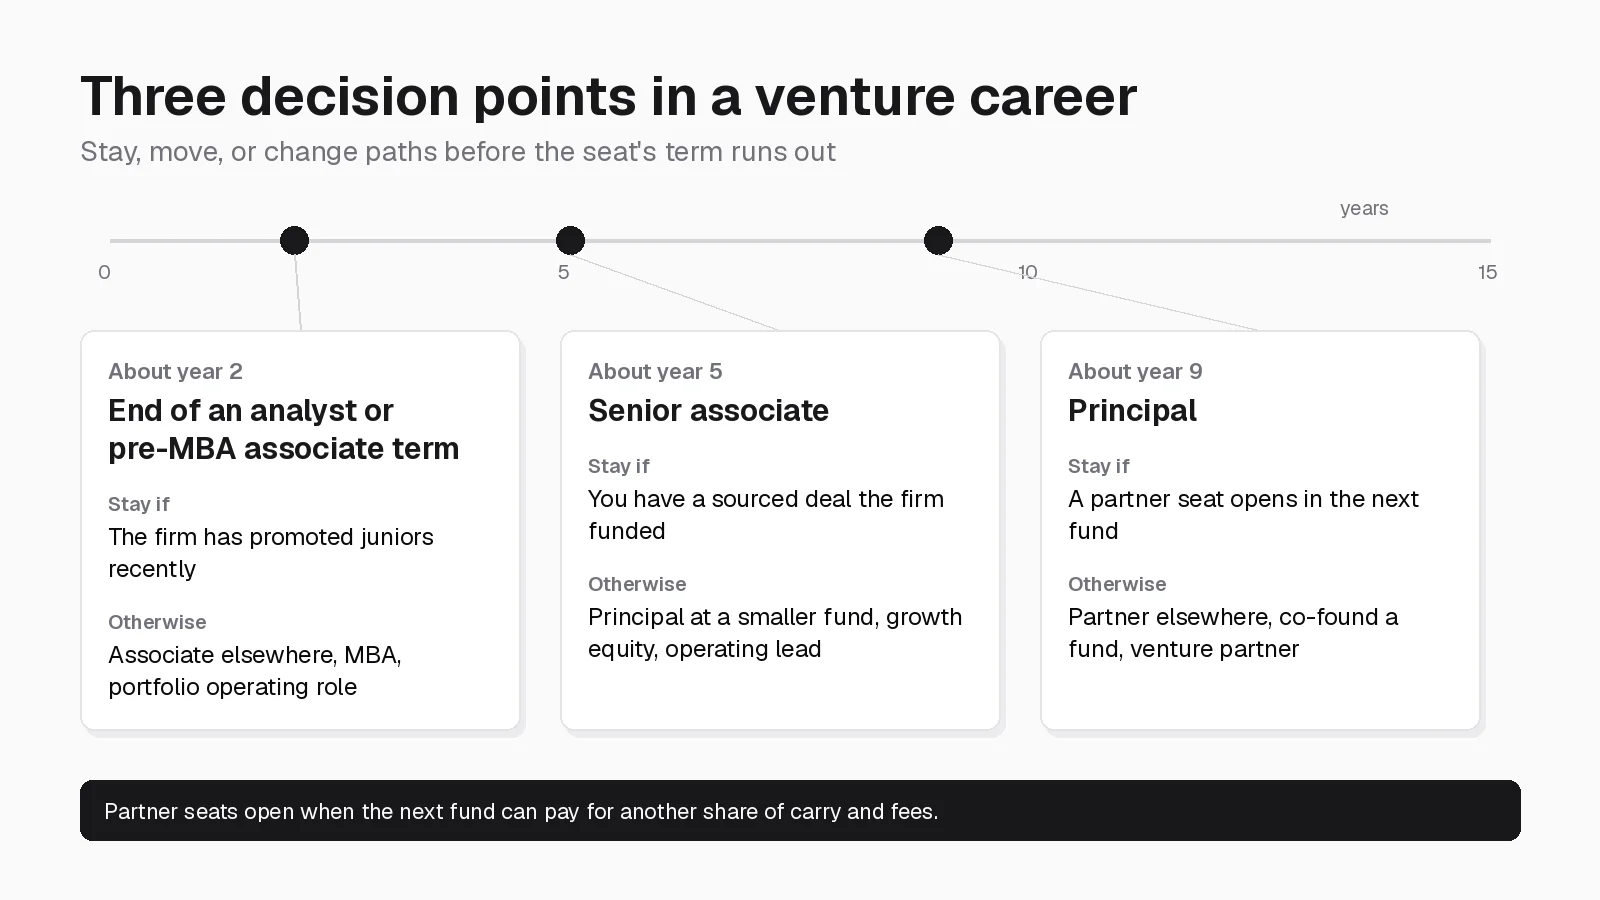
The timeline breaks at three predictable points, and each one has a short list of good moves:
| Decision point | Stay if | Move if | Common moves |
|---|---|---|---|
| End of an analyst or pre-MBA associate term (about year 2) | The firm has promoted juniors in the last two cycles and has named you for a sector | The firm has no record of promoting juniors | Associate at another fund, MBA, operating role at a portfolio company |
| Senior associate (about year 5) | You have at least one sourced deal the partnership funded | You are still supporting other people's deals | Principal at a smaller fund, growth equity, operating leadership |
| Principal (about year 9) | The partnership is adding a partner and LPs know your deals | No partner seat is opening in the next fund | Partner at another firm, co-founding a fund, venture partner role |
Partner timelines stretch when a partnership is not growing. A firm that raises a fund the same size as the last one rarely adds a partner.
What the same title means by firm size
Titles on postings look interchangeable. The work behind them is not.
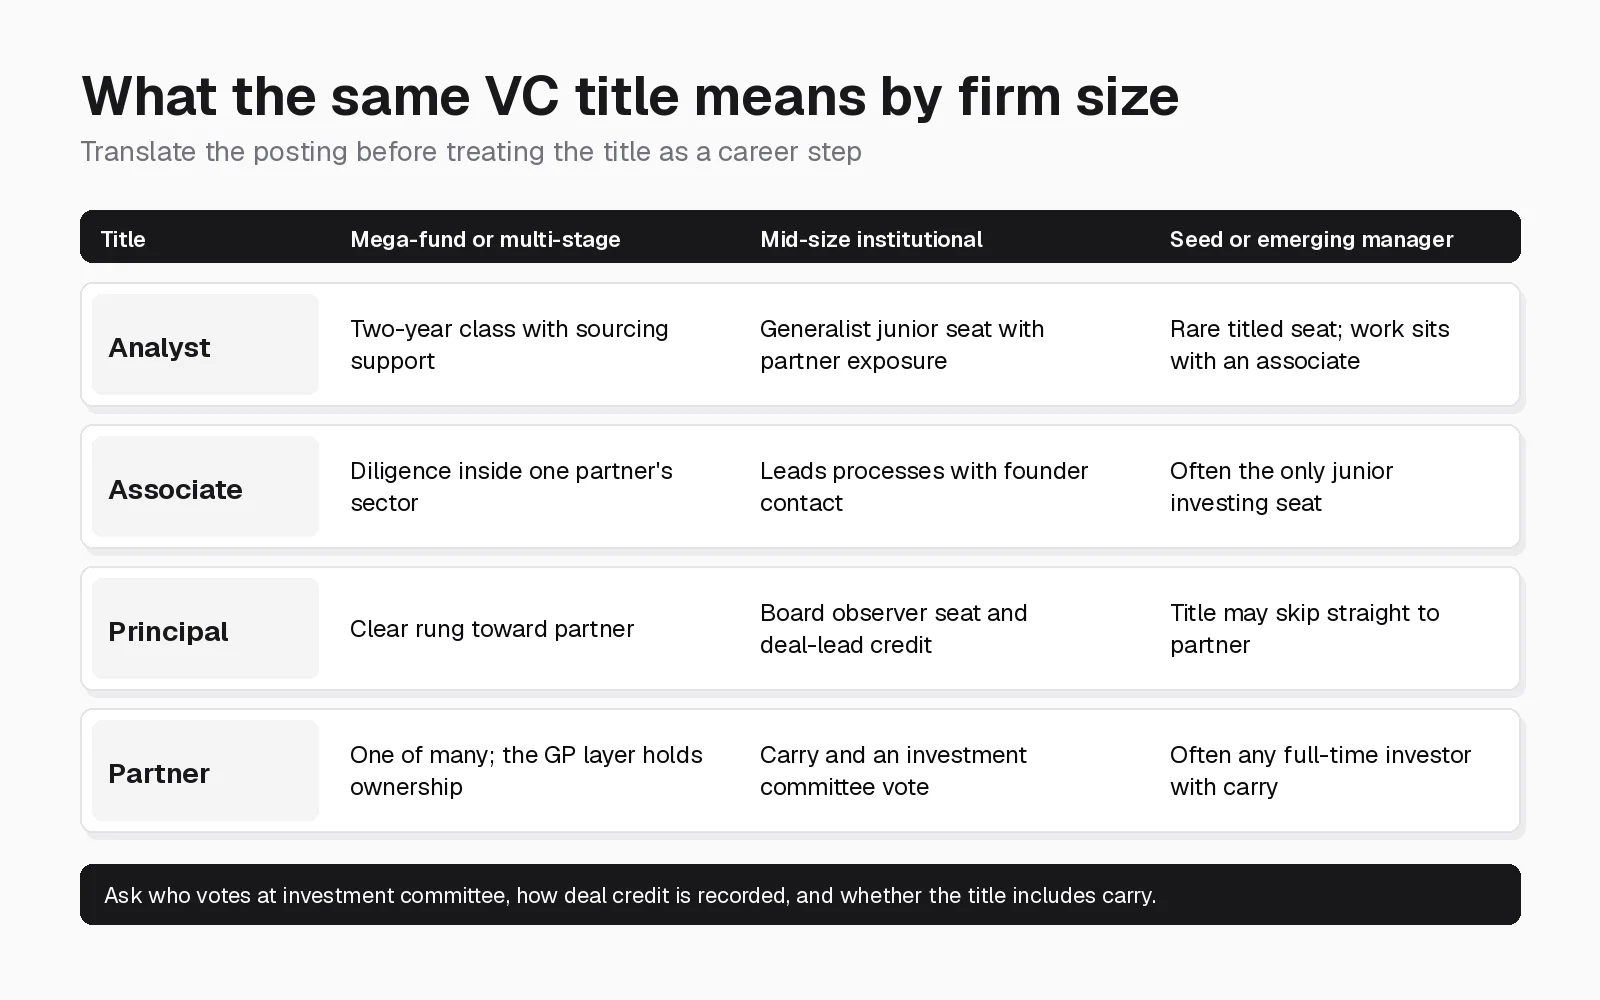
| Title on the posting | Mega-fund or multi-stage | Mid-size institutional | Seed or emerging manager |
|---|---|---|---|
| Analyst | Structured sourcing and research support, often a two-year class | Generalist junior seat with partner exposure | Rare as a titled role; the work sits with an associate |
| Associate | Diligence inside one partner's sector | Leads processes with real founder contact | Often the only junior investing seat, spanning analyst and associate work |
| Senior associate or principal | Clear rung toward the partner track | First seat with board observer rights and deal-lead credit | The title may skip straight to "partner" for the same work |
| Partner | One of many investing partners; the GP layer holds ownership | Meaningful carry and an investment committee vote | Often any full-time investor with carry |
| General partner | Ownership and LP-facing authority | Same, in a smaller partnership | Frequently the founding team |
Stage changes the work as much as size does. Seed and pre-seed investing is narrative- and relationship-heavy, with simple models. Growth-stage funds run diligence closer to private equity, which is why bankers convert more easily there (see growth equity vs venture capital). Corporate venture capital units add a third model: salaried roles inside a corporation, usually without traditional carry.
Before comparing offers, ask who votes at investment committee, how deal credit is recorded, and whether the title comes with carry. The companies directory shows stage and focus for each firm so you can tell a sourcing-heavy seat from a diligence-heavy one before you apply.
What gets you promoted at each level
Venture firms promote people who add to the deal funnel. A survey of 885 venture capitalists by Gompers, Gornall, Kaplan, and Strebulaev, summarized in the NBER Digest, found the median firm considered 100 deals for every deal it closed. Over 30% of deals came through professional networks, 30% were proactively self-generated, and only 10% came in cold from management teams. Anyone who reliably adds to the first two buckets is valuable at every level.
| Level | Evidence that earns the next seat | Question to ask your firm |
|---|---|---|
| Analyst | Market maps partners reuse, companies you flagged before they raised, clean memo sections | Has anyone in this seat been promoted in the last three years? |
| Associate | A sourced company that reached a partner meeting, a diligence process you ran, founders who take your calls | How is sourcing credit recorded? |
| Senior associate | A deal the partnership funded with your name on it, a board observer seat where founders found you useful | What does the principal decision depend on, and when is it made? |
| Principal | Deals with follow-on traction, founder references, a sector reputation that brings inbound | Is the next fund adding a partner? |
| Partner | A track record limited partners will underwrite, and a role in raising the fund | What share of the next fund's carry and management company comes with the seat? |
Hiring signals point the same way. Blume Ventures partner Sajith Pai frames top-tier venture as a sell-side job: distributing a firm's capital to founders who could take money from anyone. Menlo Ventures partner Amy Wu Martin gives the practical version for candidates: send good deal flow, not coffee-chat requests. The skills behind that are covered in venture capital skills.
Which entry path fits your background
| Background | Typical entry | Realistic five-year outcome | Best next move |
|---|---|---|---|
| Undergrad with 0 to 2 years in finance or tech | Intern or analyst | Associate elsewhere, MBA, or startup operator | Target analyst programs and build a written record of companies you would back |
| Investment banking or consulting, pre-MBA | Pre-MBA associate, more often at growth funds | MBA, post-MBA associate, growth equity, or portfolio company | Build a sector point of view on top of diligence speed (consulting to venture capital) |
| Top MBA | Post-MBA associate | Principal track at the same fund or a lateral move | Pick stage and sector deliberately; post-MBA seats are scarce |
| Startup operator, product manager, or engineer | Associate, senior associate, or principal | Principal or operating partner | Take a role with founder proximity at a venture-backed company (operator to venture capital) |
| PhD, MD, or deep technical specialist | Associate or principal at a sector fund | Principal or partner at a life science or deep tech fund | Publish or advise in your field; see biotech venture capital |
| Founder or C-suite executive | Principal, venture partner, or partner | GP at a new fund or senior seat at an established one | Skip the junior ladder entirely |
| Scout, angel, or community builder | Part-time scout, then analyst or associate | Platform or investing seat | Convert visible deal judgment into warm intros at target funds |
Entry level matters more than most candidates expect. Stanford professor Ilya Strebulaev's study of 12,627 U.S. venture careers from 1996 to 2025 found junior entrants were 70 to 80 percentage points less likely to become senior VCs than people who entered at the middle level, and 26 percentage points less likely to be credited with even one investment. The study's advice for anyone targeting partnership: work inside a startup first, then join a fund at a more senior level.
The MBA route still works but carries less weight. TechCrunch reported in September 2025 that the share of mid-career venture professionals holding MBAs fell from 44% in the early 2000s to 32%, as firms recruit technical talent from companies building AI and hardware. Alternatives are covered in venture capital without an MBA, and step-by-step break-in tactics in how to become a venture capitalist.
Partner-track expectations and exits
"Partner track" appears in job posts more often than it exists in practice. Most analyst and associate seats are apprenticeships with a planned exit, and a partnership can only add a partner when the next fund's economics support another share of carry and fees.
Carry at junior levels is rare and small where it exists. It also vests over years and only pays when the fund returns capital, so an associate who leaves after three years usually walks away with little or none of it. Wischoff Ventures' Neal Mintz has described the result: a quiet exodus of experienced non-partners into operating roles, because at many funds the best non-partners do about one deal a year, too few reps to build a track record while carry stays distant.
The common exits are well worn:
- To operating. Product, strategy, BizOps, or finance at a portfolio company. The most common exit for analysts and associates.
- To another fund. A higher title at a smaller fund, or a lateral move to a firm with a partner seat opening.
- To growth equity or private equity. Easier from later-stage venture with modeling depth.
- To founding. Venture exposure is a strong prompt to start a company, and founder experience later makes a strong partner candidate.
- To raising a fund. Covered below.
Venture capital pay by level
Venture pay blends base salary, a bonus, and carried interest. Base and bonus come from the management fee, usually 2% of committed capital a year during the investment period. Carry is typically 20% of fund profits, split across the partnership and in smaller slices to senior staff. Carta's report found both medians held steady across recent vintages: a 2% fee and 20% carry. The bands below match the venture capital salary guide, which explains the sources and drivers.
| Role | Typical base salary | Typical bonus | Carry access |
|---|---|---|---|
| Analyst | $70K to $115K | $5K to $25K | Rare |
| Associate | $100K to $175K | $10K to $50K | Sometimes small or deferred |
| Senior associate | $140K to $210K | $20K to $75K | More possible, not guaranteed |
| Principal or VP | $175K to $275K | $30K to $125K | Often meaningful if partner-track |
| Partner or GP | $250K to $600K+ cash, wide variation | Highly variable | Core economics |
Fund size is the largest driver of cash because fees scale with assets. Stage, city, and firm maturity add more spread: growth funds pay more cash than small seed funds, and emerging managers often trade lower cash for faster responsibility. Venture cash usually trails private equity at the same seniority until carry starts to matter.
Raising your own fund instead of climbing
Raising a fund skips several rungs at once, which is one reason many partners at seed firms were never associates anywhere. The economics are simple to model and hard to live on early.
Take a $25 million first fund on standard terms. A 2% annual fee produces $500,000 a year to cover every salary, legal bill, audit, and flight for the whole team, so first-time general partners often pay themselves less than a principal at an established firm. Carta reports a median GP commitment of 1.5% for funds of $25 million to $100 million, about $375,000 of personal capital for this example. If the fund eventually returns three times its capital, the $50 million profit produces a $10 million carry pool for the GP team, paid out as companies exit over a decade or more.
Raising tends to work for people with three things: a thesis that founders and LPs recognize as differentiated, a record of attributed deals (from a prior fund, angel checks, or scout investments), and relationships with limited partners before the raise starts. Without those, a few years at an established firm builds them faster. The fund structure guide and management fees explained cover the mechanics.
Pros and cons of a venture capital career
| Pros | Cons |
|---|---|
| Early view of new markets and technology across dozens of companies a month | A narrow junior ladder with few promotions and many fixed terms |
| Work with founders on their hardest decisions | Feedback on your judgment takes five to ten years to arrive |
| Long-dated upside through carry at senior levels | Carry is back-loaded, uncertain, and usually absent below principal |
| Strong exits into operating, founding, and other investing roles | Junior cash trails banking and private equity |
| Reasonable hours compared with banking, with flexible structure | An always-on networking job that blurs work and evenings |
Venture suits people who enjoy forming views with thin data, building relationships over years, and waiting a long time to find out whether they were right. It suits people who need predictable advancement, near-term wealth, or repeatable work far less.
How to read a VC job posting for career-path signals
Postings rarely say what the seat does to a five-year plan. Screen each one for:
- Term length. "Two-year program" or a fixed end date means an apprenticeship with a planned exit. "Path to principal" or no term language is a different bet, still worth verifying.
- Investing or platform. Sourcing, diligence, memo ownership, and board observer language point to investing. Community, content, talent, or portfolio operations point to platform.
- Stage and check size. Pre-seed and seed language implies founder access and narrative diligence. Growth language implies financial depth.
- Attribution language. "Own a sector" or "lead processes" builds deal credit. "Support the partners" builds learning, not credit.
- Carry wording. "Discretionary carry" or silence usually means cash only. A stated allocation with vesting terms is rare below principal and worth confirming in writing.
- Team size. A three-person partnership and a thirty-person platform team produce very different weeks.
- Questions to ask before accepting. What happened to the last two people in this seat? How is deal credit recorded? Is the fund raising, deploying, or both?
A prestigious logo with no attribution path is often a weaker career move than a smaller fund where you lead work. Mike Dauber of Amplify Partners makes the same case: stage, sector, and team size decide whether a first venture job compounds. Browse current openings on the Venture Capital Careers job board and check each firm's stage on the companies directory.
Common mistakes when planning a VC career
- Treating the analyst seat as the partner track. Many programs exist to train and rotate talent.
- Comparing titles without firm context. "Partner" at a three-person seed fund and at a mega-fund are different jobs.
- Ignoring the two-year clock. Plan the next move at month six of a fixed-term seat, not month twenty.
- Choosing brand over attribution. A famous fund where you take notes can teach less than a small fund where you run deals.
- Counting on junior carry. Assume cash only and treat any carry as a bonus.
- Skipping operating experience when partnership is the goal. Time in a venture-backed company often moves a candidate further than a second junior investing seat.
- Mistaking a platform seat for an investing seat. It converts only if it produces sourced deals.
FAQ
What is the venture capital career path?
The standard order is analyst, associate, senior associate, principal or VP, partner, and general partner or managing partner. Titles vary by firm, and many people enter at associate, principal, or partner after working as founders, operators, bankers, or engineers.
What roles are there in a venture capital firm?
Investing roles run from analyst to general partner. Outside that ladder, firms hire venture partners, operating partners, entrepreneurs in residence, platform and portfolio operations staff, talent partners, investor relations, fund finance and operations, scouts, and fellows.
How long does it take to become a VC partner?
Commonly 10 to 15 years from a first junior role, with 3 to 5 years at principal alone. Founders and senior operators often enter at partner level directly, and raising a fund skips the ladder entirely.
Do VC analysts get carried interest?
Usually not. Small allocations sometimes start at senior associate, and carry typically becomes meaningful at principal for employees who receive it.
Can you get into venture capital without an MBA?
Yes. MBAs remain a common route into post-MBA associate seats at larger firms, but the MBA share of senior-level entrants has fallen to about a third, and operating and technical backgrounds increasingly substitute for it.
Is venture capital a good career path?
It is a good path for people who want founder exposure, long-dated upside, and strong exit options, and who accept a narrow junior ladder and back-loaded pay. It is a poor fit for people who need predictable promotion or high early cash.
Your next step on Venture Capital Careers
- Browse open analyst, associate, and principal roles on the Venture Capital Careers job board.
- Match firms to your entry path by stage and sector on the companies directory.
- Create a candidate profile so VC hiring teams can find you and new roles reach you first.
- Prepare for the process with venture capital interview questions and how to get a job in venture capital.
Related posts
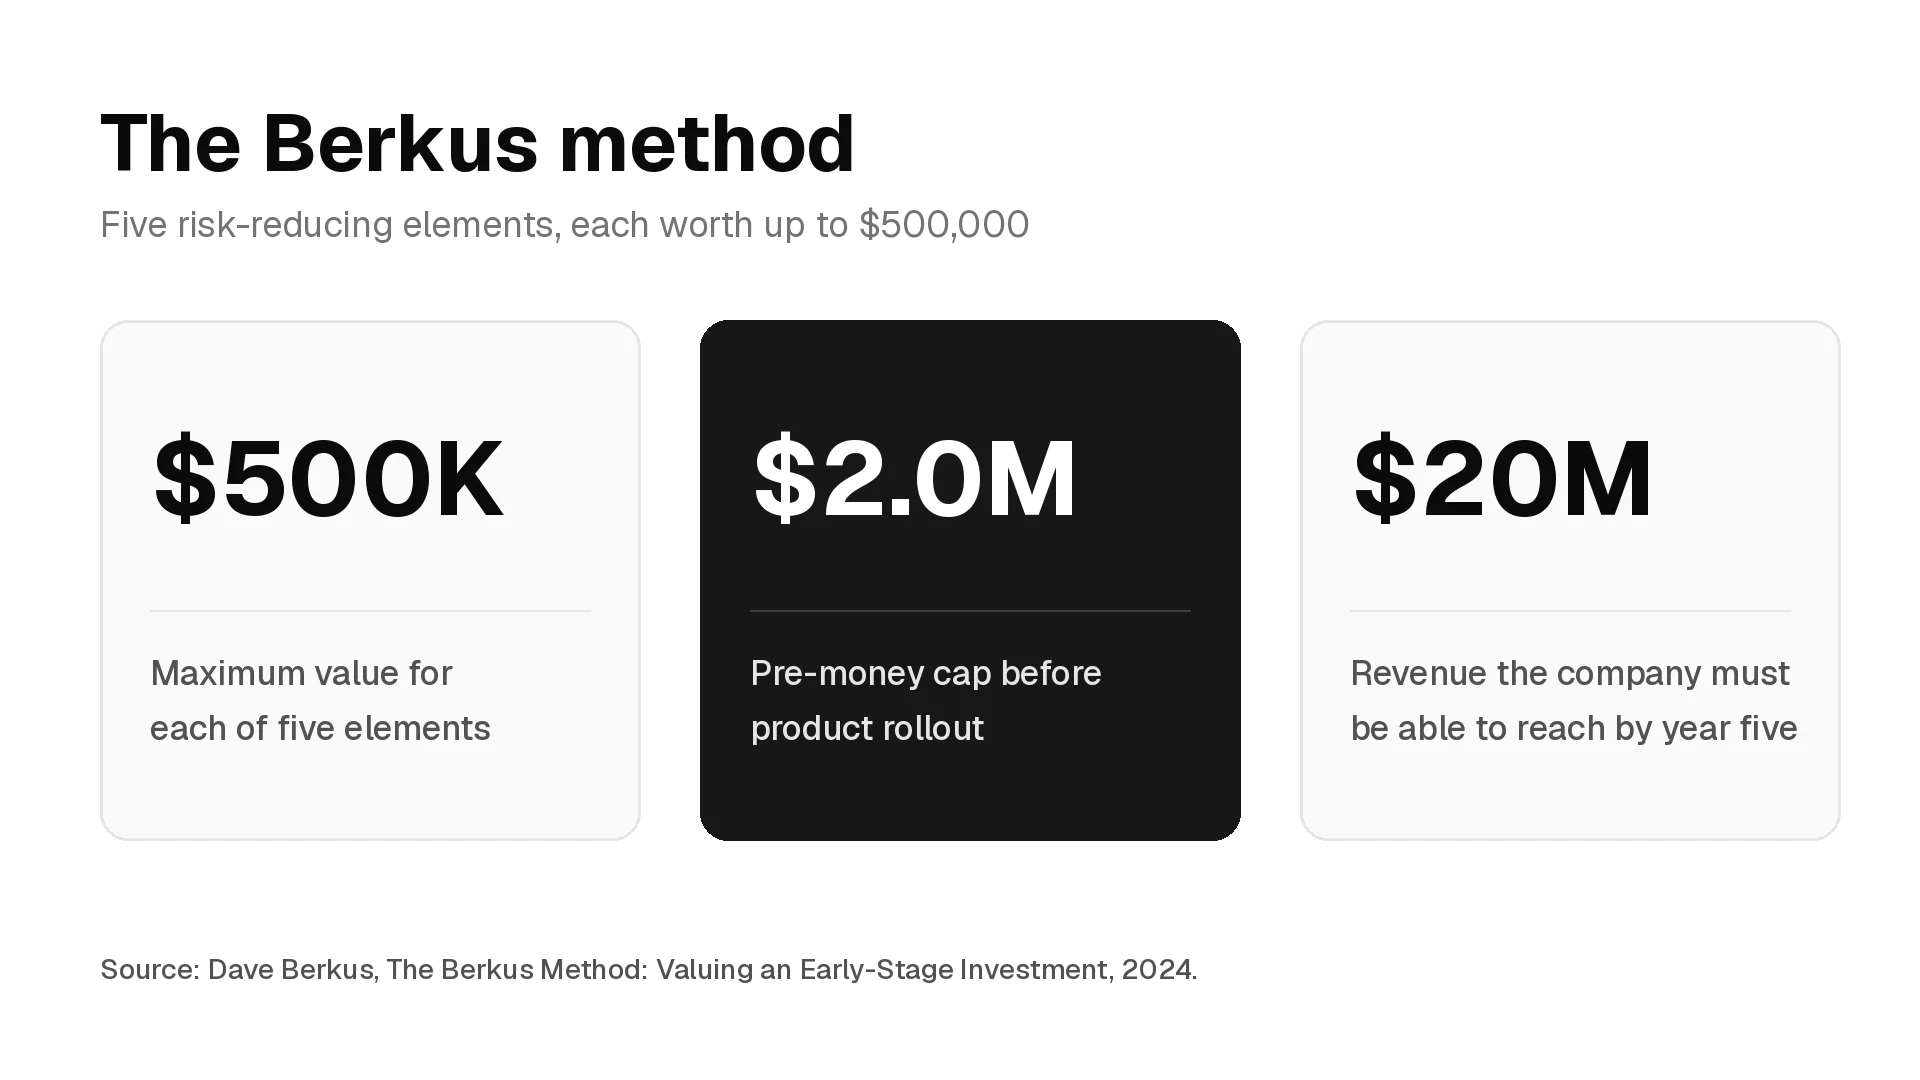
How the Berkus method values a pre-revenue startup, how to score each of the five elements, a worked example with ownership and 10x checks, how the $500,000 caps compare with current seed prices, and how VC analysts use it in memos and interviews.
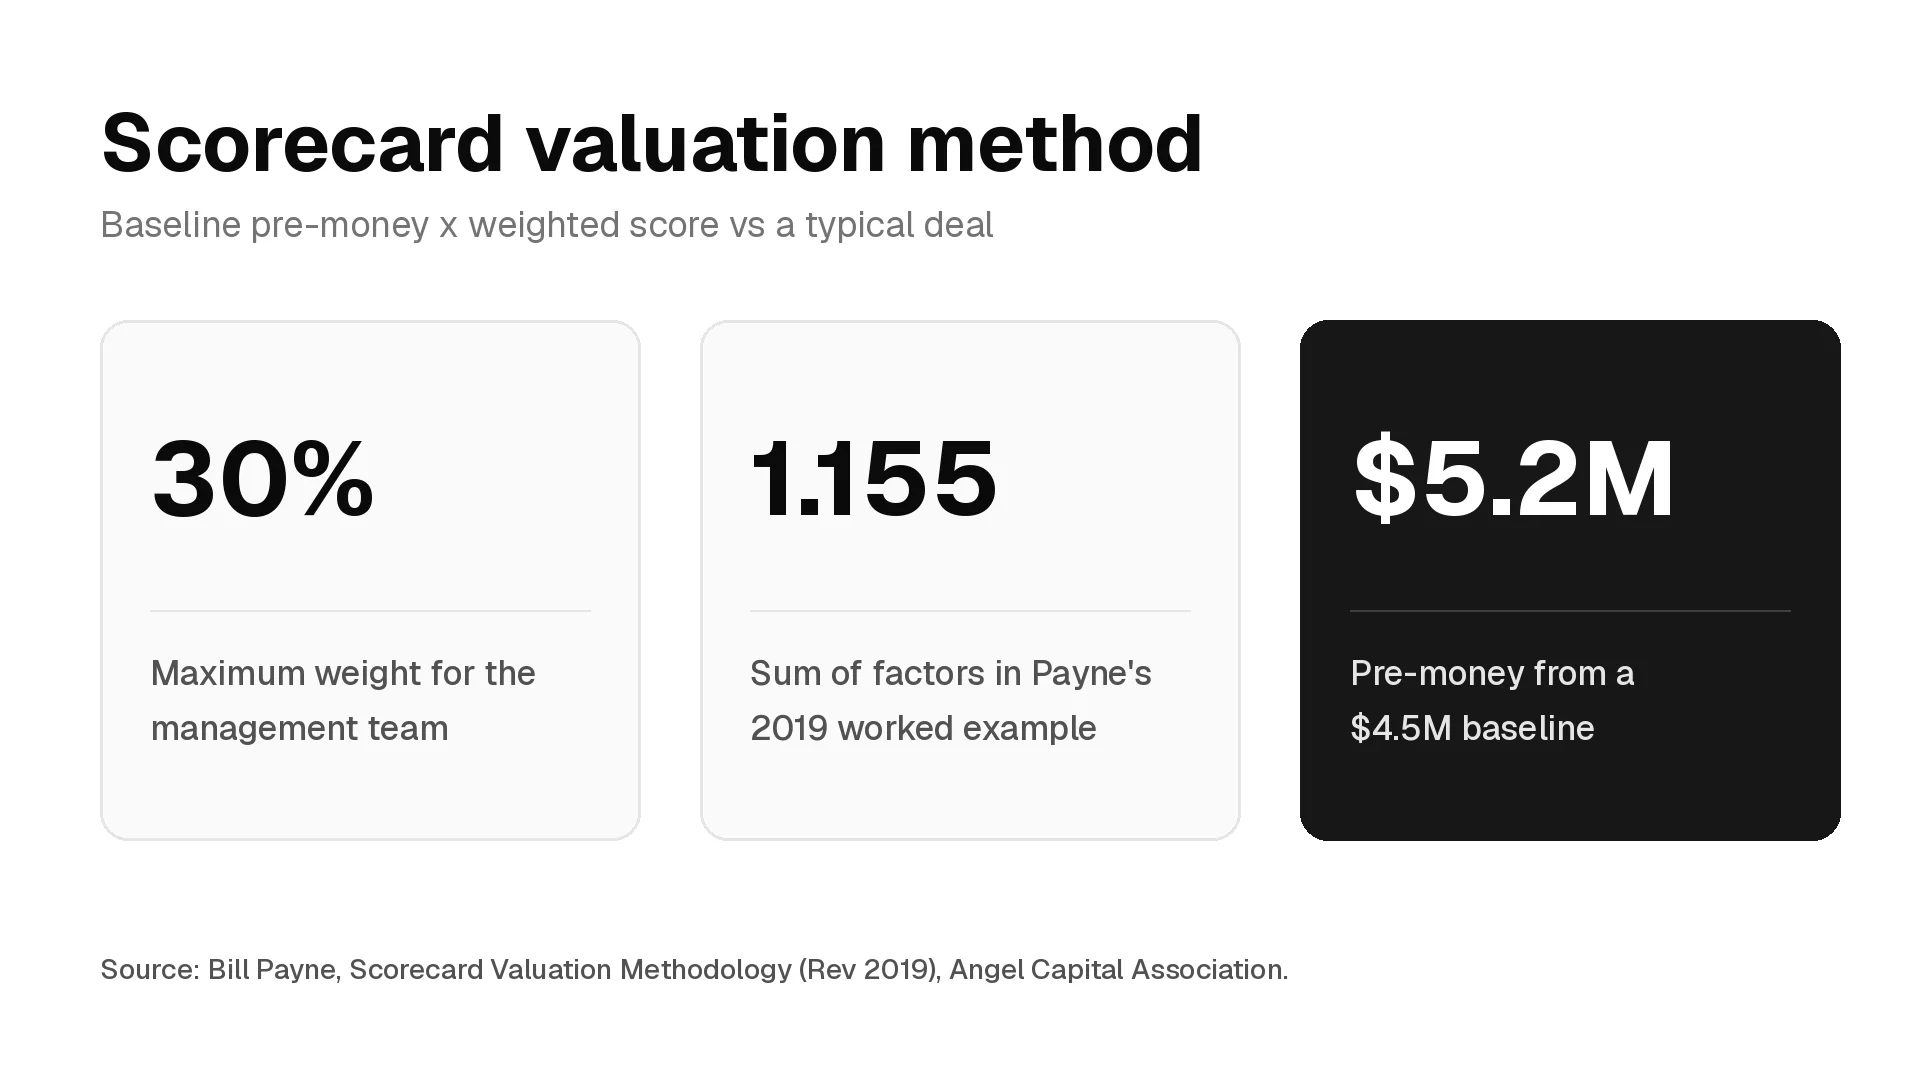
How the scorecard valuation method works, Bill Payne's seven factor weights, his worked example with the arithmetic checked, how to choose the baseline with current seed data, how sensitive the answer is, and how VC analysts use it in memos and interviews.
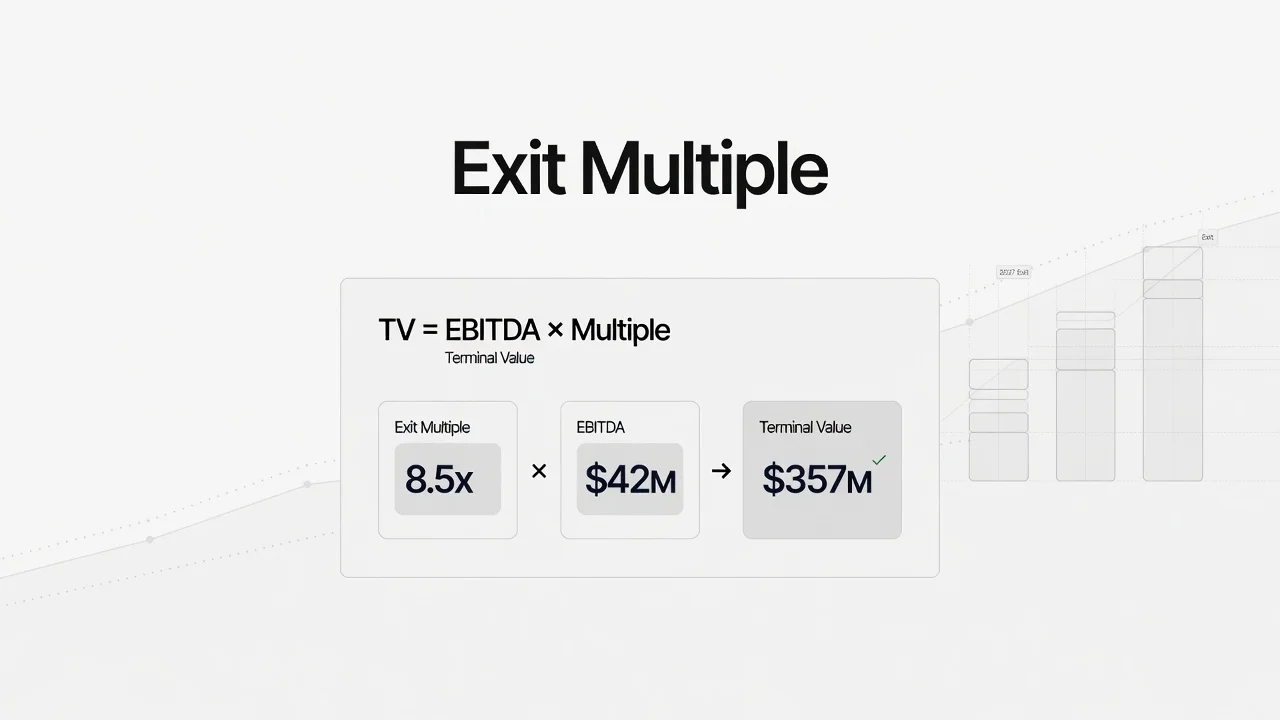
Exit multiple formula, a worked DCF terminal value example with a sensitivity grid, the implied growth cross-check, January 2026 industry multiples, and how VC investors use exit multiples.