Growth equity buys a minority stake in a company that already works: it has real revenue, growth usually above 20% a year, and profit or a near-term path to it. Venture capital buys minority stakes in startups that have not yet proven their market, product or business model. VC underwrites whether a company can work. Growth equity underwrites how fast a working company can scale, often using little or no debt and buying some existing shares from founders and early holders.
The difference shows up in losses. Cambridge Associates found that venture capital lost money on 32.7% of invested capital, compared with 13.7% for growth equity. The sample covered investments made from 1990 to 2016 and was measured to mid-2018. Venture made up for it with outliers. In VC, 8% of invested capital produced half of all value, through deals that returned more than 5x.
Growth equity vs venture capital at a glance
| Dimension | Venture capital | Growth equity |
|---|---|---|
| Company stage | Pre-seed to late stage (Series A to D+) | Scaled, often founder-owned, sometimes raising its first institutional round |
| Revenue and profit | Pre-revenue to fast-growing, usually losing money | Meaningful revenue, more than 10% growth and often above 20%, EBITDA positive or within 12 to 18 months |
| Main risk underwritten | Market, product and technology risk | Execution, valuation and scaling risk |
| Ownership | Minority stakes, built across rounds | Minority stakes, sometimes large ones, usually in a single deal |
| Shares bought | Mostly newly issued (primary) shares | Primary plus secondary shares bought from founders, employees and earlier investors |
| Leverage | None | None or limited |
| Portfolio shape | Many bets, a few outliers return the fund | Fewer bets, more outcomes in the 2x to 5x range |
| Capital loss ratio | 32.7% of invested capital | 13.7% of invested capital |
| Typical exit | Acquisition or IPO, often after many more rounds | Sale to a strategic buyer, sale to a buyout fund, or IPO |
| Investor's day-to-day | Founder assessment, market judgment, early sourcing | Financial diligence, operating metrics, cohort and margin analysis |
Loss ratios are from Cambridge Associates and cover US deals made from 1990 to 2016, measured as of June 30, 2018. The other rows describe typical patterns. Individual funds and rounds vary.
What venture capital funds
Venture capital funds companies before the business has proven itself. A seed investor may be backing a founding team, an early product and a thesis about a market. A Series A or B investor wants early signs of product-market fit and a go-to-market motion that seems to work. In both cases most of the value depends on things that have not happened yet.
VC pricing and portfolio construction follow from that. Most companies in a fund return little or nothing, so each investment needs a credible path to a very large outcome. Partners spend more time judging founders, market size and timing than building detailed operating models. That return pattern is the power law. It explains why VCs pass on good businesses that are unlikely to become category leaders.
VC rounds mostly buy newly issued preferred stock. The cash goes to the company, and each round dilutes existing holders. A company that raises from seed through Series D reprices its risk at each round as it hits milestones. Each round brings new pre-money valuation negotiations and new investors on the cap table.
What growth equity funds
Growth equity funds expansion at a company that has already shown the model works. Cambridge Associates describes a typical target this way:
- Founder-owned, with no prior institutional capital
- No debt, or limited debt
- A proven business model, an established product and existing customers
- Organic revenue growth above 10%, and often above 20%
- EBITDA positive, or expected to be within 12 to 18 months
From 2008 to 2017, growth equity companies in Cambridge's data grew revenue at an average of 17.2% a year. That was more than double the rate at buyout companies and more than triple the rate at public companies. They started smaller: median trailing revenue at entry was roughly 15% to 42% of the median buyout company's.
The money usually pays for sales capacity, new products, international expansion or acquisitions. Often part of it buys out early shareholders, which is the main structural difference from VC. Many growth equity targets bootstrapped to scale, so they have never had to run large losses. Investors price them on revenue or EBITDA, not on a story about a future market. For the definition and the firms that do it, see what growth equity is.
Key differences between growth equity and venture capital
Stage, traction and unit economics
VC can back a company before it has revenue. By Series B, investors expect traction, but losses are normal if growth is fast enough. Growth equity investors expect revenue, retention and margins that already support the business case. Diligence focuses on unit economics: gross margin, payback on customer acquisition, net revenue retention, and how growth holds up as spending increases.
Type of risk
A VC investor mainly takes market and product risk. The question is whether customers want the product and whether the company can build it. A growth equity investor mainly takes execution and price risk. The question is whether the company can keep growing at a valuation that still leaves a return. Cambridge Associates found that entry price matters less than expected and that sustaining growth matters more. About two-thirds of realized growth equity deals with revenue growth above 20% returned at least 2.0x gross. Nearly two-thirds of deals with no revenue growth were realized below cost.
Check size, valuation and ownership
VC ownership builds up across rounds. A lead investor at seed or Series A often aims for a meaningful minority stake, then defends it with pro rata rights. Growth equity usually takes its position in one larger deal and is less likely to need follow-ons. Valuation methods differ too. Growth investors price on revenue or EBITDA multiples. From 2010 to 2017, average entry multiples for growth equity deals rose more than 75% to 18.0x trailing EBITDA, against 11.2x for buyouts. Revenue multiples went from 2.9x to 4.9x. A VC investor pricing a Series A is more likely to use ownership targets and the venture capital method.
Control, terms and board seats
Both strategies usually take minority stakes, so neither controls the company the way a buyout does. Control comes through contract terms. VC rounds use preferred stock with a liquidation preference, protective provisions, information rights and often a board seat. Growth equity terms can go further because there are fewer future rounds to rely on. The company may have no other institutional investor, and the growth fund's return depends on a specific exit. Common additions include tighter consent rights over new debt or acquisitions, redemption rights, drag-along rights that can force a sale after a set period, and a board seat with more active financial oversight.
Primary vs secondary shares and founder liquidity
This is the clearest structural difference. VC rounds are mostly primary, so money goes to the company. Growth equity deals often include a secondary component that buys shares from founders, employees or early investors. Founders get personal liquidity without selling the company. Early VCs can return capital to their own funds. In a panel published in the Q3 2026 PitchBook-NVCA Venture Monitor, a growth equity general partner said that a secondary component is part of "virtually every growth equity deal" his firm does. The worked example below shows the arithmetic.
Use of proceeds
VC money pays for discovery: building the product, early hires, first sales and reaching the next milestone. Growth equity money pays for acceleration: sales and marketing capacity, geographic expansion, new product lines, add-on acquisitions, systems and finance infrastructure, and the liquidity described above. Cambridge Associates notes that growth equity companies often add infrastructure ahead of growth after the investment, which can depress EBITDA margins for the first one to two years. Buyouts tend to cut costs right away.
Due diligence
VC diligence on early companies is mostly qualitative: founder references, customer calls, market sizing and product assessment. Later VC rounds add financial work. Growth equity diligence is closer to private equity. It covers quality of earnings, cohort and retention analysis, pricing, sales capacity models, customer concentration and a financial model the investment committee will test line by line. For the investor side of each process, see venture capital due diligence and financial due diligence.
Holding period and exit
A VC investor may hold a company from seed to exit through many rounds. That is often longer than a growth investor holds a company it enters later. Growth equity hold periods are measured from a later entry point. Because growth equity companies can be profitable and are less dependent on more fundraising, they have more exit routes. They can sell to a strategic buyer, sell to a buyout fund that adds debt, or go public. Secondary sales and continuation funds now give both strategies liquidity before a full exit. For how holds are measured and what drives them, see holding period.
Risk and return: what the data shows
The Cambridge Associates analysis "Growth Equity: Turns Out, It's All About the Growth" covers 4,248 growth equity investments, 36,286 venture capital investments and 9,240 buyout investments made from 1990 to 2016. It shows how differently the two strategies produce returns.
| Measure (US, deals made 1990 to 2016, as of June 30, 2018) | Venture capital | Growth equity | Buyouts |
|---|---|---|---|
| Capital loss ratio (capital in deals realized below cost) | 32.7% | 13.7% | Roughly 10% to 15% |
| Share of invested capital in deals returning 2x to 5x | 18% | 31% | 35% |
| Share of total value from deals returning more than 5x | About half, from 8% of capital | 28% | 18% |
Source: Cambridge Associates, Growth Equity: Turns Out, It's All About the Growth (January 2019).
The table supports three points. First, growth equity loses money on far less capital than VC and is close to buyouts on downside. Second, its returns come more from a broad middle band of outcomes. Third, a VC portfolio depends on a small number of outliers. That is why the two strategies screen deals so differently. A VC investor asks whether this company could be one of the few that return the fund. A growth investor asks whether this company can keep compounding at a price that still produces a solid multiple.
At the fund level, Cambridge found that growth equity had outperformed venture capital over every period of 15 years or less as of mid-2018. US venture capital still led over the longest periods because of its mid- to late-1990s results. Fund-level returns depend heavily on the manager, so asset-class averages say little about a single fund. For how those returns are measured, see venture capital fund performance metrics.
Worked example: the same company, a VC round vs a growth equity round
A software company has $40 million in annual recurring revenue (ARR), grows 60% a year and runs close to breakeven. It has two offers at the same $250 million pre-money valuation. A founder owns 30% of the company before the round. The numbers are illustrative, and each figure follows from the inputs.
| Line | Offer A: VC-led round | Offer B: growth equity round |
|---|---|---|
| Pre-money valuation | $250M | $250M |
| New primary shares (cash to the company) | $50M | $50M |
| Secondary shares bought from existing holders | $0 | $30M, of which $10M from the founder and $20M from early investors and employees |
| Total investor check | $50M | $80M |
| Post-money valuation | $300M | $300M (a secondary purchase moves existing shares and adds no new ones) |
| New investor ownership | 16.7% ($50M / $300M) | 26.7% ($80M / $300M) |
| Founder ownership after the round | 25.0% (30% x 250 / 300) | 21.7% (25.0% minus $10M / $300M) |
| Cash to the founder | $0 | $10M |
| Likely terms | Standard preferred, board seat, pro rata rights | Preferred with more consent rights, possibly redemption or drag-along timing, board seat |
Four points follow:
- The company gets the same $50 million either way. The extra $30 million in Offer B goes to sellers, not to the balance sheet.
- The growth investor ends up with a much larger stake (26.7% vs 16.7%) for the same primary capital. That is why it can write one large check and still meet its ownership target.
- The founder trades 3.3 points of ownership for $10 million of cash. Whether that is a good trade depends on how much upside the founder expects. At a later $1 billion exit, those 3.3 points would be worth about $33 million before any preferences.
- The return math is different. If the growth investor targets 3x on $80 million, it needs $240 million back. With 26.7% and no further dilution, that requires an exit of about $900 million. A VC lead aiming for a fund-returning outcome on $50 million needs a far larger exit or more ownership.
Real deals often price secondary shares below the primary price, especially common stock bought alongside preferred. Discounts vary by deal. The structure stays the same: primary capital funds the company, secondary capital pays the sellers, and only primary capital dilutes holders. To run the ownership math for a specific round, use the post-money valuation and cap table guides.
Where late-stage venture capital and growth equity overlap
The labels blur at Series C and later. Large multistage VC firms raise growth funds, and growth equity firms lead late-stage rounds in venture-backed companies. Data providers draw the line in different places. In the PitchBook-NVCA Venture Monitor, Series C and D rounds count as late-stage VC and Series E and later count as "venture growth." Funds that identify as growth-stage vehicles are classified as private equity and left out of the report's VC fundraising totals.
Late VC rounds have also grown to growth-equity size. The median Series D+ round in the US reached $150 million in 2026 through September 30, up from $100 million in 2025. The median Series C rose from $50.5 million to $77.0 million.
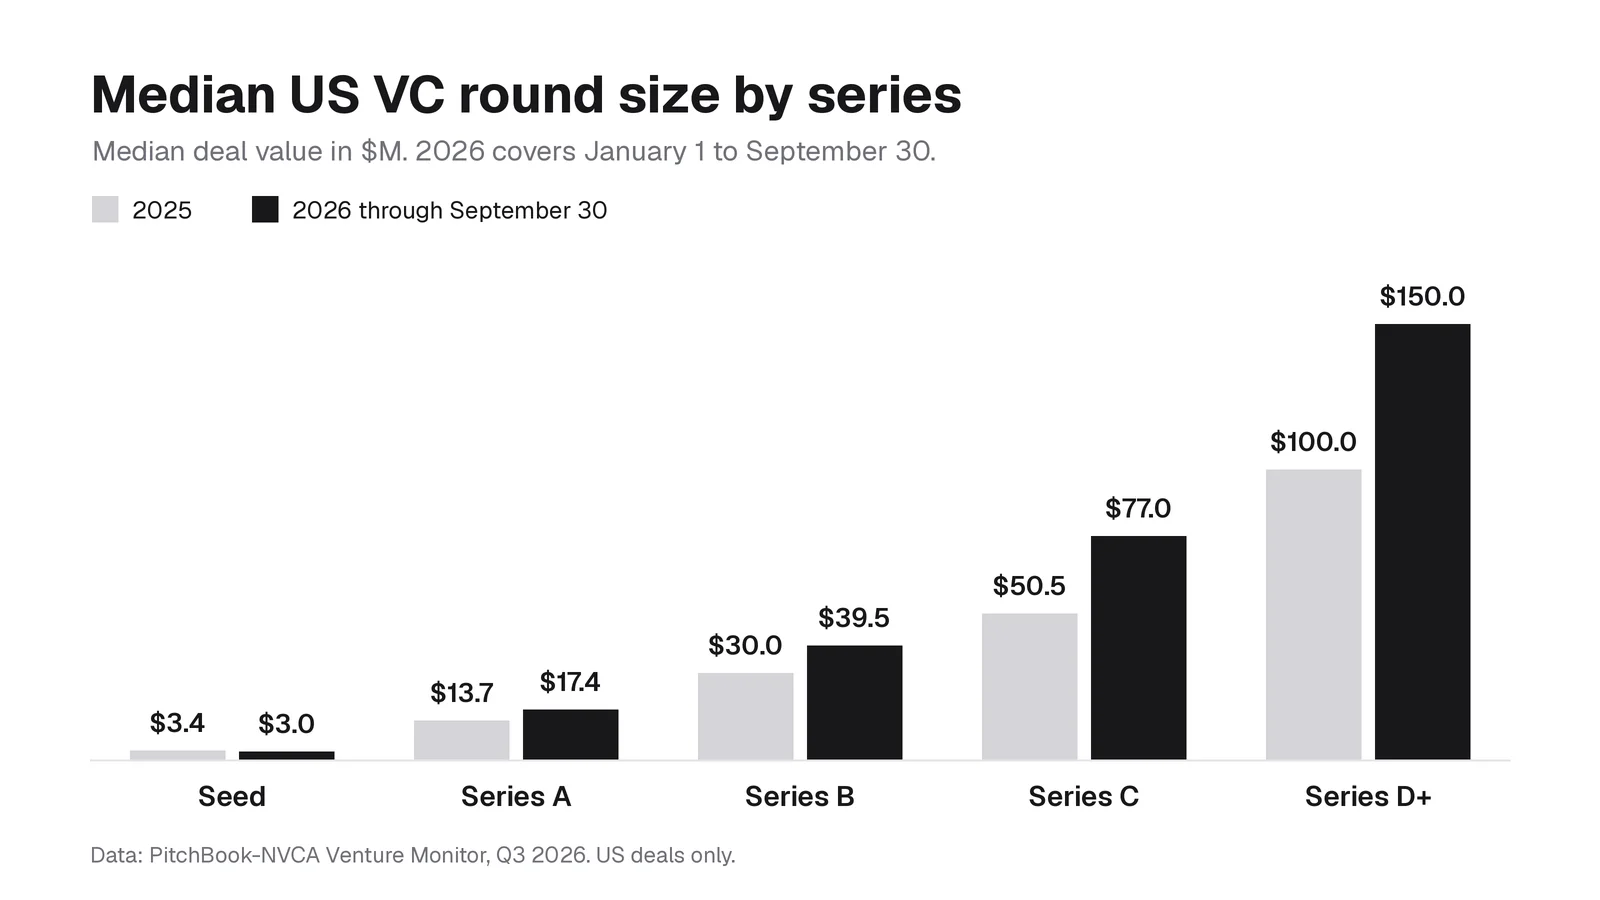
Median Series D+ pre-money valuations more than doubled over the same period, from $831.9 million to $1,723.7 million, according to the Q3 2026 PitchBook-NVCA Venture Monitor. At that size, the round label tells you little. Look at what the investor is underwriting instead:
- Late-stage VC: the company still burns heavily, and the bet is on market leadership and a very large exit. The round is mostly primary capital and is priced on future potential.
- Growth equity: the company has proven unit economics, often has a profitability plan, and the bet is on continued compounding at a reasonable price. The round often includes secondary shares and is priced on current revenue or EBITDA.
The same firm can do both. Investors from the two traditions still differ in diligence style, the terms they ask for, and how they judge whether a price is worth paying.
What growth equity and venture capital have in common
- Minority equity, not control. Both usually buy less than half the company and rely on preferred stock terms instead of majority ownership.
- Little or no debt. Neither depends on leverage for returns. This is what separates both from buyouts.
- Growth is the return driver. Cambridge Associates found that sustaining or accelerating revenue growth after investment predicts growth equity returns better than entry price does. In VC, growth is the whole thesis.
- Same fund model. Both are typically closed-end funds with limited partners, management fees and carried interest, and both need exits to return capital.
- Post-investment support matters more than it used to. Cambridge notes that growth equity managers increasingly need recruiting, business development, product and M&A support to drive results, which is ground VC platform teams have long covered.
Growth equity vs buyouts
Growth equity sits between venture capital and leveraged buyouts. A buyout fund buys control, usually a majority, and finances part of the price with debt. It often adds value through cost discipline and margin improvement soon after closing. A growth equity fund takes a minority stake with little or no debt and adds value by funding growth. In Cambridge's data, growth equity's capital loss ratio was close to that of buyouts, roughly 10% to 15% for both. Its upside was higher because capital went into growth instead of debt service. Growth equity targets were also smaller at entry and faster growing. For the full comparison of buyout funds with venture firms, see private equity vs venture capital. For the debt-like layer between the two, see mezzanine financing.
Which one fits the company
Venture capital fits when:
- The product or market is still being proven and current cash flow cannot support the plan
- The opportunity can plausibly reach a very large outcome, the kind that returns a fund
- The company expects to raise several more rounds and accepts dilution and investor governance along the way
Growth equity fits when:
- Revenue, retention and margins already prove the model, and capital would speed up something that works
- The company is profitable or near it and could keep growing without outside money, only more slowly
- Founders or early holders want partial liquidity without selling control
- The company wants one well-capitalized partner rather than a long sequence of rounds
Four questions settle most cases:
- Is the main risk whether customers want the product, or whether the company can scale delivery and sales? The first points to VC, the second to growth equity.
- Would the company survive and grow without the money? Growth equity investors usually want the answer to be yes.
- Does anyone on the cap table need liquidity? A secondary component is standard in growth equity and less common in VC rounds.
- Can the company accept stronger investor terms in exchange for a larger check and less future fundraising?
A company can do both in sequence. Many raise venture rounds through product-market fit and take growth equity once the model is proven. Growth equity firms also invest in companies that have never taken institutional capital.
Career differences: venture capital vs growth equity jobs
The jobs differ in the same ways as the capital.
| Dimension | Venture capital investor | Growth equity investor |
|---|---|---|
| Core judgment | Founder quality, market size and timing with little data | Business quality, durability of growth and price with a lot of data |
| Sourcing | Networks, founder referrals, early signals | Outbound calling and data screens of bootstrapped and founder-owned companies |
| Modeling | Light at early stages: ownership, dilution, return scenarios | Heavier: operating models, cohort analysis, returns with secondary and preferred terms |
| Diligence | Customer calls, product and team assessment | Quality of earnings, unit economics, management references, legal and commercial diligence |
| Common entry routes | Startups, product and engineering roles, investment banking, consulting | Investment banking, consulting, private equity, growth-stage operating roles |
| Exit opportunities | Founding or joining startups, later-stage VC | Private equity, later-stage investing, operating roles at portfolio companies |
Investment banking and private equity backgrounds fit the modeling-heavy growth equity seat more directly. Operators and former founders often have an edge in early-stage VC. Interview processes follow the same pattern. Growth equity interviews usually include a modeling test or case study. VC interviews lean on market maps, investment memos and founder judgment. For routes in, see venture capital career path, investment banking vs venture capital, the venture capital modeling test and the venture capital salary guide. Open roles at venture and growth firms are listed on the Venture Capital Careers job board.
Frequently asked questions
What is the main difference between growth equity and venture capital?
Venture capital funds companies that are still proving their market and product. Growth equity funds companies that have proven the model and need capital to scale. The investor's main risk shifts from whether the business can work to whether it can keep growing at the price paid.
Is growth capital the same as growth equity?
Mostly. "Growth capital" is the broader term for minority investment in mature, growing companies without a change of control. "Growth equity" usually refers to the dedicated funds and firms that provide it. Neither means a late VC round by default, although the two often overlap.
Is growth equity part of private equity or venture capital?
Most data providers and investors classify growth equity as a private equity strategy. The PitchBook-NVCA Venture Monitor, for example, classifies growth-stage funds as private equity. In practice it overlaps with late-stage venture capital, and many firms do both.
Is growth equity less risky than venture capital?
Yes, on losses. Cambridge Associates measured a 13.7% capital loss ratio for growth equity vs 32.7% for venture capital. Growth equity also has less extreme upside. VC concentrates its value in a small set of outliers.
Can a company raise venture capital and later switch to growth equity?
Yes. A common path is venture rounds through product-market fit, then a growth equity round once revenue and margins support it. That round often includes secondary shares bought from earlier VC investors and employees.
Do growth equity investors take control of the company?
Usually not. Growth equity takes minority stakes. It protects its position through preferred stock terms, consent rights and board representation, not majority ownership. Buyouts take control.
Do growth equity firms invest in profitable companies?
Often. Many targets are profitable or expect to reach positive EBITDA within 12 to 18 months, and some have never raised institutional capital. VC rarely requires profitability.
Is growth equity or venture capital better for a finance career?
Growth equity is the more direct fit for investment banking and private equity skills because the work is model-heavy and data-driven. Venture capital rewards market judgment and founder networks. Exit routes differ: growth equity leads more often to private equity, and VC leads more often to startups.
Related posts
A practical VC CRM evaluation workflow with a fictional six-submission test, a vendor-neutral scorecard, and checks for source history, permissions, exports and rollout.
How the risk factor summation method values a pre-revenue startup, how to score each of the 12 risks with evidence, a worked example with ownership and 10x checks, whether the $250,000 step still fits current seed prices, and how VC analysts use it in memos and interviews.
How the Berkus method values a pre-revenue startup, how to score each of the five elements, a worked example with ownership and 10x checks, how the $500,000 caps compare with current seed prices, and how VC analysts use it in memos and interviews.