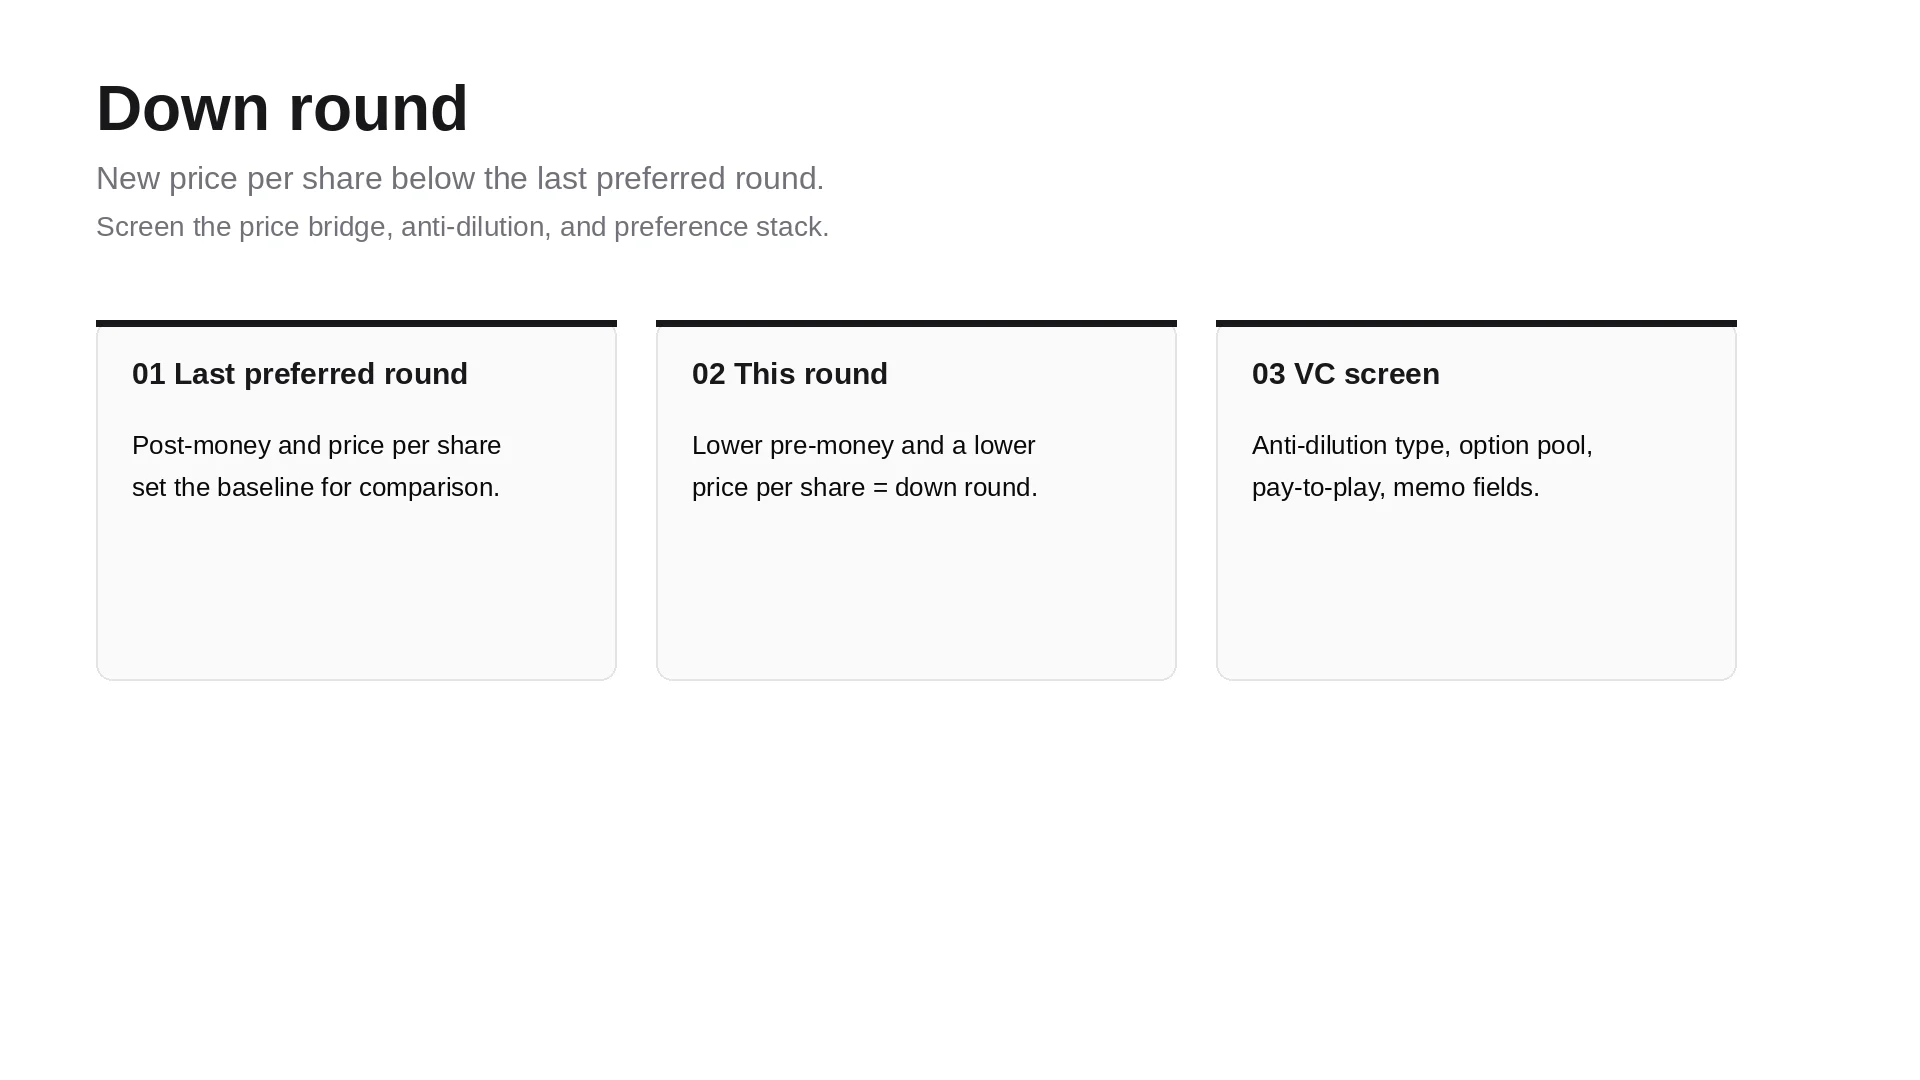
A down round is a financing in which a company sells new shares at a lower price per share than in its previous preferred equity round. In valuation terms, the new pre-money valuation sits below the post-money valuation of the last priced round. The company still raises cash. Existing preferred and common holders usually lose paper value, and anti-dilution terms often shift more of that loss onto common stock.
Analysts and associates at venture capital firms screen these deals constantly: not only whether the company needs the capital, but which terms rewrite the cap table and what belongs in the investment memo.
What a down round is
Compare two prices. Last round closed at a post-money valuation and a price per share for preferred stock. This round proposes a lower pre-money valuation and a lower price per share. That is a down round.
AngelList states the same test in plain language: the pre-money of the new round is lower than the post-money of the prior round. If those two numbers match, the round is flat. If the new pre-money is higher, the round is up.
The label is about price, not about whether the company grew. A company can hit product milestones and still take a down round when public comps reprice the sector, when the prior round was crowded and expensive, or when cash runway forces a quick close. The opposite is also true. Missed growth alone does not create a down round until a buyer sets a lower price in a term sheet.
Down round financing usually means a priced preferred round. A SAFE or convertible note bridge can postpone a price. It does not erase the later comparison when preferred stock is finally issued.
Down round vs flat round vs up round
| Up round | Flat round | Down round | |
|---|---|---|---|
| Price per share vs last preferred | Higher | Same | Lower |
| New pre-money vs prior post-money | Higher | Equal | Lower |
| Signal investors usually read | Momentum or denser evidence | Pause / reset without a cut | Reprice, distress, or both |
| Typical term pressure | Lighter | Mixed | Heavier (prefs, pay-to-play, pool) |
Headline valuation is the shorthand. Dilution and preference math decide who gets hurt. A clean down round with a 1x non-participating liquidation preference can leave common better off than a flat round stacked with participating preferred and a large option-pool refresh for new money.
Why down rounds happen
Four causes show up in diligence memos again and again.
Missed plan. Revenue, growth, or product milestones that justified the last price are not there. New money prices the gap.
Market reprice. Public multiples and private comps move. Carta's 6 February 2023 guide on down rounds noted that in Q3 2022, 12.5% of fundraises on Carta were down rounds on a pre-money basis, up from 5% in Q1 2022. That is a platform sample from a stressed period, not a 2026 rate. Use it as context for how often the label appears when markets reprice, not as a forecast.
Prior round overpricing. Competitive dynamics or exuberance set a price the next buyer will not match. The down round is a correction.
Cash pressure. Runway is short. Negotiating leverage falls. Price and protective terms move together.
Public examples travel with the label. AngelList cites Klarna's 2022 financing at a $6.7B valuation after a prior round near $45.6B. Named, dated, and extreme. Most portfolio downs are quieter and still trigger the same paperwork.
What a down round does to the cap table
New preferred shares land at a lower price. Ownership percentages for people who do not buy their share of the round fall. Three mechanics matter more than the headline cut.
Anti-dilution. Prior preferred holders often hold weighted-average or full-ratchet anti-dilution protection. The conversion price adjusts. Full ratchet is rare and severe. Broad-based weighted average is the market default. The adjustment issues more preferred-equivalent ownership to protected holders. Common stock, including founder and employee shares, absorbs more of the dilution.
Preference stack. New money adds liquidation preference at the new invested amount. Higher multiples or participating preferred grow the stack that must be paid before common sees exit proceeds.
Option pool and underwater grants. Employees with strike prices above the new fair-market value hold options that are out of the money. Boards often refresh the pool or reprice grants. That is more dilution, usually taken before or as part of the round for the benefit of new investors and retention.
Pay-to-play terms can force existing investors to buy their pro rata or lose anti-dilution or preferred status. That changes who sits on the post-round table as much as the price does.
Alternatives to a priced down round
Companies try to avoid printing a lower preferred price when they can. The usual paths:
- Cut burn and extend runway until evidence or comps improve.
- Raise a bridge round on a SAFE or convertible note so valuation is deferred.
- Add venture debt when revenue and lender covenants support it.
- Keep the headline closer to flat by granting harder investor terms instead. That can be worse for common than a clean price cut.
None of these is free. A bridge that fails still becomes a down round later, often with less time and a weaker story. Debt adds covenants and repayment risk. Harsh prefs at a flat price can strand common below a participating stack. The associate's job is to model the alternative that is actually on the table, not the slogan on the deck.
How a VC screens a down round
Founder explainers stop at stigma and survival. The desk that underwrites the check runs a shorter list.
1. Confirm it is actually a down round. Pull last-round price per share, share class, and post-money. Pull this round's pre-money, price per share, and option-pool shuffle. Do not trust a verbal "flat" if the pool expands for new money in a way that cuts the effective price.
2. Map anti-dilution. Which prior classes have protection? Weighted average or full ratchet? What is the as-converted ownership shift onto common? Link the charter language; do not summarize from memory.
3. Read the preference stack. Multiple, participating or non-participating, seniority, and whether prior prefs are being amended. A 1x non-participating down round and a 2x participating "rescue" are different deals.
4. Check pay-to-play and pro rata. Who must write a check to keep rights? Who is being crammed? What does that do to syndicate politics and follow-on reserves?
5. Option pool and people. Size of refresh, repricing plan, retention risk for key operators. Underwater equity without a plan is a diligence flag.
6. Separate company failure from market reprice. Missed plan needs an operating thesis. Market reprice needs a path to the next fundable evidence at the new price. Both can be true. The memo must say which claim the firm is underwriting.
What belongs in the memo. Price bridge from last round, ownership waterfall before and after, anti-dilution math, preference outcomes at two exit cases, reserve math, and the operating plan that makes the new price earn an up round later.
What does not belong. A founder pep talk, a general essay on "navigating hard times," or a recycled market narrative with no company-specific numbers. Those belong in a blog, not in the IC packet.
People who do this work for a living browse open roles on Venture Capital Careers and research firms by stage and sector while they learn the paperwork.
Frequently asked questions
What is a down round in venture capital?
A financing where new preferred shares are sold at a lower price per share than the previous preferred round, so the new pre-money valuation is below the prior post-money valuation.
Is a down round the same as a flat round?
No. Flat means the new pre-money matches the prior post-money. Down means it is lower. Terms can still be aggressive in a flat round.
How does a down round affect existing investors?
Preferred holders without protection lose paper value and ownership if they do not buy their share. Holders with anti-dilution receive conversion adjustments that push more dilution onto common. Fund marks and TVPI can fall when the write-down hits the portfolio.
How does a down round affect employees?
Options priced above the new fair-market value go underwater. Companies often reprice or grant new options, which dilutes the table further. Communication and a retention plan matter as much as the spreadsheet.
What is the opposite of a down round?
An up round: new price per share and pre-money above the prior round's post-money.
Can a company recover after a down round?
Yes. Recovery is an operating and financing fact pattern, not a slogan. Clean terms, enough runway, and evidence that supports a later up round are what change the story.
A down round is a price fact with term consequences. Screen the price, the anti-dilution, the preference stack, and the pool before the narrative. For the related paperwork, read anti-dilution, pay-to-play, liquidation preference, term sheets, bridge rounds, and venture debt. For the jobs that diligence these deals, start at Venture Capital Careers.
Related posts
Copy-ready VC associate job description template with responsibilities, skills, investing vs sourcing seat signals, interview scorecard, and how candidates should read a posting.
A practical career guide to venture capital fund operations: roles from accountant to CFO or COO, skills and proof of work, and how to evaluate the seat before you apply.
Prepare for analyst and associate VC interviews with 25 questions, answer frameworks, technical priorities, and role-level calibration.