Getting a job in venture capital means winning one of very few seats. Most firms run on a management fee budget with a handful of investors, so they hire when a new fund closes or someone leaves, and they fill most junior roles through referrals before or alongside a public posting. Candidates who get hired pick a realistic first seat, show proof that they can find and judge companies, apply where their background fits the firm's stage and sector, and prepare for a process that runs from a short screen through a memo or case to meetings with every partner.
Which VC jobs exist
A venture firm has two kinds of seats: the investing team, which finds and backs companies, and the platform and operations team, which supports the portfolio and runs the fund. Know which one you are applying for before you network, because the interview, the proof, and the next career step differ.
| Seat | Typical prior experience | What the job is |
|---|---|---|
| Analyst | 0 to 2 years, often banking, consulting, or a startup | Market maps, sourcing lists, first-pass screens, memo support |
| Associate | 2 to 4 years pre-MBA, or post-MBA | Sourcing, diligence, founder calls, memos, deal process |
| Principal or VP | MBA plus operating years, or internal promotion | Runs deals to close, first board seats |
| Partner | Senior operator, founder, or long venture record | Leads investments, sits on boards, helps raise the fund |
| Scout or venture partner | Any level, part-time | Sources deals, sometimes with a small allocation or deal-by-deal carry |
| Platform, talent, community, content | Recruiting, marketing, community, or operating roles | Helps portfolio companies hire, sell, and grow |
| Investor relations, finance, fund operations | Fund accounting, audit, IR, legal | LP reporting, capital calls, compliance, fund administration |
Fixed terms are common at the junior level. Union Square Ventures' 2026 analyst program, for example, hires two analysts for a fixed two-year term. Many pre-MBA associate seats work the same way. The venture capital career path covers what happens at each rung after you are in.
Platform and fund operations seats often outnumber junior investing seats at multi-stage firms. They are real jobs with their own ladders. Take one because the work fits, not as a short detour, since moving from platform to investing happens but is not automatic.
Which entry point fits your background
There is no single feeder, but each background maps to a first seat that is hard but realistic.
| Background | Realistic first seat | Evidence that travels | Common trap |
|---|---|---|---|
| Investment banking or PE | Analyst or associate, strongest at growth and later-stage funds | Modeling, process discipline, deal exposure | Answering every question like a banker; no view on founders |
| Consulting | Associate, platform strategy, corporate development into CVC | Structured problem solving, industry depth | No opinion on markets |
| Startup operator (product, growth, sales, engineering leadership) | Associate at early-stage funds, platform, later operating partner | Domain reps, founder network, shipped outcomes | Assuming the title maps one to one; little written judgment |
| Founder | Scout, partner at an emerging manager, associate at a specialist fund | Pattern recognition, network, credibility with founders | Waiting only for a brand-name fund |
| MBA | Associate, sometimes senior associate | Recruiting calendar, case skills, prior industry | Treating on-campus recruiting as the whole market |
| PhD, MD, or deep technical | Specialist analyst or associate in bio, climate, or deep tech | Technical diligence | No commercial translation; no sourcing habit |
Two checks keep this honest. First, search LinkedIn for people at your target firms who had your background before they joined. If nobody at a firm looks like you, that firm is a long shot. Second, read the team page: the mix of former bankers, operators, and scientists shows what the firm hires for.
Entry level matters for the long run. Ilya Strebulaev's study of 12,627 U.S. venture careers found junior entrants were 70 to 80 percentage points less likely to become senior VCs than people who entered at the middle level. A few years building inside a startup can be a faster route to a senior seat than a junior seat today. Life science funds are a separate market that often hires PhDs and MDs directly; see biotech venture capital for that track.
What VC firms screen for
Firms hire someone who adds to the deal funnel or improves a partner's decisions. A survey of 885 venture capitalists, summarized in the NBER Digest, found the median firm considered about 100 deals for every one it closed, and more than 30% of deals came through professional networks while about 30% were proactively self-generated. Candidates who can show they will add to those two buckets get attention.
What that looks like in a candidate:
- Sourcing. You find companies worth a call before they are widely known.
- Judgment. You can say why a market is attractive and why a company is or is not the right bet on it.
- Writing. A memo a partner can read in five minutes and act on.
- Domain. Enough depth to ask founders questions they have not heard from other investors.
- Analytical floor. You can read a deck, size a market from the bottom up, and spot numbers that do not reconcile.
- Reliability. You follow up, finish work, and do not create drag for partners.
Stage changes the weighting. Early-stage firms lean on sourcing, market views, and founder judgment. Growth and late-stage firms lean on financial analysis, unit economics, and diligence, which is why bankers convert more often there. The full skill breakdown is in venture capital skills.
Build proof before you apply
Proof of work turns "interested in VC" into a candidate a partner can evaluate. Ship these before you ask anyone for a job:
| Proof | What good looks like | Best for |
|---|---|---|
| Investment thesis | One or two pages on a sector: what changed, who is building, what a winning company looks like | Every investing seat |
| Market map | 15 to 40 companies segmented by business model or customer, with notes on who is raising | Analyst and associate |
| Two investment memos | A real or practice company with a clear yes or no, the risks, and what would change your mind | Associate and up |
| Sourced companies | Five early companies in your sector with a one-line reason each | Early-stage funds |
| Founder conversations | Notes from ten founder calls on what they need and how they pick investors | Early-stage and platform |
| Public writing | A newsletter, post, or teardown that shows your thinking | Optional; helps where the firm values content |
Scout programs and venture fellowships give the same signal with a firm's name attached. Treat them as proof, not as a guaranteed path to a full-time seat. The investment memo, investment thesis, and market map guides cover formats.
Where VC jobs come from
Seats open for three reasons: a new fund closes and adds fee budget, someone leaves, or a firm adds a sector or platform function. Since every hire is paid out of partner economics, few firms hire ahead of need.
- Referrals. A partner, portfolio founder, or former colleague puts your name forward. This is still the main route for many junior investing seats.
- Search firms. Larger funds sometimes run associate searches through buy-side recruiters. They rarely call career switchers unprompted, so reach out and ask specifically about venture roles.
- Firm career pages and partner posts. Small firms often post once, on their own site or a partner's LinkedIn or X, and close quickly.
- Job boards. The Venture Capital Careers job board lists open roles across VC firms by title and location. Sign up for alerts so new roles reach you the week they post.
Timing helps. Watch for fund closes announced in the press, new partners joining from operating roles, and platform hires at your target firms. Each one can signal a junior seat in the next few months. Use the companies directory to track each firm's stage, sector, and team. For a comparison of boards, see venture capital job boards.
How to screen a VC job posting
A weak search burns weeks on listings that were never a fit. Run each posting through six checks before you write a cover note.
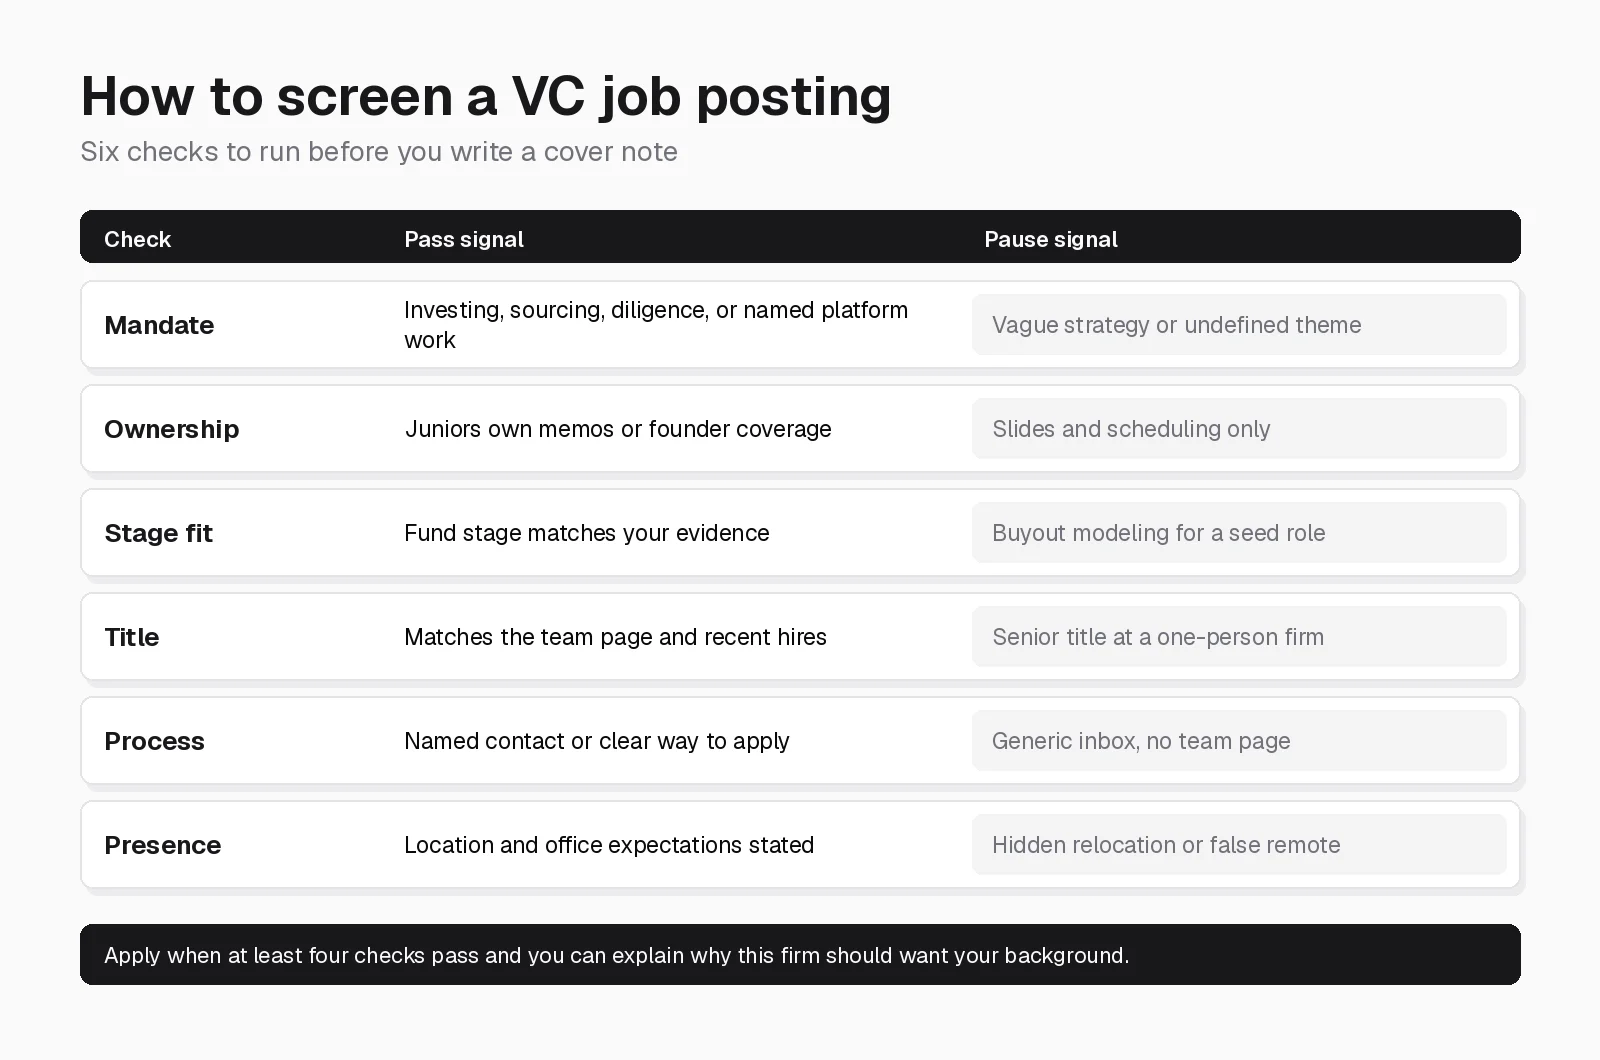
| Check | Pass signal | Pause signal |
|---|---|---|
| Mandate | Investing, sourcing, diligence, or named platform work with a clear owner | Vague "venture strategy," fundraising advisory, or an undefined theme |
| Ownership | Juniors own memos, workstreams, or founder coverage | Slide formatting and scheduling only, or an unpaid "fellow" role with no output |
| Stage fit | The fund's stage matches your evidence | Early-stage role asking for buyout modeling, or growth role with no analytical bar |
| Title | Matches the team page and recent hires | Senior title at a one-person firm, or associate title with partner-only economics |
| Process | Named contact, timeline, or a clear way to apply | Generic inbox, no team page, rolling post with no recent hires |
| Presence | Location and office expectations stated | Hidden relocation, or "remote" that means five days in office |
Pass when the posting fails mandate or ownership. Park a firm that is interesting but whose listing is unclear: follow the team and send a relevant note later. Run the same screen on roles found through the VC job board and firm sites.
Networking and outreach that gets replies
Most investors answer specific, useful notes and ignore generic requests for advice. A note that gets a reply has four parts:
- A reason for this person. Mention a portfolio company, a recent post, or the fund's focus.
- Something useful. One company or insight that fits their thesis, with a one-line reason.
- A small, clear ask. Fifteen minutes on whether your background fits their associate bar beats "any advice."
- One follow-up with new substance. Add another company or a revised memo rather than "just bumping this."
Start with associates and platform leads. They read inbound decks, filter candidates, and are more reachable than partners. Emerging managers are often more open to meeting new talent than established funds. Portfolio founders who vouch for how you work carry more weight than another investor contact. Do not message every partner at a firm on the same day. Templates are in venture capital cold email templates, and longer strategy in venture capital networking.
Tailor the resume and application to the firm
Before applying, know the firm's fund size, check size, stage, sectors, and three recent investments. Pick two portfolio companies you like and one you would question. That research shapes everything you send.
- Resume. One page. Lead with outcomes, ownership, and domain. Put any sourcing, investing, or startup work at the top. "Sourced 40 seed-stage fintech companies and brought three to partner meetings" beats "conducted startup research." See the venture capital resume guide and the analyst resume version.
- Cover note. Three short paragraphs: why this firm, what you bring that fits its stage and sector, and the proof. Reference a specific investment. See the VC analyst cover letter.
- Attach proof. A one-page memo or market map in the firm's sector is the strongest attachment you can send.
How VC recruiting works, from first call to offer
VC recruiting is unstructured compared with banking or private equity. A firm replacing someone may finish in a few weeks; a firm without urgency can take months. Expect to meet most of the team, because small firms want every partner to sign off.
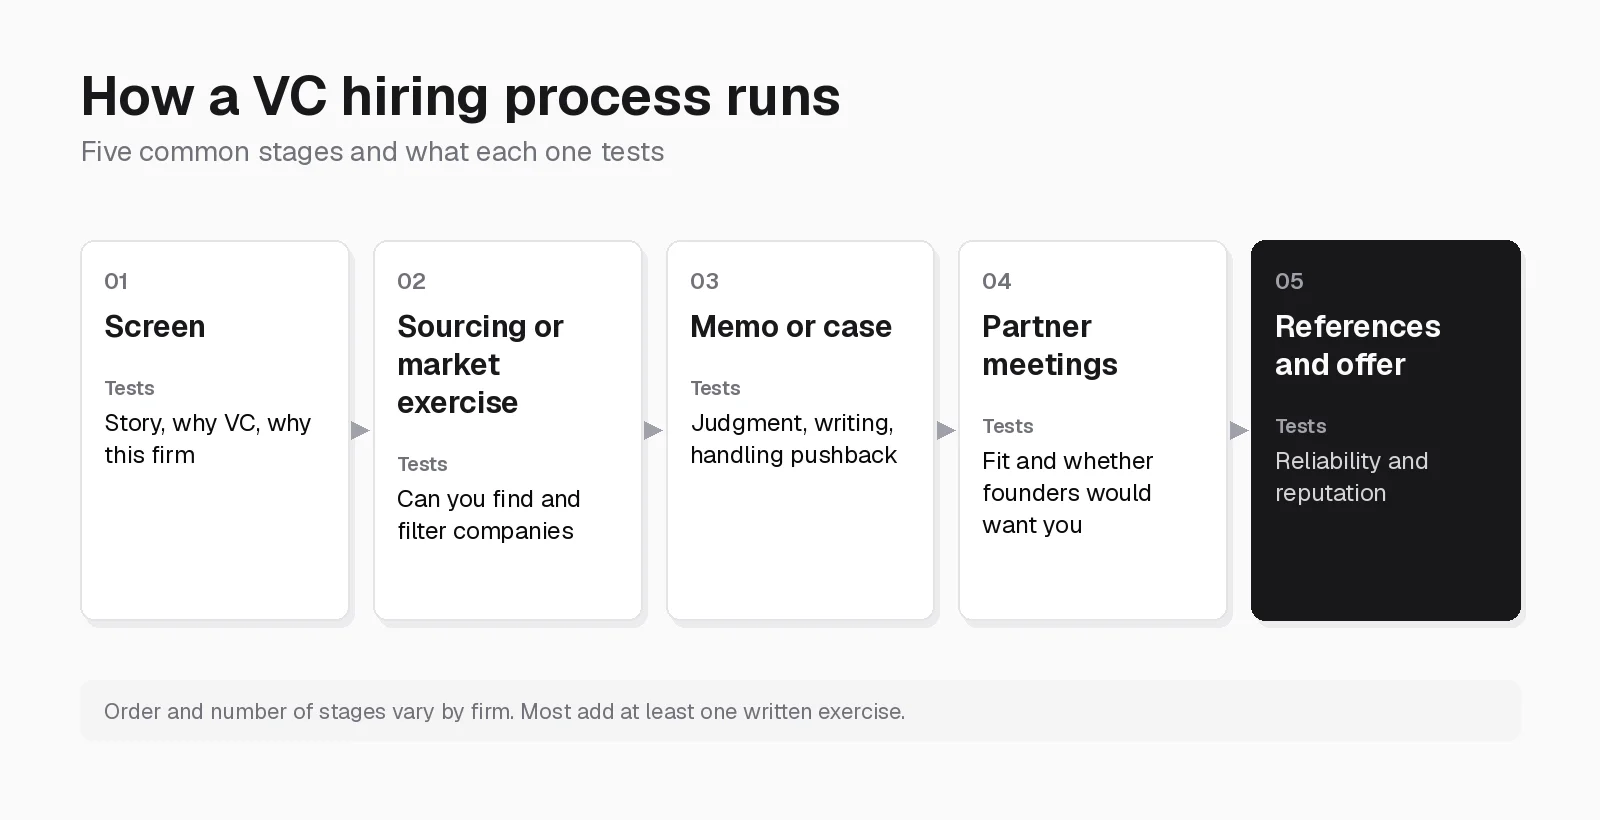
| Stage | Who you meet | What it tests | What to bring |
|---|---|---|---|
| Screen | Associate, principal, or talent lead | Story, why VC, why this firm, sector interest | A two-minute story and three sectors you follow |
| Sourcing or market exercise | Investment team | Whether you can find and filter companies | A market map and two or three companies the firm has not backed |
| Memo or case | Partner or panel, sometimes take-home | Judgment, writing, handling pushback | A memo with a clear recommendation and risks; practice defending it |
| Partner meetings | Each partner, often one to one | Fit, how you think, whether founders would want to work with you | Views on the firm's portfolio and one deal you would have passed on |
| References and offer | Former managers, founders you worked with | Reliability and reputation | Prepared references who can speak to specific work |
If you hear back within a day or two, it is usually good news. If not, follow up every week or two with something new. Case prep is in the case study interview guide.
What VC interviews test
Questions fall into five groups. In rough order of weight:
- Fit and background. Walk me through your resume. Why venture? Why this firm? Why now?
- Market and investment views. Which startup would you back and why? Which market should we avoid?
- The firm itself. What do you think of our portfolio? Which investment would you not have made?
- Experience. How did you add value on a deal, a sale, or a launch?
- Technical. Cap tables, dilution, SAFEs, unit economics, market sizing, and how a fund makes money through management fees and carry.
Formal modeling tests are less common than in private equity. A written memo or market exercise is more common. Stand behind your views when pushed; folding at the first challenge reads as weak conviction. Practice out loud with the VC interview questions list and, for cap table drills, the cap table interview guide.
Pay and the offer conversation
Junior VC pay is mostly cash; carry arrives later and takes years to pay out. Typical U.S. bands from the Venture Capital Careers salary guide:
| Role | Typical base | Typical bonus | Carry |
|---|---|---|---|
| Analyst | $70K to $115K | $5K to $25K | Rare |
| Associate | $100K to $175K | $10K to $50K | Sometimes small or deferred |
| Principal or VP | $175K to $275K | $30K to $125K | Often meaningful if partner-track |
Fund size drives most of the range, since salaries come out of the management fee. Before accepting, ask:
- What is the term, and have juniors been promoted in the last two fund cycles?
- Who did this partner hire before, and where are those people now?
- Will I get recorded credit for deals I source?
- Is there carry, when does it vest, and what happens to it if I leave?
- When was the current fund raised, and when does the firm expect to raise the next one?
- What share of my time goes to sourcing, diligence, portfolio work, and admin?
- What are the in-office expectations?
A famous firm where juniors never own work can be a weaker first job than a smaller fund where you lead deals. Mike Dauber of Amplify Partners advises checking firm size, how past juniors were promoted, and whether the firm raises a new fund every two to three years before taking a first venture job. Negotiation tactics are in VC associate offer negotiation.
How long a VC job search takes
Most serious searches take several months alongside a full-time job, and longer for career switchers who are still building proof. A realistic sequence:
| Phase | Focus | Done when |
|---|---|---|
| Weeks 1 to 4 | Pick seat type and 20 to 40 target firms; write the thesis; rebuild the resume | You can explain in one sentence why each firm should hire you |
| Months 2 to 3 | Ship a market map and a memo; run founder calls; send targeted outreach; apply to screened roles the week they post | Conversations are turning into referrals |
| Months 3 to 6 and beyond | Focus on the fund segment that responds; drill interviews; revisit platform seats | Interviews are reaching partner meetings |
Track artifacts shipped and referrals earned, not messages sent. Internship candidates follow a different calendar, covered in how to get a venture capital internship.
Adjacent seats if the first search stalls
Some backgrounds need one more step before a VC seat. Each of these builds evidence firms hire for, and each has a known path back to investing:
- Startup operating role at a venture-backed company in your target sector, ideally one owned by a target firm's portfolio.
- Corporate venture capital at a strategic investor, where banking and consulting skills transfer directly. See corporate venture capital.
- Growth equity or private equity, for candidates whose strength is modeling and diligence.
- Platform roles at a venture firm, such as talent, community, or portfolio operations.
- Scout or angel investing, to build a record of sourced deals while keeping your current job.
FAQ
How hard is it to get a job in venture capital?
Hard compared with most finance roles. Firms are small, hire one or two people at a time, and fill many seats through referrals. Candidates with proof of sourcing and judgment, a fit with the firm's stage, and warm introductions do far better than candidates who only apply online.
Do I need an MBA to work in venture capital?
No. An MBA helps with the associate and principal track and gives you a recruiting calendar, but it is neither required nor enough. TechCrunch reported in September 2025 that the share of mid-career venture professionals with MBAs fell from 44% in the early 2000s to 32%. See venture capital without an MBA.
Can you get a VC job straight out of college?
Yes, at funds that run analyst programs, but those seats are few. Internships during school and two years in banking, consulting, or a startup are the more common route. See how to become a venture capital analyst.
Should I target analyst or associate?
Target the title the firm uses for your experience. Some firms have no analysts; others call pre-MBA hires associates. Read the job description and the team page rather than a generic ladder.
Can operators get VC jobs without finance experience?
Yes, especially at early-stage funds that value founder judgment, go-to-market depth, or technical diligence. You still need written memos and a sourcing habit. See how to become a venture capitalist for the paths by background.
Should I pay for a VC course or fellowship?
Only if it gives you network access or forced practice you would not get alone. Be cautious of any program that implies a placement guarantee.
Browse open roles on the Venture Capital Careers job board, research firms in the companies directory, and create an account to get new VC roles by email.
Related posts
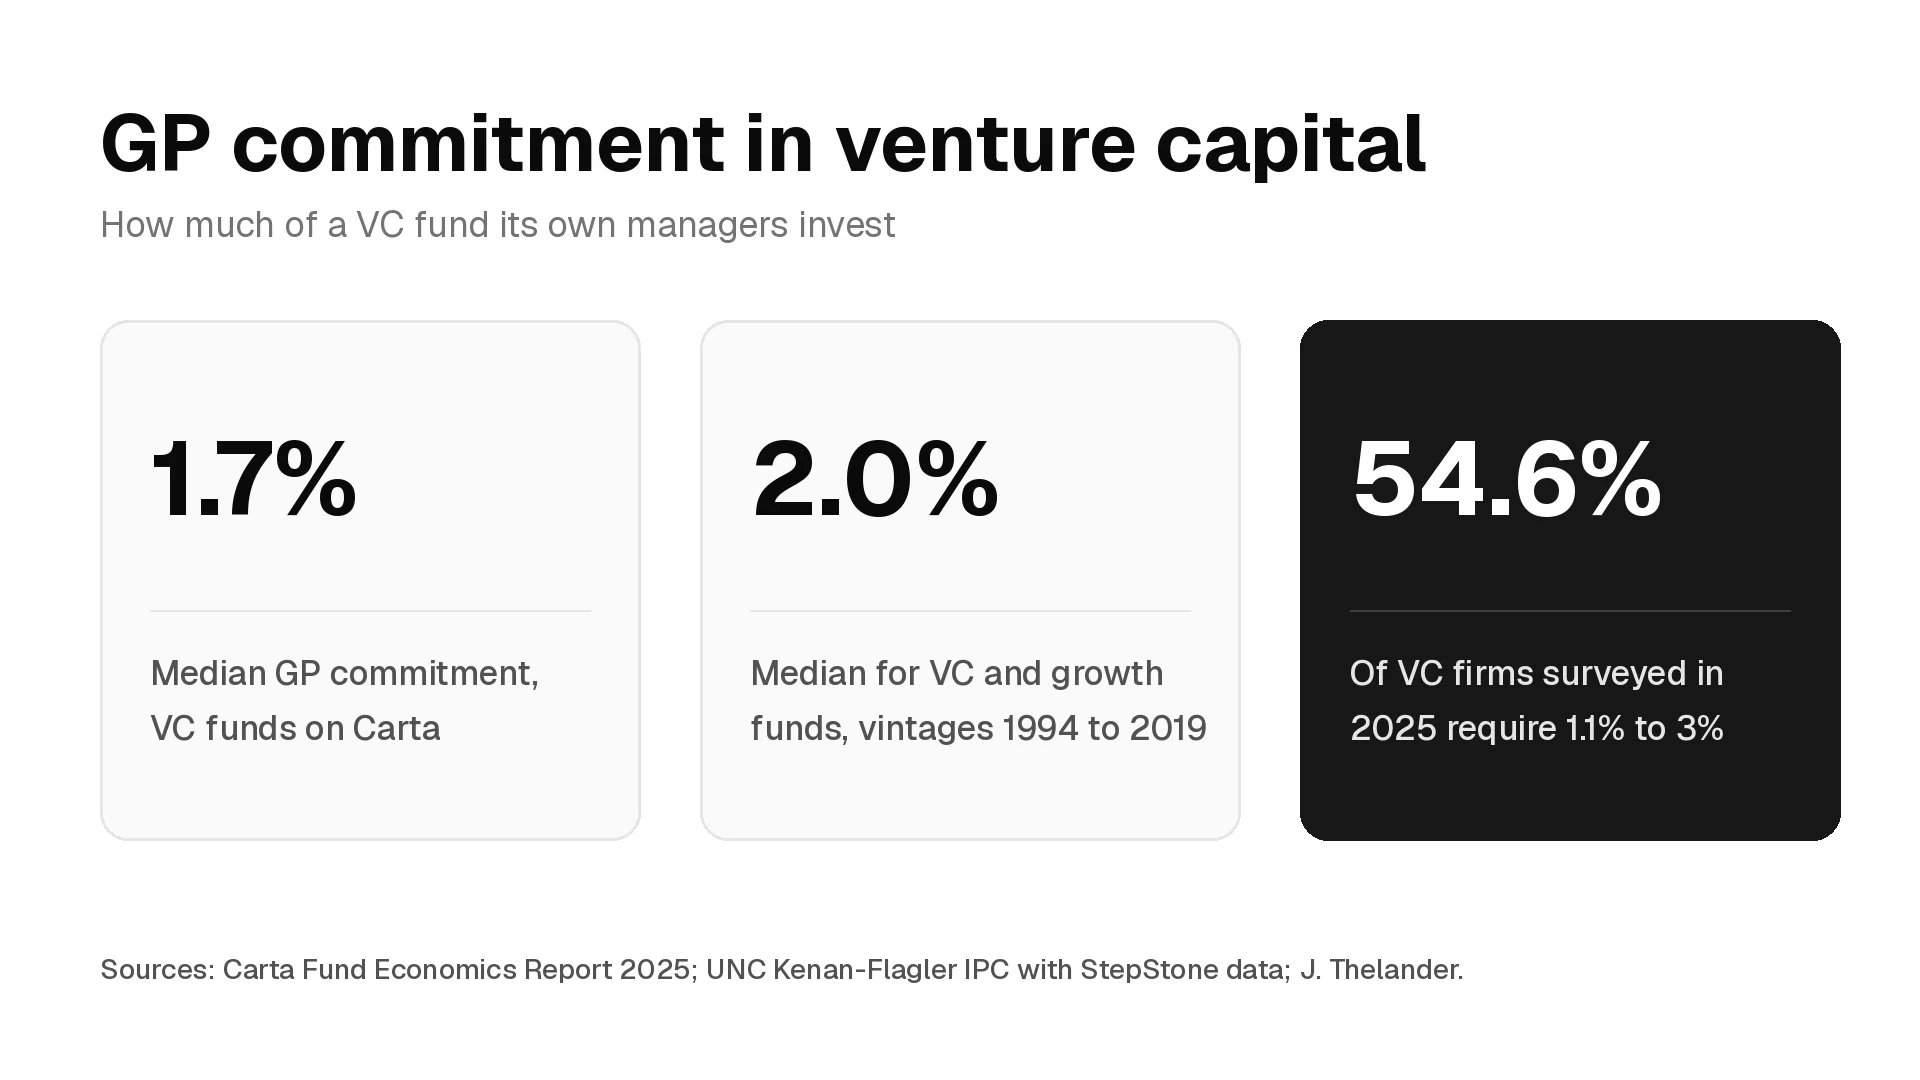
What a GP commitment is, how large it is in venture capital, how GPs fund it, where it sits in the LPA, what the returns evidence says, how firms split it across partners and principals, and what to ask before you accept a role with carry.
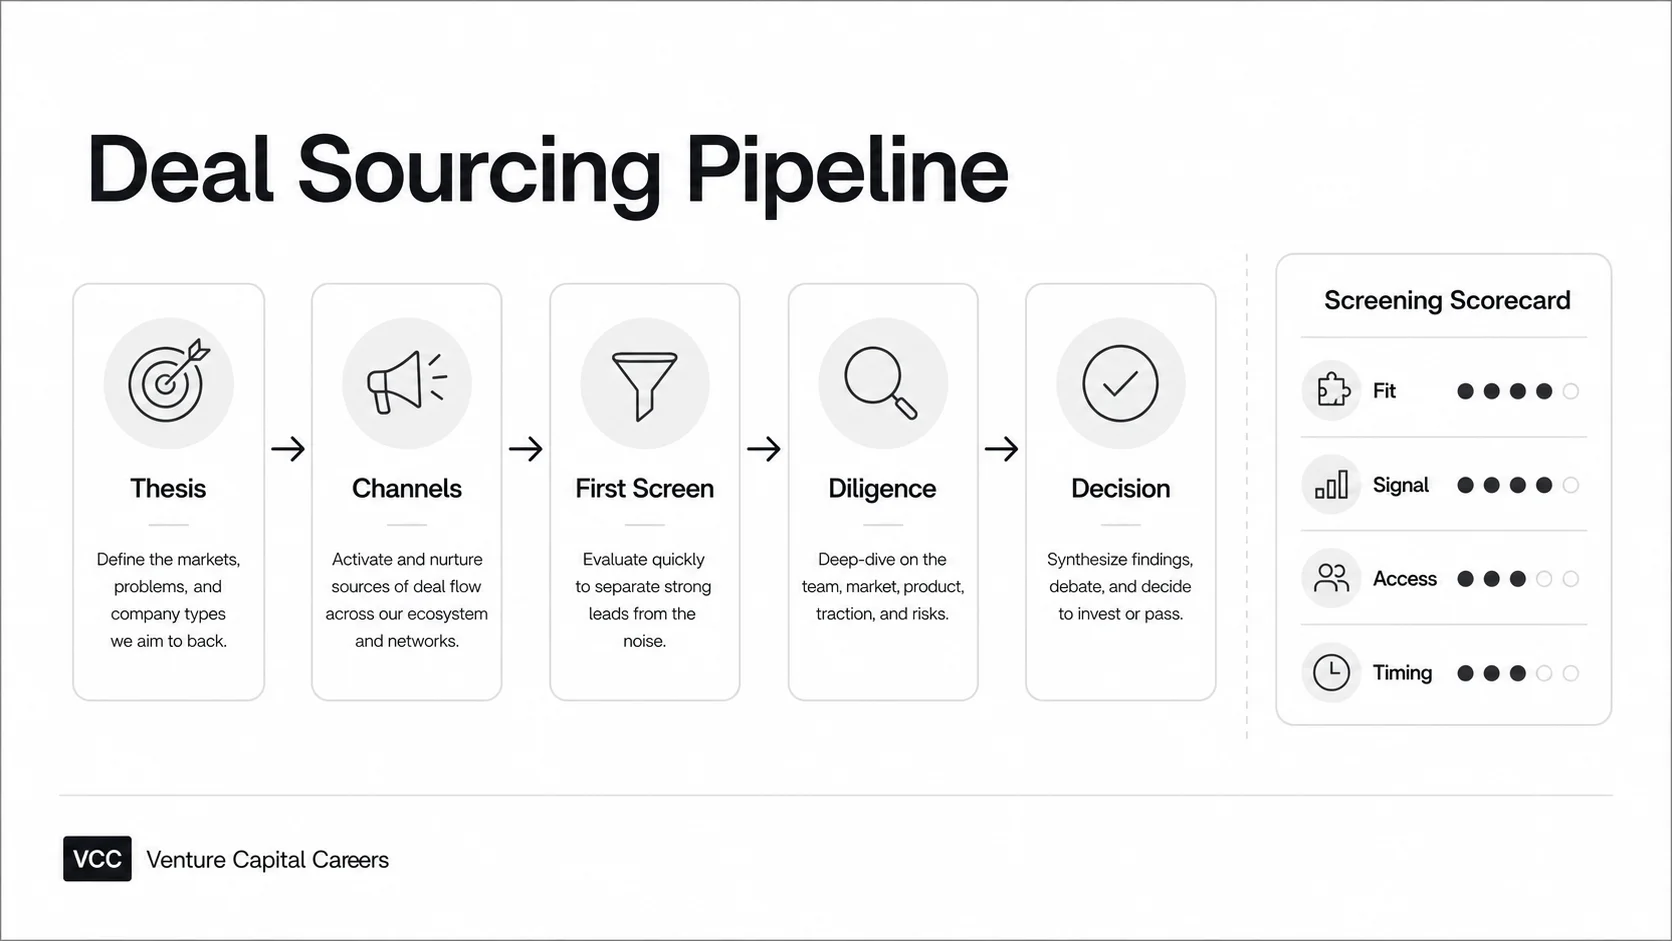
Most closed VC deals start with a relationship. See where deals come from by stage, how to work each sourcing channel, which signals show up early, and how analysts run a weekly sourcing process.
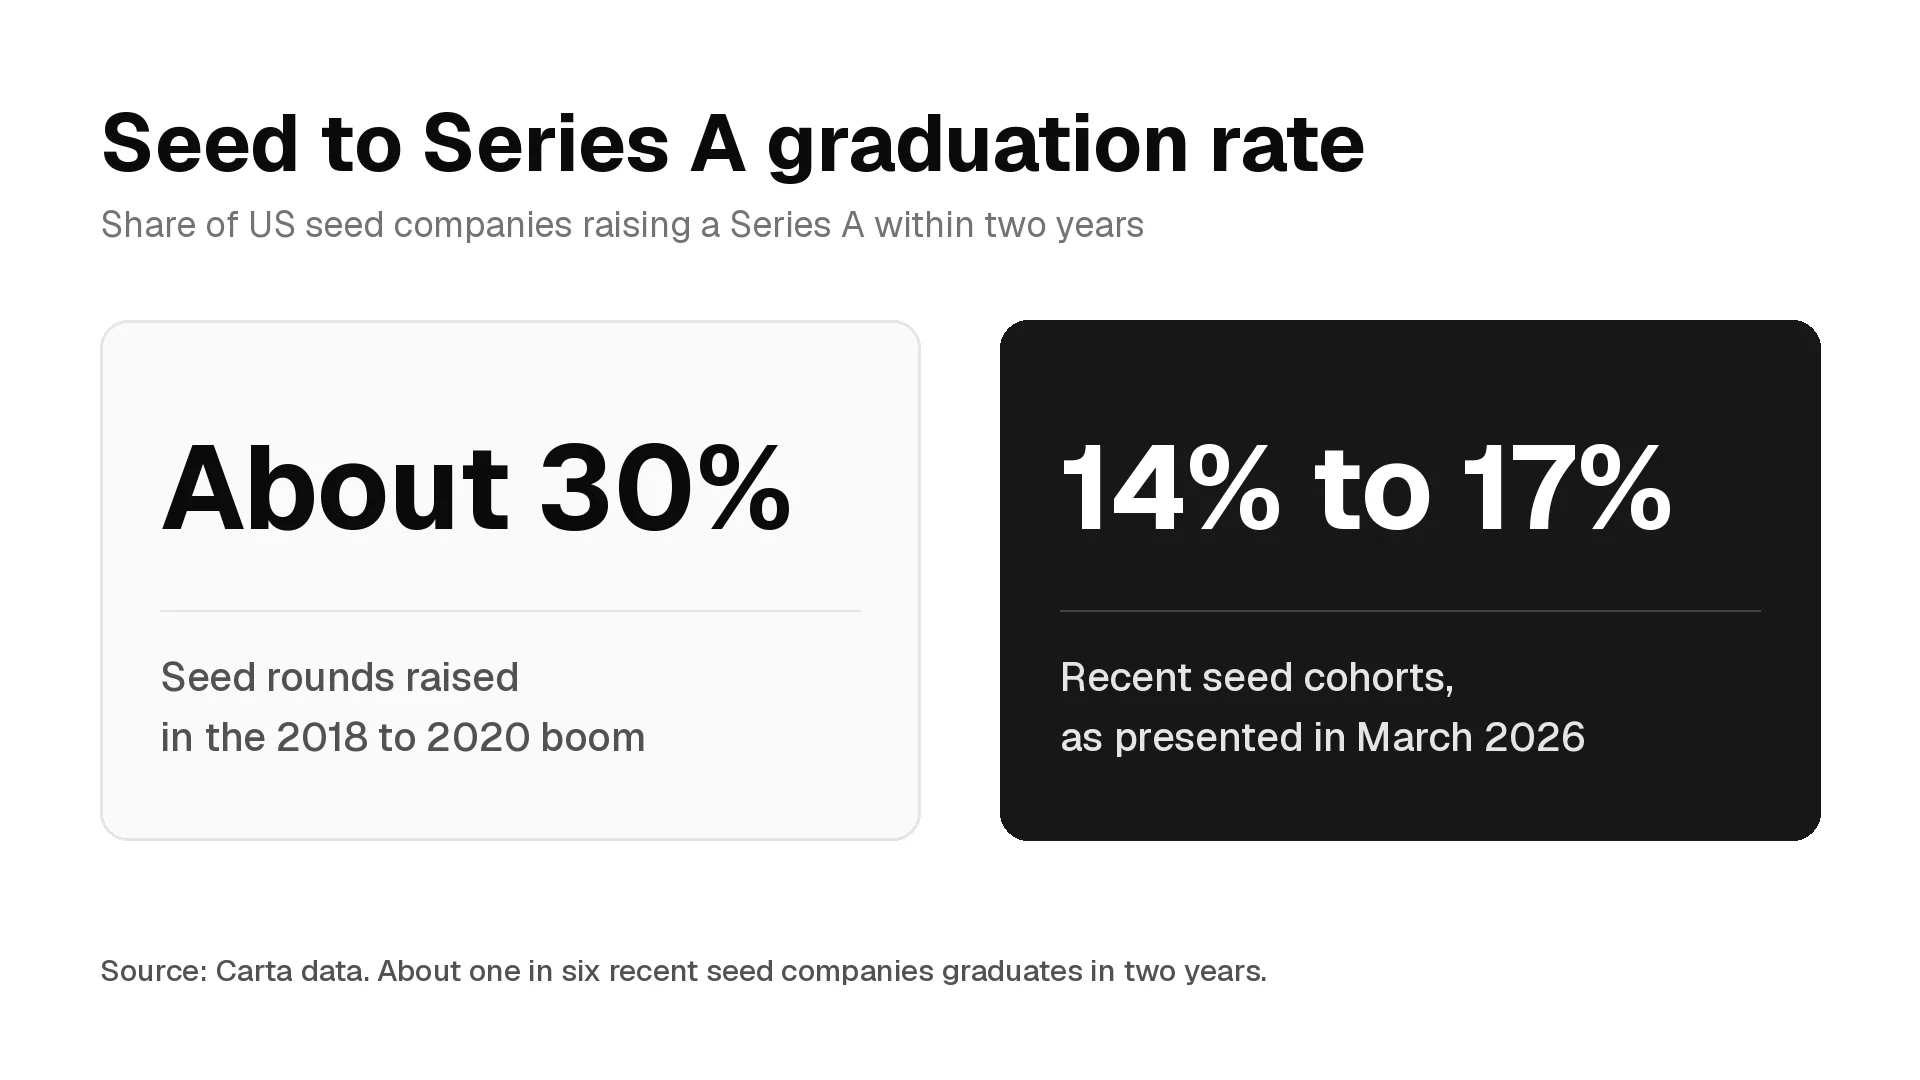
Seed to Series A graduation rates by cohort from Carta and Crunchbase, how long the jump takes, why rates fell after 2021, why published figures disagree, and how seed and Series A firms use the rate for reserves, LP reporting, portfolio reviews and interviews.