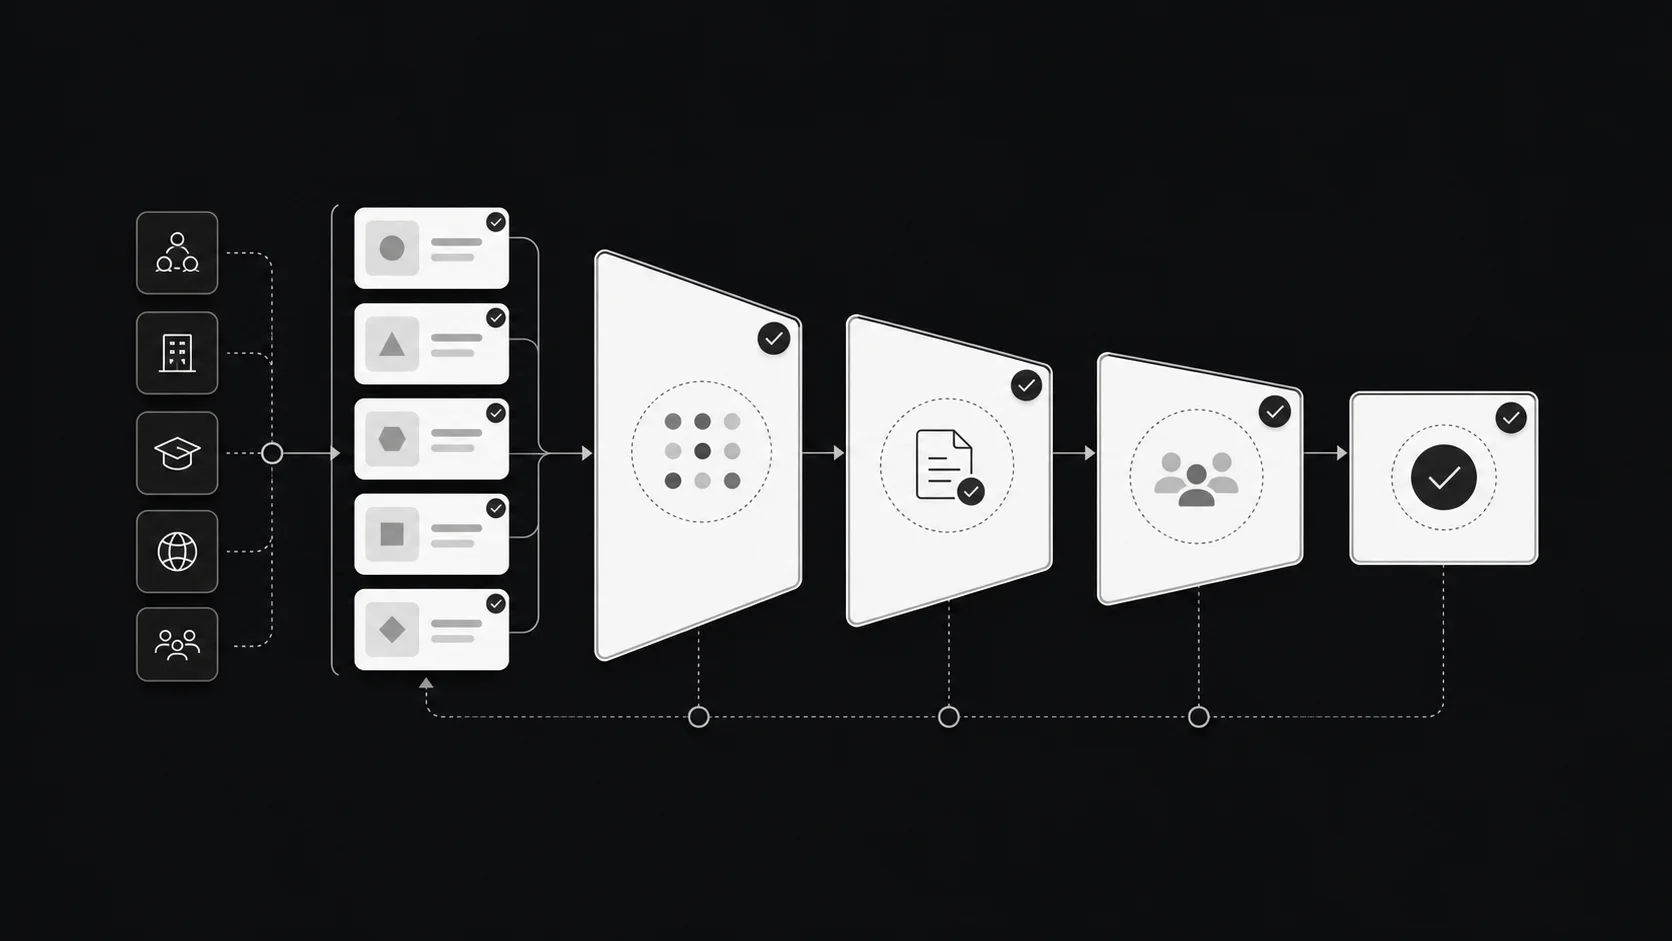
Deal flow in venture capital is the stream of investment opportunities that reaches a firm and the funnel those opportunities move through before a check is written. It is measured two ways. Volume counts how many companies the firm sees in a period. Conversion counts how many move from first look to meeting, partner review, diligence, term sheet, and close.
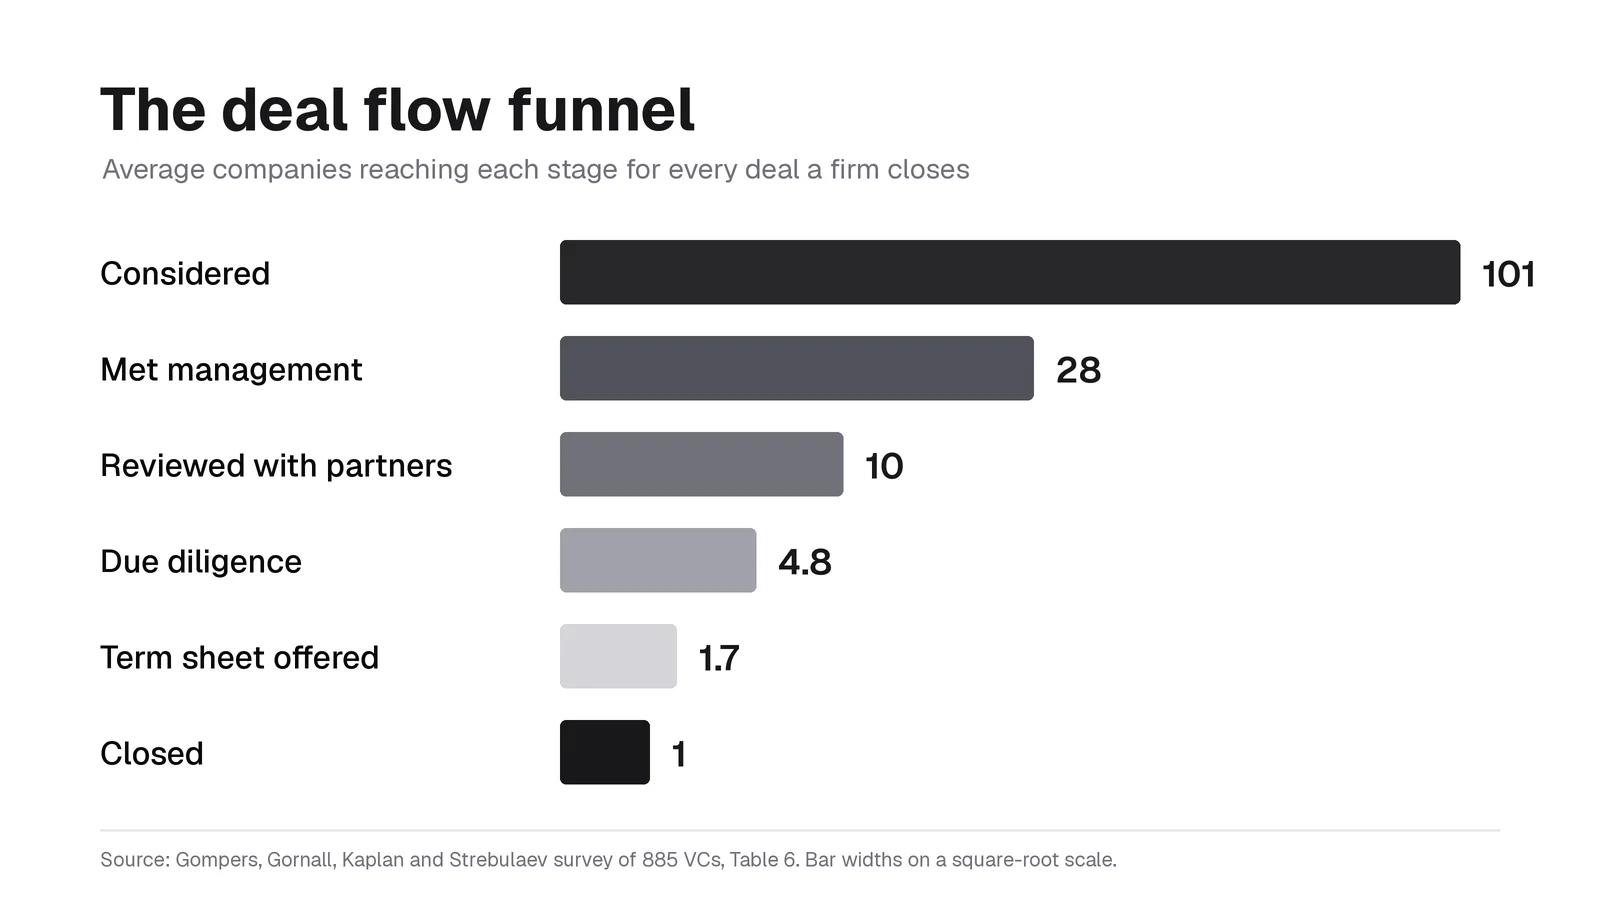
The best measured version of that funnel comes from a survey of 885 venture capitalists at 681 firms by Paul Gompers, Will Gornall, Steven Kaplan, and Ilya Strebulaev, published in the Journal of Financial Economics in 2020 (NBER Working Paper 22587). For every deal a firm closed, it considered about 101 companies, met about 28 management teams, took 10 to a partner meeting, ran diligence on about 5, and offered 1.7 term sheets.
What is deal flow in venture capital?
Deal flow is the rate at which a venture firm receives and evaluates potential investments, plus the pipeline that sorts them. A firm with "good deal flow" sees enough relevant companies, early enough, to fill its target number of investments with companies it actually wants to back.
Three things are bundled into the term:
- Volume. Companies logged per week, month, or year.
- Quality. The share of those companies that fit the fund's investment thesis on stage, sector, geography, and check size, and the share that go on to raise strong next rounds.
- Access. Whether the firm can win the deals it wants once it decides to compete.
Investment banks, private equity funds, and angel investors use the same word for their own pipelines. In venture capital the funnel is unusually wide because a fund needs many shots to find the few outliers that drive returns, a pattern covered in the venture capital power law.
The deal flow funnel, stage by stage
Most firms run a version of the same sequence. A team member logs a company, screens it, meets the founders, brings it to the partners, runs diligence, offers terms, and closes. Each stage removes most of what entered it.
| Stage | What happens | Companies per closed deal (all firms) | Early-stage firms | Late-stage firms |
|---|---|---|---|---|
| Considered | Company is logged and gets a first look at deck, data, or intro note | 101 | 119 | 94 |
| Met management | At least one call or meeting with the founders | 28 | 34 | 24 |
| Reviewed with partners | Champion presents the company at a partner or pipeline meeting | 10 | 11 | 10 |
| Due diligence | Formal work on market, product, customers, financials, and references | 4.8 | 4.6 | 4.4 |
| Term sheet offered | Firm proposes price and terms | 1.7 | 1.5 | 2.3 |
| Closed | Legal documents signed, capital wired | 1 | 1 | 1 |
Source: Gompers, Gornall, Kaplan, and Strebulaev, Table 6, averages per closed deal (NBER w22587).
First look and screen
The first cut is the largest. About three of every four companies considered never get a founder meeting. The screen is usually a few minutes against fixed criteria such as stage, sector, geography, round size, and whether the firm can lead. Speed matters more than depth here, because a slow reply costs the firm the founder's attention.
Founder meeting
The first call tests the team, the problem, and why now. One person at the firm owns the relationship from this point. If the meeting goes well, there may be a second call with another investor or a product demo before the company goes to the partnership.
Partner review
The deal owner presents the company at a weekly pipeline or partner meeting. Roughly one in three founder meetings reaches this stage. The partners decide whether to spend diligence hours, which are the scarcest resource in the funnel. Group judgment at this step is where pattern matching helps and where it misfires.
Due diligence
About half of partner-reviewed companies go into formal diligence. The same survey reports that the average closed deal took 83 days and 118 hours of diligence, with about 10 reference calls. Early-stage firms averaged 73 days and 81 hours. Late-stage firms averaged 106 days and 184 hours. The venture capital due diligence process explains what gets checked.
Term sheet and close
The investment committee approves terms, and the firm issues a term sheet. Not every offer closes. Firms offered 1.7 term sheets per closed deal, a close rate of roughly 60%, because other firms bid on the same companies. Late-stage firms offered about 50% more term sheets per close than early-stage firms, which the authors read as more competition and less proprietary access at later stages.
How many deals a VC firm sees in a year
The median firm in the survey considered about 200 companies a year, met about 50 management teams, took 20 to partners, ran diligence on 12, offered 5.5 term sheets, and closed 4 deals. Early-stage firms considered a median of 250 companies a year, and late-stage firms 100.
The ratio of companies considered per closed deal varies by sector. IT-focused investors considered about 151 companies per investment, and healthcare investors about 78.
These figures count companies a firm logged as "considered." Firms that log every cold email will report far larger top-of-funnel numbers than firms that only log companies someone actually reviewed. Compare funnels only when the definition of a logged deal matches.
Time is the real constraint. Respondents reported a 55-hour work week, with about 15 hours on sourcing and 7 on networking. Volume beyond what a team can screen well does not add returns. It adds noise.
How to size deal flow for a target number of investments
The per-close ratios turn a fund's plan into a weekly workload. Take a seed fund that plans six new investments a year and uses the early-stage averages above.
| Stage | Early-stage ratio per close | Needed for 6 investments | Per week (50 working weeks) |
|---|---|---|---|
| Considered | 119 | 714 | about 14 |
| Met management | 34 | 204 | about 4 |
| Reviewed with partners | 11 | 66 | about 1.3 |
| Due diligence | 4.6 | about 28 | about 0.6 |
| Term sheets offered | 1.5 | 9 | n/a |
| Closed | 1 | 6 | n/a |
At 81 hours of diligence per closed deal, six closings imply close to 490 hours of diligence on the companies the fund backs, before counting diligence on deals it lost or dropped.
Use the model in reverse to diagnose a pipeline. A fund that logs 700 companies but holds only 80 first meetings has a screen that is too tight, or a top of funnel full of off-thesis companies. A fund that reaches 30 diligences and issues 2 term sheets is spending diligence hours on companies the partnership was never likely to back.
Where VC deal flow comes from
The same survey asked where closed deals originated.
| Source | Share of closed deals (all firms) | Early-stage | Late-stage |
|---|---|---|---|
| Professional network | 31% | 31% | 25% |
| Proactively self-generated by the firm | 28% | 23% | 42% |
| Referred by other investors | 20% | 22% | 17% |
| Inbound from company management | 10% | 12% | 7% |
| Referred by portfolio companies | 8% | 9% | 4% |
Source: Gompers, Gornall, Kaplan, and Strebulaev, Table 5 (NBER w22587).
About six in ten closed deals came through a relationship of some kind. Late-stage firms generated far more of their own deals, which fits a model where growth investors map a market and call companies that already show traction. Cold inbound produced only one deal in ten, though it often makes up a much larger share of what arrives.
The tactics for building each channel, from referral networks to thematic market maps and scout programs, are the subject of venture capital deal sourcing.
Deal flow vs deal sourcing
Deal sourcing is how a firm finds companies. Deal flow is everything that happens to the companies once found, including the volume, the pipeline stages, the conversion rates, and the record of each decision.
A firm can source well and still manage deal flow badly. It meets strong founders and then loses them to slow follow-up, missing notes, or a partner meeting that never gets to the company. The reverse also happens. A tidy pipeline with weak sourcing fills with companies nobody at the firm wants to back.
How VCs track and manage deal flow
Every serious firm keeps a single pipeline record, whether in a spreadsheet, a shared database, or a venture CRM. The tool matters less than whether every company has an owner, a stage, and a next step.
Fields a deal record needs
| Field | Why it matters |
|---|---|
| Company, website, sector, stage, location | Lets the team filter by thesis fit and avoid duplicate outreach |
| Source channel and referrer | Shows which channels produce companies that advance |
| Date first logged and date of last touch | Exposes stale deals and slow response times |
| Deal owner | One accountable person per company |
| Current stage | Maps to the funnel above |
| Round size, lead status, and timing | Tells the team when a decision is due |
| Next step and due date | Keeps the company moving or formally closed |
| Pass reason (if declined) | Feeds pass analysis and future follow-up |
| Follow-up date for passes | Brings back companies that were too early |
The weekly pipeline meeting
Most firms review the pipeline once a week. New companies get a quick yes or no on a first meeting. Active companies get a decision on the next stage. Companies with no movement in two or three weeks are either given a next step or closed out with a reason. Investors who joined from banking or consulting will recognize the format as a deal review. The difference is the volume of early companies with little data.
Pass notes and the "too early" list
Passes are data. A short pass note, written the day of the decision, records why the company did not fit and what would change the answer. Firms that revisit this list each quarter catch companies that were too early at seed and are now raising the next round. The same list later shows which passes were mistakes.
Deal flow metrics to track
| Metric | How to calculate | Benchmark from the survey (all firms) |
|---|---|---|
| Companies logged | Count per month, by source channel | Median 200 considered per year |
| Meeting rate | First meetings ÷ companies considered | About 28% (28 of 101) |
| Partner review rate | Partner reviews ÷ first meetings | About 36% (10 of 28) |
| Diligence rate | Diligences ÷ partner reviews | About 48% (4.8 of 10) |
| Term sheet rate | Term sheets ÷ diligences | About 35% (1.7 of 4.8) |
| Win rate | Closings ÷ term sheets offered | About 60% (1 of 1.7) |
| Time to first response | Days from logged to first reply | No survey benchmark, so track the trend |
| Time in stage | Days a company sits at each stage | Track the trend against the 83-day average close |
| Channel yield | Partner reviews or closings ÷ companies, by source | Compare channels inside the firm |
| Missed-deal rate | Passed companies that later raised a strong round ÷ all passes | Internal only |
Channel yield and missed-deal rate are the two numbers most firms skip and the two that change behavior. If portfolio referrals produce partner reviews at three times the rate of inbound forms, the next quarter's time should shift toward portfolio founders. If passed companies keep raising strong Series A rounds, the screen is wrong, not the volume.
What good deal flow looks like
Good deal flow has four properties, and raw volume is not one of them.
- On thesis. Most companies logged fit the fund's stage, sector, and check size.
- Early. The firm meets companies before the round is shopped, often months before.
- Converting. Each channel produces companies that reach partner review, not just logged names.
- Compounding. Founders the firm met, backed or not, send the next founders.
"Proprietary deal flow" is the claim that a firm sees deals others do not. The survey's 1.7 term sheets per closed deal suggests many funded deals were contested. Early-stage firms faced less competition than late-stage firms, so proprietary access is more realistic at seed than at growth. A firm that wins contested deals through speed, founder trust, or a reputation for help often has an advantage worth as much as true exclusivity.
Volume still has a case. Returns concentrate in a few companies, and a company the firm never saw cannot be in the fund. The answer is a fast, honest first screen, not a narrower funnel. Investors who back companies others pass on, covered in non-consensus investing, need the widest top of funnel of all.
How to increase deal flow
Increasing deal flow means adding relevant companies at the top without breaking the screen.
- Write down the thesis and publish it. A clear thesis tells founders and referrers what to send and filters off-thesis inbound.
- Make inbound easy and fast. A short intake form and a response within days, even if the answer is no, earn more referrals than silence.
- Track referrers and thank them. Close the loop with the person who made an introduction, whatever the outcome.
- Build thematic market maps. List the companies in a target category and contact the strongest before they raise.
- Cover the feeders. Accelerator demo days, university spinout offices, angel groups, and scout networks bring early companies in volume.
- Use portfolio founders. Portfolio referrals were 8% of closed deals in the survey, and the share grows as a firm's portfolio grows.
- Revisit passes. The "too early" list is free deal flow.
Each of these is a sourcing tactic. The pipeline discipline in the sections above decides whether the extra companies turn into investments.
Deal flow software for venture capital
Deal flow software is the system a firm uses to log companies, assign owners, move deals through stages, and report on the funnel. Most tools fall into four categories.
| Category | What it does | When a firm adds it |
|---|---|---|
| Spreadsheet or shared database | Manual pipeline with custom stages | Solo GPs and first-time funds with a few hundred companies a year |
| Venture CRM | Pipeline stages, relationship history pulled from email and calendars, referral tracking | When several people source and duplicate outreach starts |
| Company data platforms | Funding history, headcount, and growth signals for market mapping | When the firm runs outbound sourcing by theme |
| Intake forms and deck trackers | Structured inbound submissions that feed the pipeline | When inbound volume outgrows a shared inbox |
The test for any tool is whether the team keeps it current. A CRM with stale stages produces wrong conversion rates, which is worse than no rates at all. Firms usually move off a spreadsheet when relationship history starts living in individual inboxes instead of the shared record.
Who handles deal flow inside a VC firm
The survey's average firm had 14 employees and 5 senior investment professionals, so pipeline work is spread across a small team. Titles vary by firm, but the split usually looks like this.
| Role | Typical deal flow work |
|---|---|
| Analyst | Logs companies, runs first screens, builds market maps, keeps the CRM current, prepares pipeline meeting notes |
| Associate | Takes first meetings, owns companies through partner review, drafts screening memos, runs parts of diligence |
| Principal | Sources independently, champions deals at partner meetings, leads diligence on smaller rounds |
| Partner | Decides which companies get diligence and term sheets, owns referral relationships, sits on the investment committee |
| Scout or venture partner | Refers or invests in early companies from a personal network, sometimes in exchange for a share of returns |
| Platform team | Runs events, founder communities, and inbound programs that feed the top of the funnel |
For junior investors, deal flow work is the job. It is also the most visible part of it, because partners see who brings companies into the pipeline, who follows up, and whose screening notes hold up at partner review.
How to talk about deal flow in a VC interview
Interviewers ask about deal flow to test whether a candidate understands the work. Expect versions of "How would you source deals for us?", "Walk me through a company you would bring to the partnership," and "How would you manage 50 inbound decks a week?"
Strong answers use the funnel. Name a channel and why it fits the firm's thesis. Describe a screen with three or four criteria and a time limit. Bring one company, explain where it sits in the funnel, and say what diligence would need to show. Know that roughly 1 in 100 companies considered gets funded, and that time, not deck count, limits a firm. The venture capital interview questions guide and the case study interview walkthrough cover the formats. A short investment memo on one company is a common take-home.
Analyst and associate roles that run a firm's pipeline are listed on the Venture Capital Careers job board, and each firm's profile on the companies directory shows its stage and focus.
Common deal flow mistakes
Counting volume as quality
A thousand off-thesis decks is a sorting cost, not a pipeline. Measure partner reviews per channel instead of companies logged.
Not measuring the middle of the funnel
Firms that count only decks received and deals closed cannot tell which stage is broken. Track every stage.
Letting the pipeline go stale
Companies sitting at "met founders" for two months with no next step distort every rate. Close them out with a reason.
Slow responses to founders
A two-week reply to a strong founder tells that founder, and the people they talk to, where the firm ranks them.
Ignoring passes
Without pass notes and follow-up dates, a firm repeats the same screening errors and misses companies that were only early.
Relying on one channel
A pipeline fed only by other investors often receives deals after those investors passed. Mix network, outbound, portfolio, and inbound.
Frequently asked questions
What is deal flow in simple terms?
Deal flow is the number and quality of investment opportunities an investor receives and reviews over a period, and the process used to sort them into investments.
How many deals does a VC look at before investing?
In the Gompers, Gornall, Kaplan, and Strebulaev survey, firms considered about 101 companies for every deal they closed. The median firm considered about 200 companies and closed 4 deals a year.
What percentage of startups get VC funding from a firm's pipeline?
About 1% of companies a firm considers end in a closed investment from that firm. About 28% get a founder meeting and about 5% reach formal diligence.
What is a good deal flow conversion rate?
The survey averages are a reasonable baseline: about 28% of companies considered to a first meeting, about 10% to partner review, about 5% to diligence, and about 1.7% to a term sheet. A firm far above those rates may be screening too tightly at the top, and one far below may be logging too much off-thesis volume.
What is proprietary deal flow?
Proprietary deal flow means seeing and winning companies that other investors do not see or cannot access. Survey evidence suggests it is rarer than firms claim, especially at later stages, where firms offered more term sheets per closed deal.
What is the difference between deal flow and deal pipeline?
The terms overlap. Deal flow usually refers to the incoming stream and its volume and quality. The pipeline is the set of stages and records a firm uses to track those companies from first look to close.
What software do VCs use to manage deal flow?
Most firms use a venture CRM or a shared database for pipeline stages and relationship history, plus company data platforms for market mapping and intake forms for inbound submissions. Small funds often start with a spreadsheet.
Related posts
How the risk factor summation method values a pre-revenue startup, how to score each of the 12 risks with evidence, a worked example with ownership and 10x checks, whether the $250,000 step still fits current seed prices, and how VC analysts use it in memos and interviews.
Growth equity buys minority stakes in proven, growing companies; venture capital backs startups still proving the market. Compare stage, risk, terms, secondaries, loss ratios, 2026 round sizes and careers.
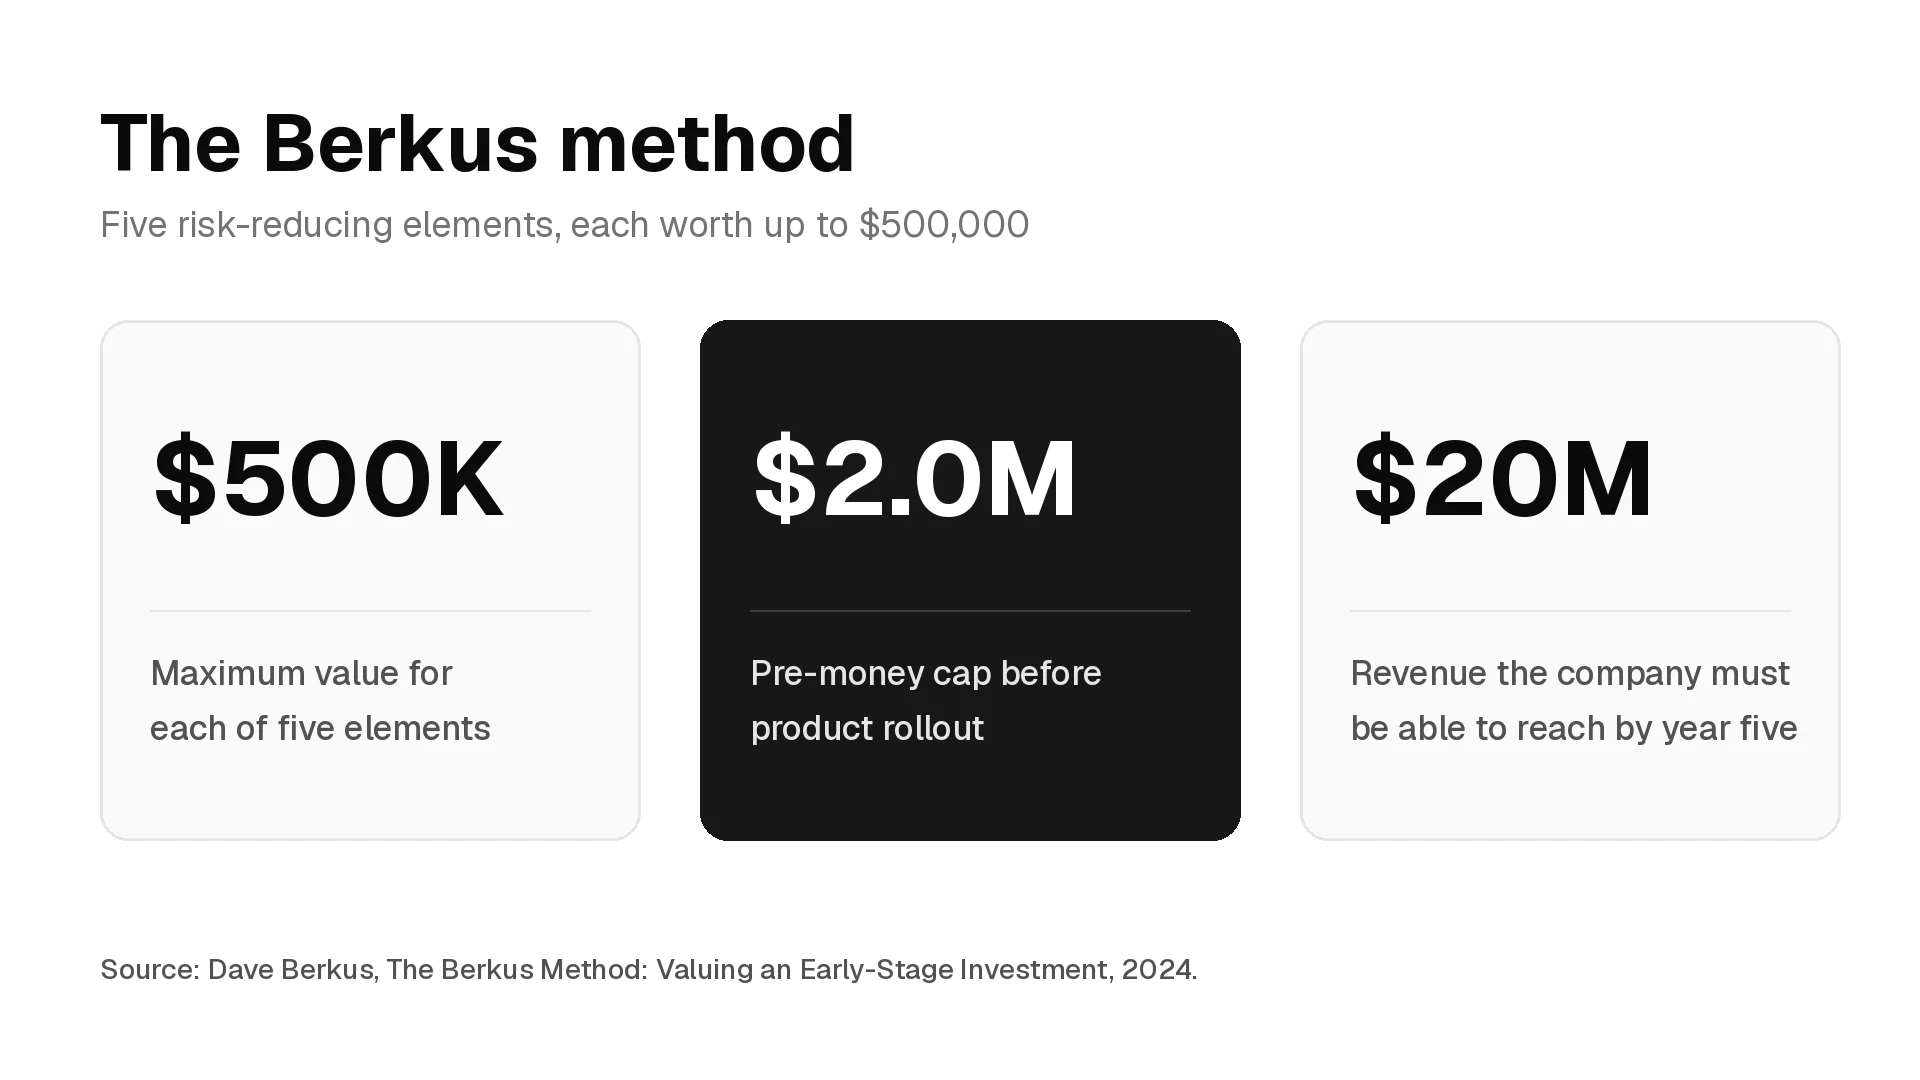
How the Berkus method values a pre-revenue startup, how to score each of the five elements, a worked example with ownership and 10x checks, how the $500,000 caps compare with current seed prices, and how VC analysts use it in memos and interviews.