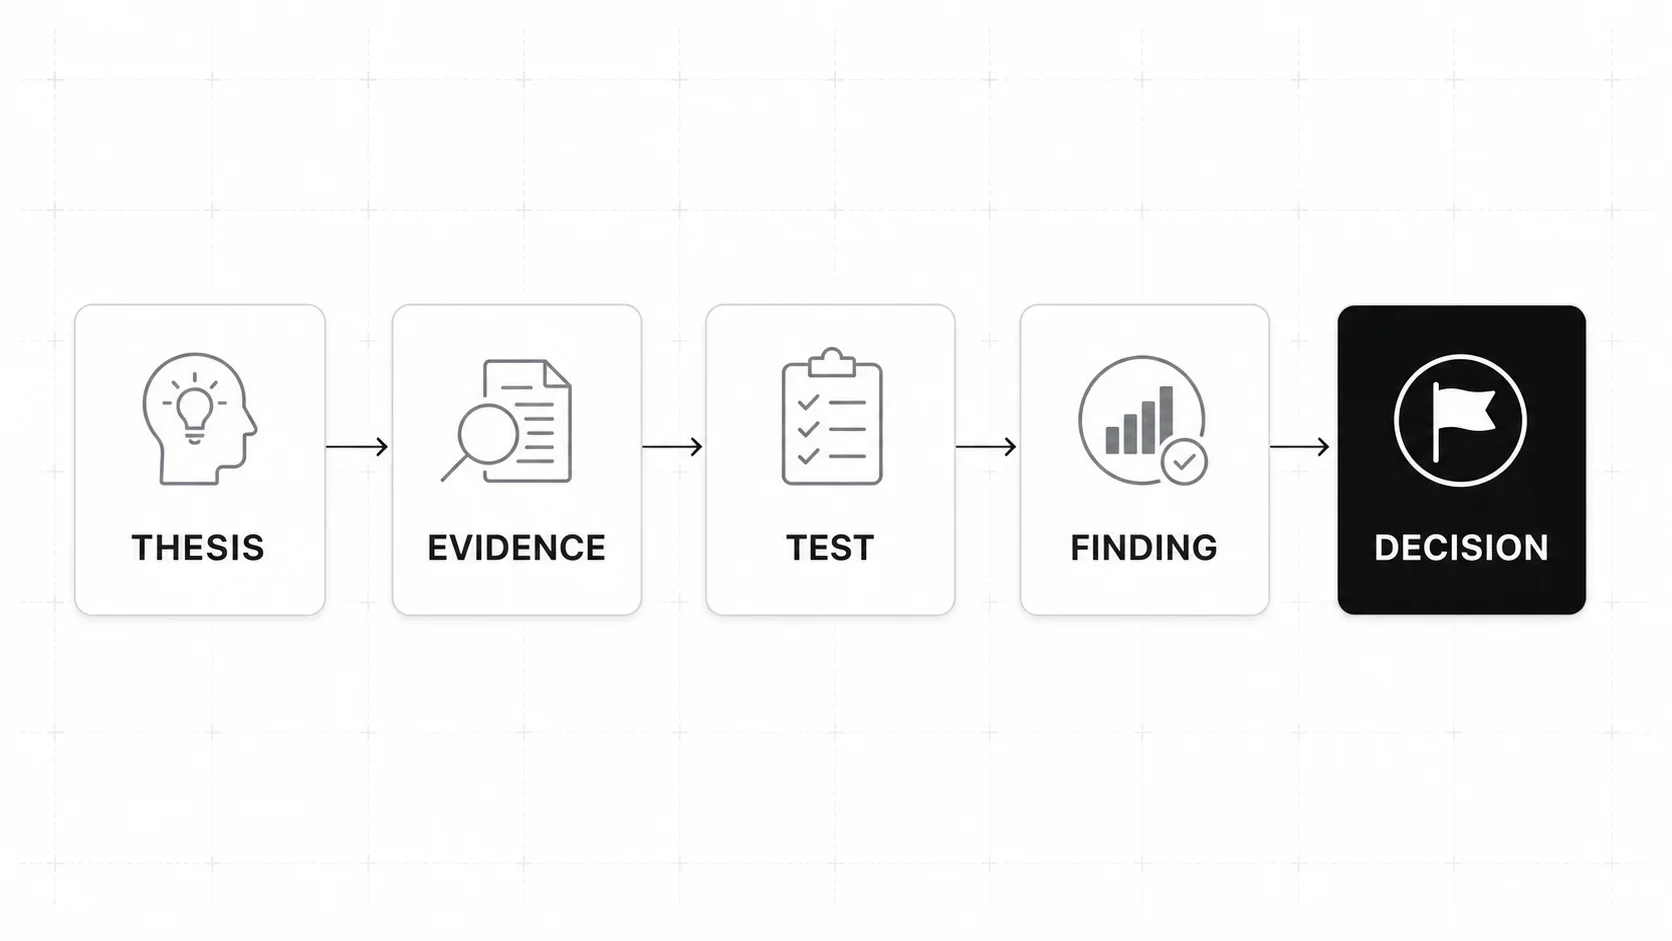
Venture capital due diligence is the investigation a VC firm runs after a startup passes initial screening and before it commits capital: the deal team tests the founders, market, product, customers, financials, and legal records against the investment thesis, then turns what it finds into a recommendation, deal terms, or a pass. In the largest survey of US venture investors, by Paul Gompers, Will Gornall, Steven Kaplan, and Ilya Strebulaev, the average deal took 83 days to close, the average firm spent 118 hours on due diligence over that period, and it called 10 references (NBER Working Paper 22587).
The output is not a folder of documents. It is a defensible investment decision, a record of what remains unknown, and a plan for the terms, closing conditions, and board monitoring that follow.
What venture capital due diligence is and is not
Screening asks whether a company deserves more time: stage, sector, check size, geography, ownership target, and conflicts. Diligence starts once a partner has a plausible investment thesis for the company. It verifies the upside case, looks for the facts that would break it, and decides which uncertainties the fund can accept.
Three features separate VC diligence from other kinds of investigation:
- It underwrites a future, not a history. A seed company cannot prove a market will form. Clean records matter, but the decisive questions are about founders, demand, and timing.
- It is sized to the outlier case. Most venture returns come from a few companies, so the question is whether this company could become one of them. A business that can only be a modest success often fails the power law test even when every document checks out.
- It is minority-position diligence. Unlike a buyout, a VC usually does not control the company after closing. Governance rights, information rights, dilution, and follow-on needs matter as much as enterprise value.
A working rule: do not request a document unless you know which claim it tests and which decision could change because of it.
Where due diligence sits in the VC deal funnel
Most firms run some version of the same sequence: source, screen, first meeting, partner review, due diligence, term sheet, confirmatory diligence, close. The survey data show how narrow the funnel is by the time diligence starts. For every deal a firm closes, it considers about 101 companies, meets 28 management teams, reviews 10 at a partner meeting, takes 4.8 into due diligence, and offers 1.7 term sheets (NBER 22587, Table 6). Roughly half of partner-reviewed companies proceed to diligence, and about a third of companies in diligence receive a term sheet.
Two consequences follow for anyone doing the work:
- Diligence is where most serious deals die. About two of every three companies a firm diligences do not get a term sheet. The job is to find the reason quickly, not to confirm enthusiasm.
- Sequencing varies. Some firms issue a term sheet before legal and financial confirmation; in hot markets, some issue preemptive term sheets before formal diligence. Confirmatory diligence after signing still covers corporate records, securities, IP, and material contracts.
The upstream stages, from sourcing volume to partner meetings, are covered in the deal flow breakdown; the partner-level judgment that sits on top of diligence is covered in how venture capitalists make investment decisions.
How long VC due diligence takes
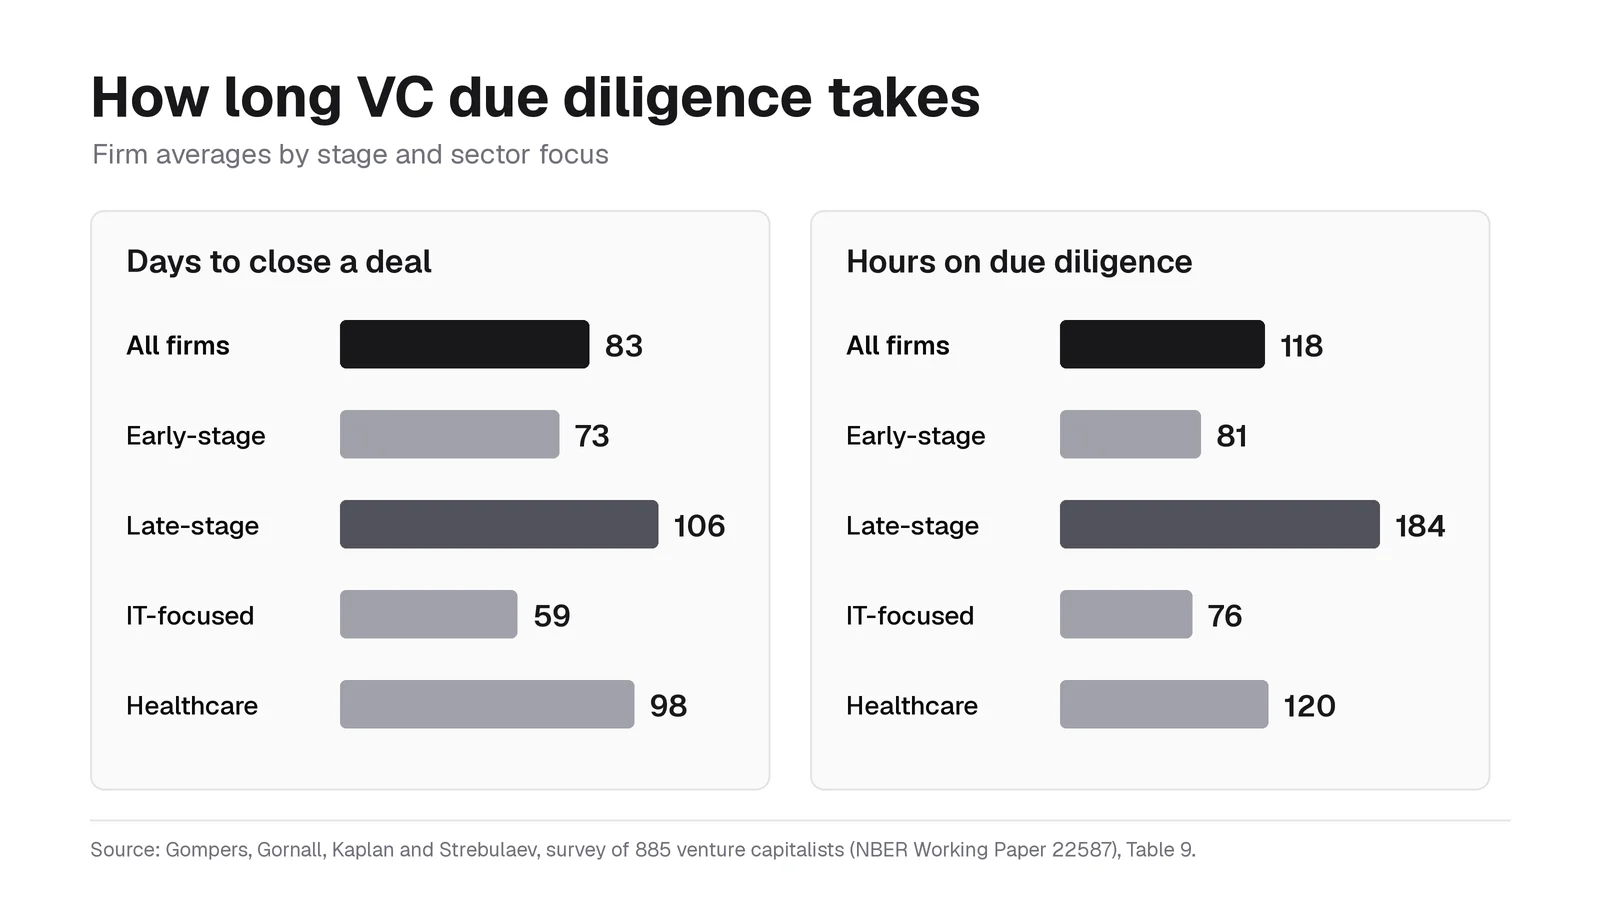
The same survey gives the most reliable benchmark for timing and effort. Averages hide large differences by stage and sector:
| Group | Days to close a deal | Hours on due diligence | References called |
|---|---|---|---|
| All firms | 83 | 118 | 10 |
| Early-stage firms | 73 | 81 | 8 |
| Late-stage firms | 106 | 184 | 13 |
| IT-focused firms | 59 | 76 | 10 |
| Healthcare-focused firms | 98 | 120 | 11 |
Source: Gompers, Gornall, Kaplan, and Strebulaev, NBER Working Paper 22587, Table 9 (survey of 885 venture capitalists at 681 firms; results averaged by firm).
How to read the numbers:
- Days to close covers the whole deal process, not only the diligence work. A focused seed process can move far faster than the average; a regulated healthcare or multi-jurisdiction growth round can take longer.
- Hours scale with evidence. Late-stage firms spend more than twice the hours of early-stage firms because there are more financial records, contracts, and cohorts to test.
- References are a core workstream, not a formality. Even early-stage firms average eight reference calls per deal.
When a competitive round compresses the calendar, the hours do not disappear. They move earlier, into thesis work and market mapping the firm does before a specific company appears.
The VC due diligence process in six steps
1. Write the investment hypothesis and kill criteria
State the thesis in falsifiable terms. "Large market and strong team" is too vague. A usable hypothesis reads: "Mid-market finance teams will adopt this product without services-heavy implementation, producing strong retention and a payback period the company can finance."
Then write the kill criteria: no evidence of repeat usage, a market too small for the fund's return target, unresolved IP ownership, a cap table that prevents the target ownership, or a regulatory dependency the company cannot meet.
2. Build the diligence plan and assign owners
Turn each thesis claim into a question, an evidence request, an owner, and a deadline. Put the questions most likely to change the decision first. Decide which workstreams can run in parallel and which depend on customer access, product data, counsel, or an outside expert.
3. Request evidence and grade its quality
System-generated or audited records beat a slide prepared for the round. A signed contract answers a different question from a pipeline spreadsheet. Customer calls test urgency and alternatives; product analytics test whether usage lasts.
Label each item as primary, corroborating, management-provided, or unverified. When two sources conflict, record the conflict instead of choosing the more attractive number.
4. Test the claims across workstreams
Triangulate. A product-market fit claim can be tested through cohort retention, usage depth, renewals, discounting, support load, and what customers used before. A market-size claim should connect identifiable buyers, budget, sales capacity, and realistic penetration, not a top-down industry total.
5. Keep an issue log and red-team the deal
Every material issue gets an owner, evidence, severity, next action, and resolution date. Ask someone outside the deal team to argue the strongest case against the investment. Red-teaming matters most when the process is fast, a well-known investor is leading, or partner conviction formed before the evidence arrived.
6. Convert findings into the memo, terms, and monitoring plan
The synthesis shows which claims held, which failed, and which remain open. Terms can allocate or limit some risks. They cannot repair weak demand, broken retention, or a team the firm does not trust.
Worked example: from claim to decision
| Step | Example |
|---|---|
| Founder claim | "Customers expand rapidly after the first deployment." |
| Evidence | Contract values, invoices, product usage, account-level revenue history, renewals, customer calls |
| Test | Build cohorts by start quarter; separate price increases, services, and acquired revenue from product expansion |
| Finding | Expansion is strong in enterprise accounts but flat in mid-market accounts, which are most of the pipeline |
| Implication | The go-to-market plan overstates near-term efficiency and may need a more expensive enterprise sales motion |
| Decision response | Revise the base case, re-test hiring and cash needs, adjust valuation or check size, monitor enterprise conversion |
Venture capital due diligence checklist
Organize the checklist by decision, not by folder. The table is the summary; the sections below give the questions that do the work in each area.
| Workstream | Decision question | Evidence to test | Red flags |
|---|---|---|---|
| Team and founders | Can this team recruit, learn, and execute through uncertainty? | Founder interviews, work history, references, hiring record, founder equity and vesting | Story changes between meetings, unexplained co-founder exits, weak ownership of critical functions |
| Market and competition | Is the obtainable market large, urgent, and open now? | Segmentation, market map, buyer interviews, win/loss data, regulatory or technology shifts | Top-down TAM with no buyer path, incumbent response ignored |
| Product, technology, and IP | Does the product solve the problem, and can it scale defensibly? | Demo, architecture review, usage, reliability, security practices, IP provenance | Demo differs from production, single-engineer dependency, unassigned IP |
| Customers and traction | Is demand repeatable and economically attractive? | Customer calls, contracts, pipeline, retention cohorts, pricing, discounts, sales cycle | Hand-picked references only, concentration, churn hidden by new sales |
| Financials and unit economics | Can the company finance the plan, and do economics improve with scale? | Statements, bank records, budget vs. actual, model, gross margin, CAC, payback, burn, runway | Numbers that do not reconcile, aggressive revenue recognition, cash need understated |
| Legal, cap table, and governance | Does the company own what it sells, and can the round close cleanly? | Formation records, board approvals, cap table, SAFEs and notes, option grants, IP assignments, material contracts | Undisclosed SAFEs or notes, missing approvals, undocumented equity promises, litigation |
| Operations, security, and regulation | Can the organization grow without unacceptable exposure? | Key vendors, insurance, data flows, access controls, incident history, licenses | Critical vendor dependency, weak data controls, missing licenses |
Team and founders
The team is the factor venture investors weigh most. In the NBER survey, 95% of firms named the management team as an important selection factor and 47% named it the most important, ahead of business model (83% important), product (74%), and market (68%) (NBER 22587, Table 7). Early-stage and IT investors were the most team-driven; late-stage and healthcare investors put more weight on the business.
Questions that separate a real assessment from a vibe check:
- Why is this team unusually well placed to win this market? That is the founder-market fit question, and it needs evidence from the founders' history, not only the pitch.
- Who owns product, sales, and engineering today, and who is missing for the next 18 months?
- How are founder equity, vesting, and roles documented, and has anyone left?
- What do backchannel references, not only founder-supplied ones, say about how the founders handle bad news, hiring, and conflict?
Watch for pattern matching standing in for evidence. A familiar résumé is a prior, not a finding.
Market and competition
Build the market from the bottom up: named customer segments, the budget the product replaces or creates, price, sales capacity, and realistic adoption. A venture capital market map helps separate direct competitors, substitutes, incumbents, and in-house builds. Ask why now: what changed in technology, regulation, or buyer behavior that makes this company possible today, and what happens if that change stalls.
Product, technology, and IP
Test whether the product solves an urgent problem and whether the advantage holds once competitors respond. Useful evidence includes production usage, not demo flows; architecture and security reviews for technical products; and the provenance of core code and inventions. Technical diligence is usually run by an expert adviser or an operating partner. Their job is to supply evidence, not to own the investment decision.
Customers and traction
Customer calls are the most direct test of demand. Ask for a mix of current, churned, and lost prospects, not only the founder's favorites. Cover the problem before the product, the alternative the customer used, the buying process, renewal intent, and what would make them switch. Then check the story against cohorts, contract terms, discounts, and the sales cycle.
Financials and unit economics
Reconcile management figures to bank records or system data where possible. Look at gross margin, contribution margin, CAC, payback, net revenue retention, burn, and runway by cohort, not only as blended averages. Tie the model to the hiring plan and pipeline: if the plan needs ten account executives, the model should show when they ramp and what happens if ramp time doubles. The financial due diligence explainer goes deeper on the accounting review.
Legal, cap table, and governance
Confirm the company exists, is in good standing, and owns its IP through founder, employee, and contractor assignments. Reconcile the cap table against every SAFE, note, option grant, and side promise, then recalculate ownership after the new round and the option pool. Review prior financing rights, material contracts, disputes, and regulatory permits. The NVCA model legal documents are the common reference set for US venture financings; transaction-specific review belongs to counsel.
Operations, security, and regulation
Check what could stop the company from operating as planned: critical vendors, data handling, security incidents, insurance, and licenses in regulated sectors such as fintech, health, and defense. Scale the depth to the exposure. A consumer app handling health data needs a different review from a developer tool.
How diligence changes by funding stage
The stage changes the available evidence and the burden of proof. Do not punish a seed company for lacking history, and do not let a growth company substitute narrative for data.
| Workstream | Pre-seed and seed | Series A | Growth stage |
|---|---|---|---|
| Team | Founder insight, commitment, complementary skills, ability to recruit | Leadership gaps, recruiting velocity, functional ownership, references | Executive depth, succession, controls, board effectiveness |
| Market | Problem urgency, credible customer set, bottom-up wedge, timing | Repeatable segment, competitive position, expansion path | Share, category durability, adjacent expansion, downside scenarios |
| Product | Prototype or MVP, user learning, technical feasibility | Engagement, retention, roadmap, scalability, security basics | Reliability, architecture, technical debt, compliance at scale |
| Commercial | Design partners, early willingness to pay, founder-led sales | Cohort retention, pricing, pipeline quality, repeatable motion, CAC and payback | Revenue quality, concentration, expansion, churn, forecast accuracy |
| Financial | Use of funds, burn, runway, basic model, clean accounting | GAAP-quality statements, budget vs. actual, unit economics | Controls, audit readiness, scenario sensitivity, margin durability |
| Legal and cap table | Formation, founder equity, SAFEs and notes, option grants, IP assignment | Material contracts, employment and invention agreements, financing history | Governance, litigation, multi-jurisdiction exposure, complex securities |
| Core question | Can this team discover and own a large opportunity? | Is there enough repeatability to finance scaling? | Is growth durable, governable, and worth the price? |
The survey numbers line up with the table. Early-stage firms average 81 diligence hours and 8 reference calls per deal; late-stage firms average 184 hours and 13 calls (NBER 22587, Table 9). Late-stage investors also rank valuation and business model higher, which is why growth diligence leans on financial and commercial evidence.
Two rules prevent false conclusions:
- Missing mature data at seed is not a red flag by itself. The question is whether the company has produced the evidence appropriate to its age and used it honestly.
- A large dataset at growth stage is not strong evidence by itself. Blended metrics can hide weak cohorts, discounting, concentration, or acquired growth.
Risks and red flags in VC due diligence
Most diligence findings map to a small set of risk types. Naming the type tells the team what evidence would resolve it and whether terms can help.
| Risk type | What it asks | Typical evidence | Can terms help? |
|---|---|---|---|
| Team and execution | Can these people build and sell this, at this pace? | References, hiring record, delivery against past plans | Rarely; vesting and board seats only at the margin |
| Market and timing | Will enough customers buy, soon enough? | Buyer interviews, budgets, adoption data, why-now evidence | No |
| Product and technical | Does it work, at scale, and is it defensible? | Usage data, architecture review, IP provenance | Partly; IP fixes as closing conditions |
| Financing | Can the company reach the next milestone on this capital? | Model, burn, runway, milestone plan | Partly; round size, tranches, pro rata |
| Legal and structural | Can the round close cleanly, with the ownership expected? | Cap table, contracts, approvals, disputes | Yes; conditions to close, reps and warranties |
| Regulatory | Can the company operate as planned under current and likely rules? | Licenses, counsel opinions, regulator history | Partly; conditions and covenants |
Red flags that usually trigger deeper work, re-pricing, or a pass:
- Founders whose numbers or story change between meetings, or who resist backchannel references.
- Revenue that does not reconcile to bank records, or spikes nobody can explain.
- One customer, channel, or partner carrying most of the revenue.
- Unassigned IP, especially code written before incorporation or by contractors.
- SAFEs, notes, or option promises that appear late or are missing from the cap table.
- Co-founder departures without a clear account.
- Litigation or regulatory issues disclosed only when asked directly.
A red flag is rarely an automatic pass. It is a prompt to dig, restructure, or re-price. An integrity problem is the exception: if trust cannot be restored, stop.
What founders should have ready for due diligence
Founders who prepare a clean data room shorten the process and avoid surprises that change terms. A typical early-stage request list covers:
| Area | Documents |
|---|---|
| Corporate | Certificate of incorporation, bylaws, board and stockholder consents, good-standing certificate |
| Cap table and financing | Fully diluted cap table, SAFEs and convertible notes, prior financing documents, option plan and grants, 409A valuations |
| IP and team | Founder, employee, and contractor IP assignment agreements, key employment agreements, org chart |
| Financial | Monthly financial statements, bank statements, budget vs. actual, operating model, tax filings |
| Commercial | Customer list with revenue, top contracts, pipeline, retention cohorts, pricing and discount history |
| Product and security | Product roadmap, architecture overview, security policies, incident history |
| Legal and regulatory | Material contracts, licenses and permits, litigation or disputes, insurance policies |
Two habits matter more than the folder structure: every number in the deck should reconcile to the data room, and known problems should arrive with a remediation plan before the investor finds them.
Turn findings into an investment decision
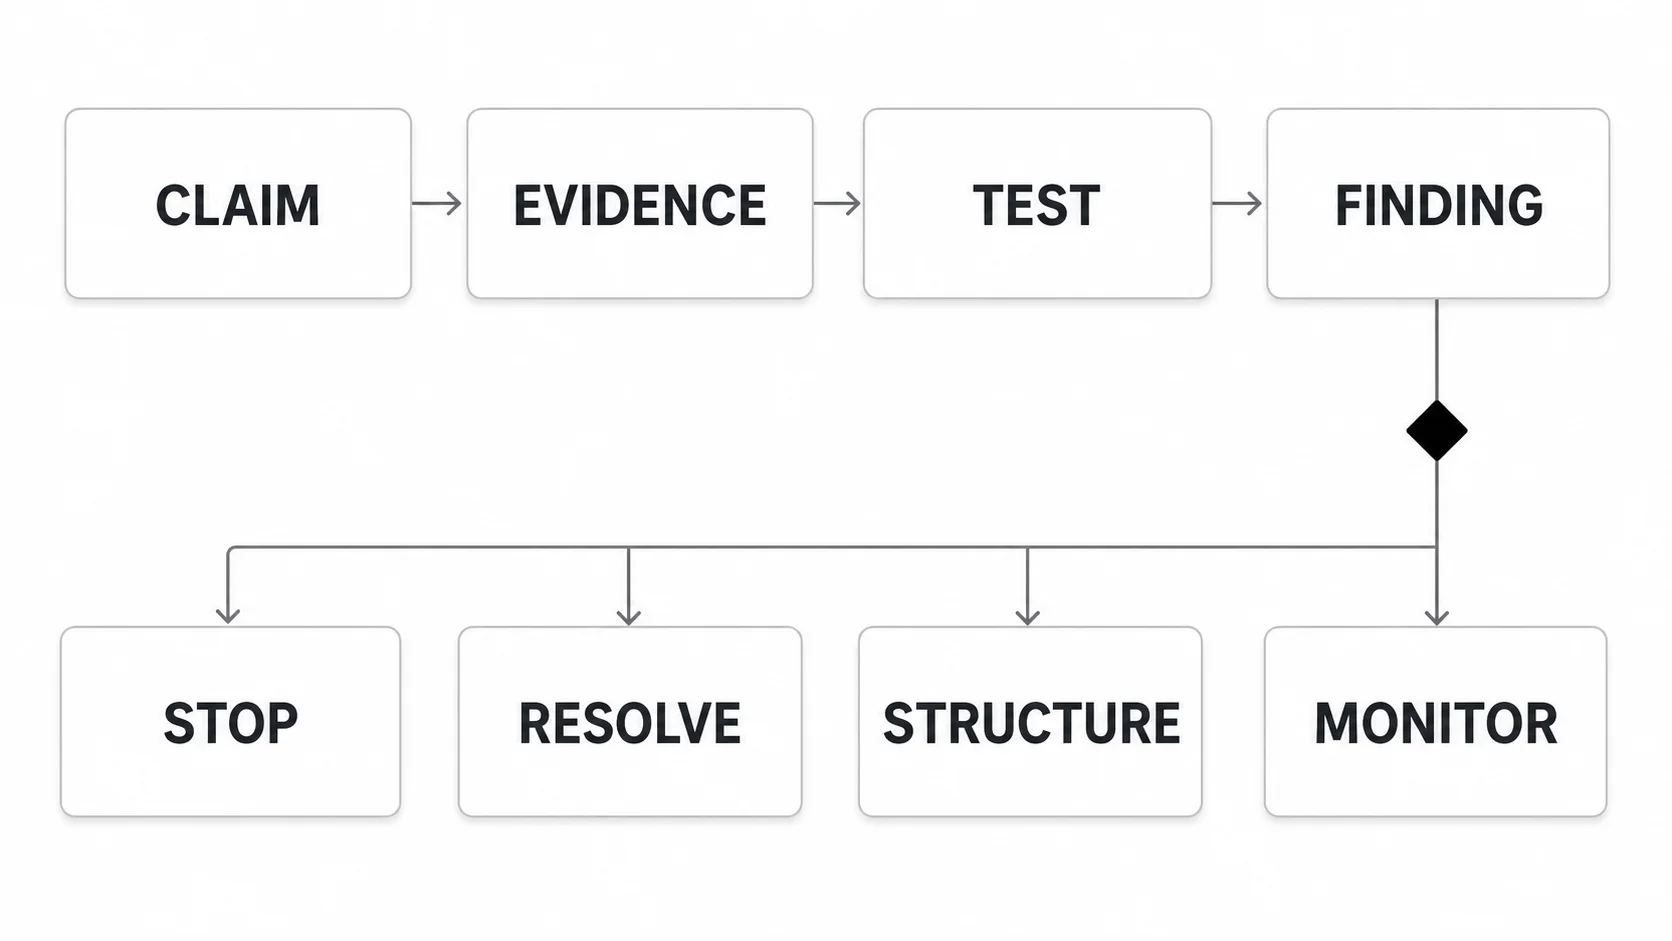
An issue log becomes useful when every material finding has a decision consequence:
- Stop: the core thesis is broken, trust is impaired, the company cannot lawfully operate as assumed, or the risk cannot be made acceptable.
- Resolve before close: a fix or verification is required before funds move, such as board approval, IP assignment, a corrected cap table, or a specialist opinion.
- Price or structure: the deal proceeds, but the finding changes valuation, check size, ownership, governance, protective terms, milestones, or the syndicate.
- Monitor: the uncertainty is acceptable today, but the board needs a metric, owner, threshold, and review cadence.
| Finding | Possible decision response |
|---|---|
| Market is attractive, but adoption is slower than the base case | Rebuild scenarios; reduce price or check; require more runway; monitor leading adoption indicators |
| Strong usage but weak gross margin because implementation is services-heavy | Reclassify the business model, test delivery capacity, revise margin and cash assumptions |
| Customer concentration is high but contracts and references are strong | Stress-test churn; size the round for concentration risk; track renewal and diversification milestones |
| Critical contractor has not assigned IP | Resolve with counsel before close; a representation alone is not a cure |
| Cap table contains unexpected SAFEs, notes, or option commitments | Reconcile fully; recalculate ownership and dilution; revise round economics |
| Founder reference pattern raises integrity concerns | Escalate and corroborate; if trust cannot be restored, stop |
The recommendation goes into a venture capital investment memo that separates facts, inferences, assumptions, and unknowns, then to the investment committee, which should be able to challenge the thesis without reopening every file in the data room. If the deal proceeds, findings shape the term sheet and any protective provisions. Terms can allocate governance and economic rights; they cannot create customer demand.
What analysts and associates do in VC due diligence
Partners own founder judgment and final conviction. Junior investors make the process legible and fast. Typical analyst and associate work products:
| Work product | What good looks like |
|---|---|
| Diligence plan | One page tying each thesis claim to a question, evidence request, owner, and date |
| Request list | Prioritized, sent once, tracked to completion |
| Market map | Direct competitors, substitutes, incumbents, and in-house builds, with why-now evidence |
| Customer and reference notes | Source, date, and contradictions recorded; backchannel calls flagged separately |
| Financial model | Transparent assumptions, cohort views, downside case tied to hiring and burn |
| Issue log | Facts, inferences, unknowns, severity, next action |
| Memo and IC deck | A recommendation, the strongest bear case, and what would reverse it |
With 4.8 companies entering diligence for every investment a firm closes (NBER 22587, Table 6), most diligence work ends in a pass. The skill that gets noticed is reaching a well-supported pass early, not producing the longest memo. Role scope varies by firm; the venture capital analyst job description and associate job description cover how responsibilities split.
How to approach a diligence case study
Interview case studies test the same skills. Start by naming the three to five questions that could change the decision. A seed software case might prioritize founder-market fit, urgent demand, repeat usage, distribution, and financing risk. A growth case might prioritize revenue quality, cohort durability, sales efficiency, concentration, and gross margin.
For each question, show what you know, what you infer, what remains unknown, which evidence you would request next, and what result would change your recommendation. Make the downside concrete: if the base case assumes faster sales hiring, show what happens when ramp time doubles.
Finish with invest, pass, or continue subject to named conditions, and state the strongest argument against your own conclusion. Practice with the venture capital case study interview framework, then browse open venture capital roles to put the work in front of a firm.
Common venture capital due diligence mistakes
Treating the data room as ground truth
The data room is a set of claims assembled for a transaction. Reconcile statements to bank or system records, compare pipeline claims with contracts and conversion history, and use customer calls to test the story behind the numbers.
Confusing market size with obtainable revenue
A large industry total does not establish a venture-scale opportunity. Connect segment, buyer, budget, sales motion, price, adoption, and competitive response to a bottom-up outcome.
Letting blended metrics hide the cohorts
Company-wide retention, CAC, or gross margin can improve while recent customers deteriorate. Segment by start period, customer type, product, channel, or geography when those cuts affect the thesis.
Calling only the founder's references
Founder-supplied references are selected to be positive. Backchannel calls with former colleagues, customers who churned, and prospects who chose a competitor carry more information per call.
Outsourcing judgment to experts or AI
Experts can challenge technical, market, legal, or regulatory assumptions. AI tools can speed document review and question generation. Neither should be the source of record or make the decision. Verify material claims against primary documents, system data, and accountable people.
Leaving cap table, IP, and compliance questions until the end
These issues change ownership, closing readiness, or the company's ability to operate. Surface them early enough for counsel to decide whether they can be fixed.
Writing an advocacy memo
A memo that sells the deal while burying unknowns defeats the purpose. The decision record should show the bear case, scenario sensitivity, and the facts that would reverse the recommendation.
Frequently asked questions
How long does venture capital due diligence take?
In the NBER survey of 885 venture capitalists at 681 firms, the average deal took 83 days to close, with 118 hours of due diligence. Early-stage firms averaged 73 days and 81 hours; late-stage firms averaged 106 days and 184 hours. Competitive seed rounds can close much faster; regulated or complex growth rounds can take longer.
Does due diligence happen before or after a term sheet?
Both. Many firms complete business diligence before issuing a term sheet and leave confirmatory legal, financial, and technical work for afterward. Some issue preemptive term sheets before formal diligence in competitive markets. The term sheet should state the conditions that remain open.
Who performs due diligence at a VC firm?
The deal team. Analysts and associates usually run research, models, reference calls, and the issue log; partners assess the founders and own the recommendation to the investment committee. Lawyers, accountants, technical advisers, and industry experts handle specialist workstreams.
What do VCs look for most in due diligence?
The management team. In the NBER survey, 47% of venture capitalists ranked the team as the single most important factor in investment decisions, ahead of business model, product, and market. Valuation was ranked most important by fewer than 3% of respondents overall.
How many references do VCs call?
The surveyed firms averaged 10 reference calls per deal: 8 for early-stage firms and 13 for late-stage firms. Strong processes mix founder-supplied references with backchannel calls and customer calls.
How is VC due diligence different from private equity due diligence?
Private equity buyers usually take control of mature companies and focus on historical cash flow, debt capacity, and operational improvements, with deep legal and accounting review. VC investors usually take minority stakes in young companies and focus on founders, market potential, and evidence of demand. See private equity vs. venture capital for how the jobs differ.
What should founders prepare for VC due diligence?
A clean fully diluted cap table, financing documents, corporate records, IP assignments, monthly financials and bank statements, a model, customer and retention data, key contracts, and security and regulatory materials. Make every deck number reconcilable and disclose known problems with a plan.
Related posts
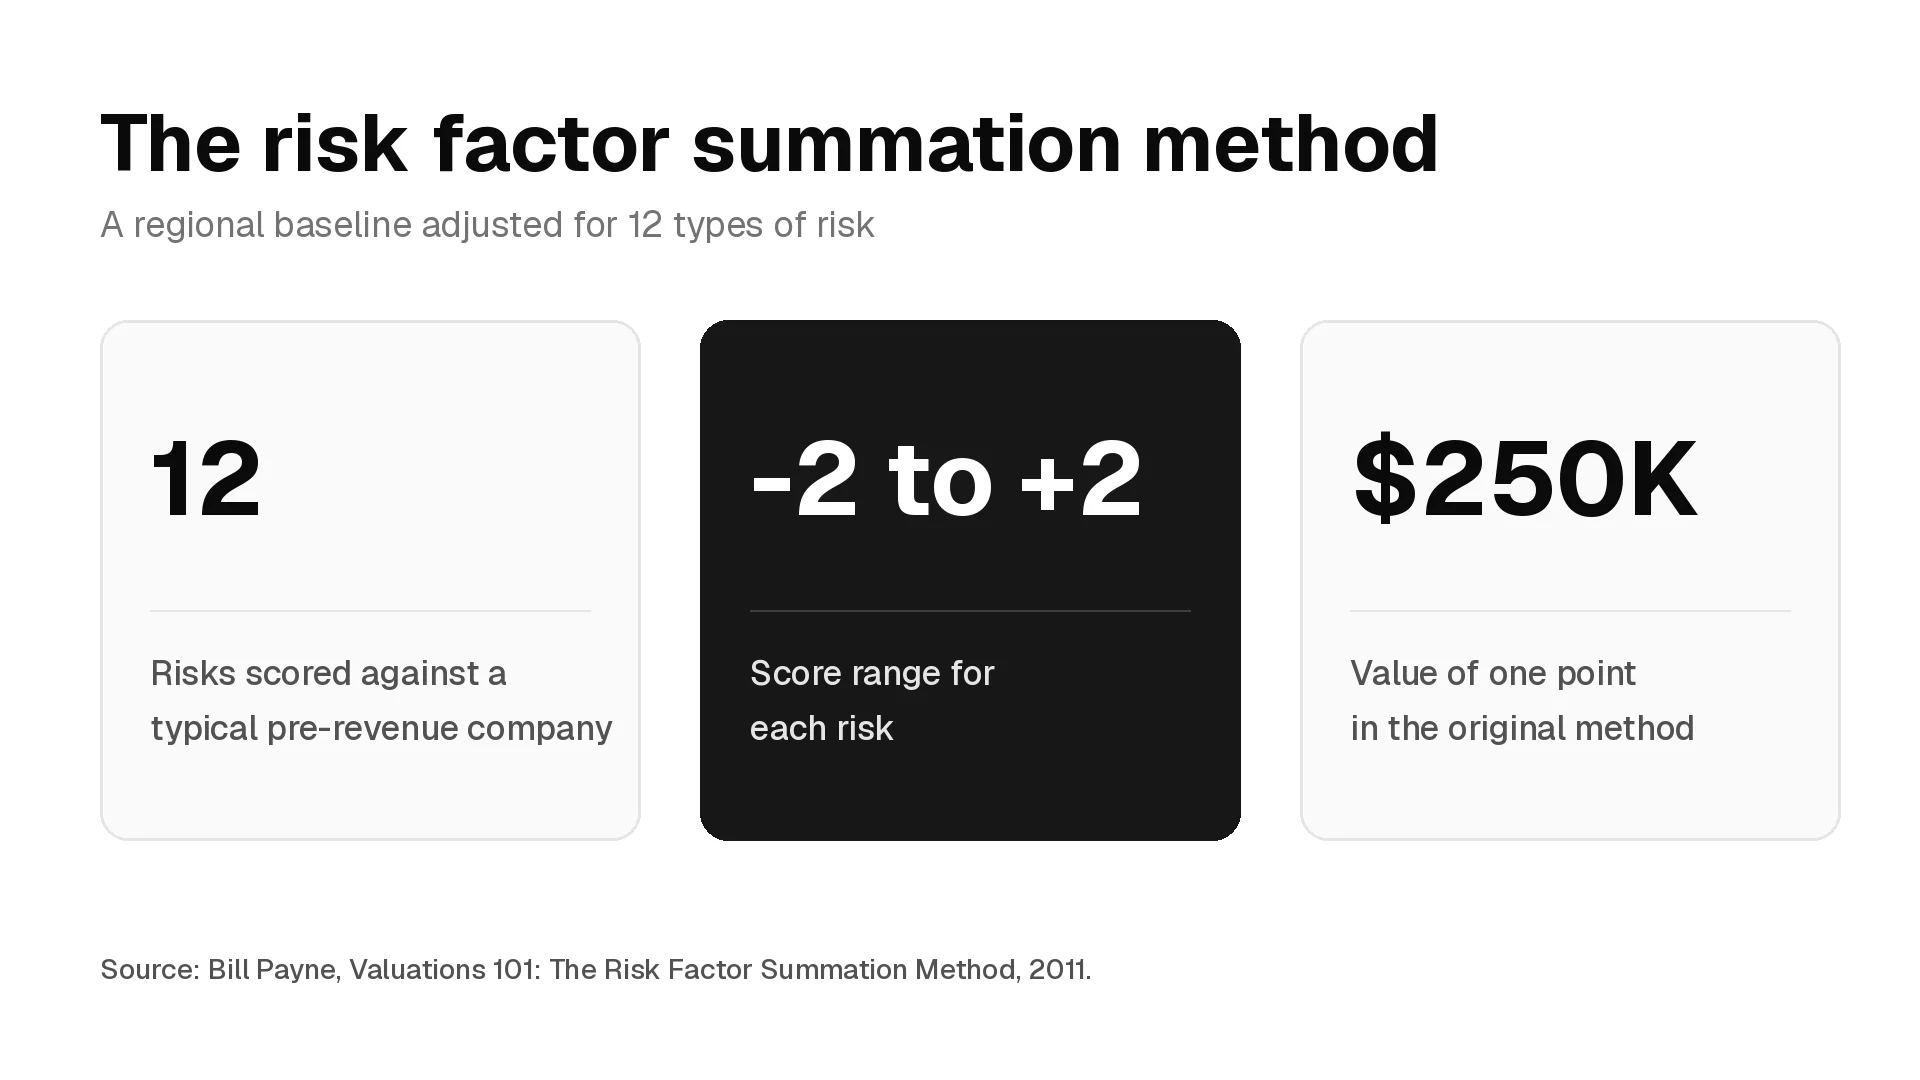
How the risk factor summation method values a pre-revenue startup, how to score each of the 12 risks with evidence, a worked example with ownership and 10x checks, whether the $250,000 step still fits current seed prices, and how VC analysts use it in memos and interviews.
Growth equity buys minority stakes in proven, growing companies; venture capital backs startups still proving the market. Compare stage, risk, terms, secondaries, loss ratios, 2026 round sizes and careers.
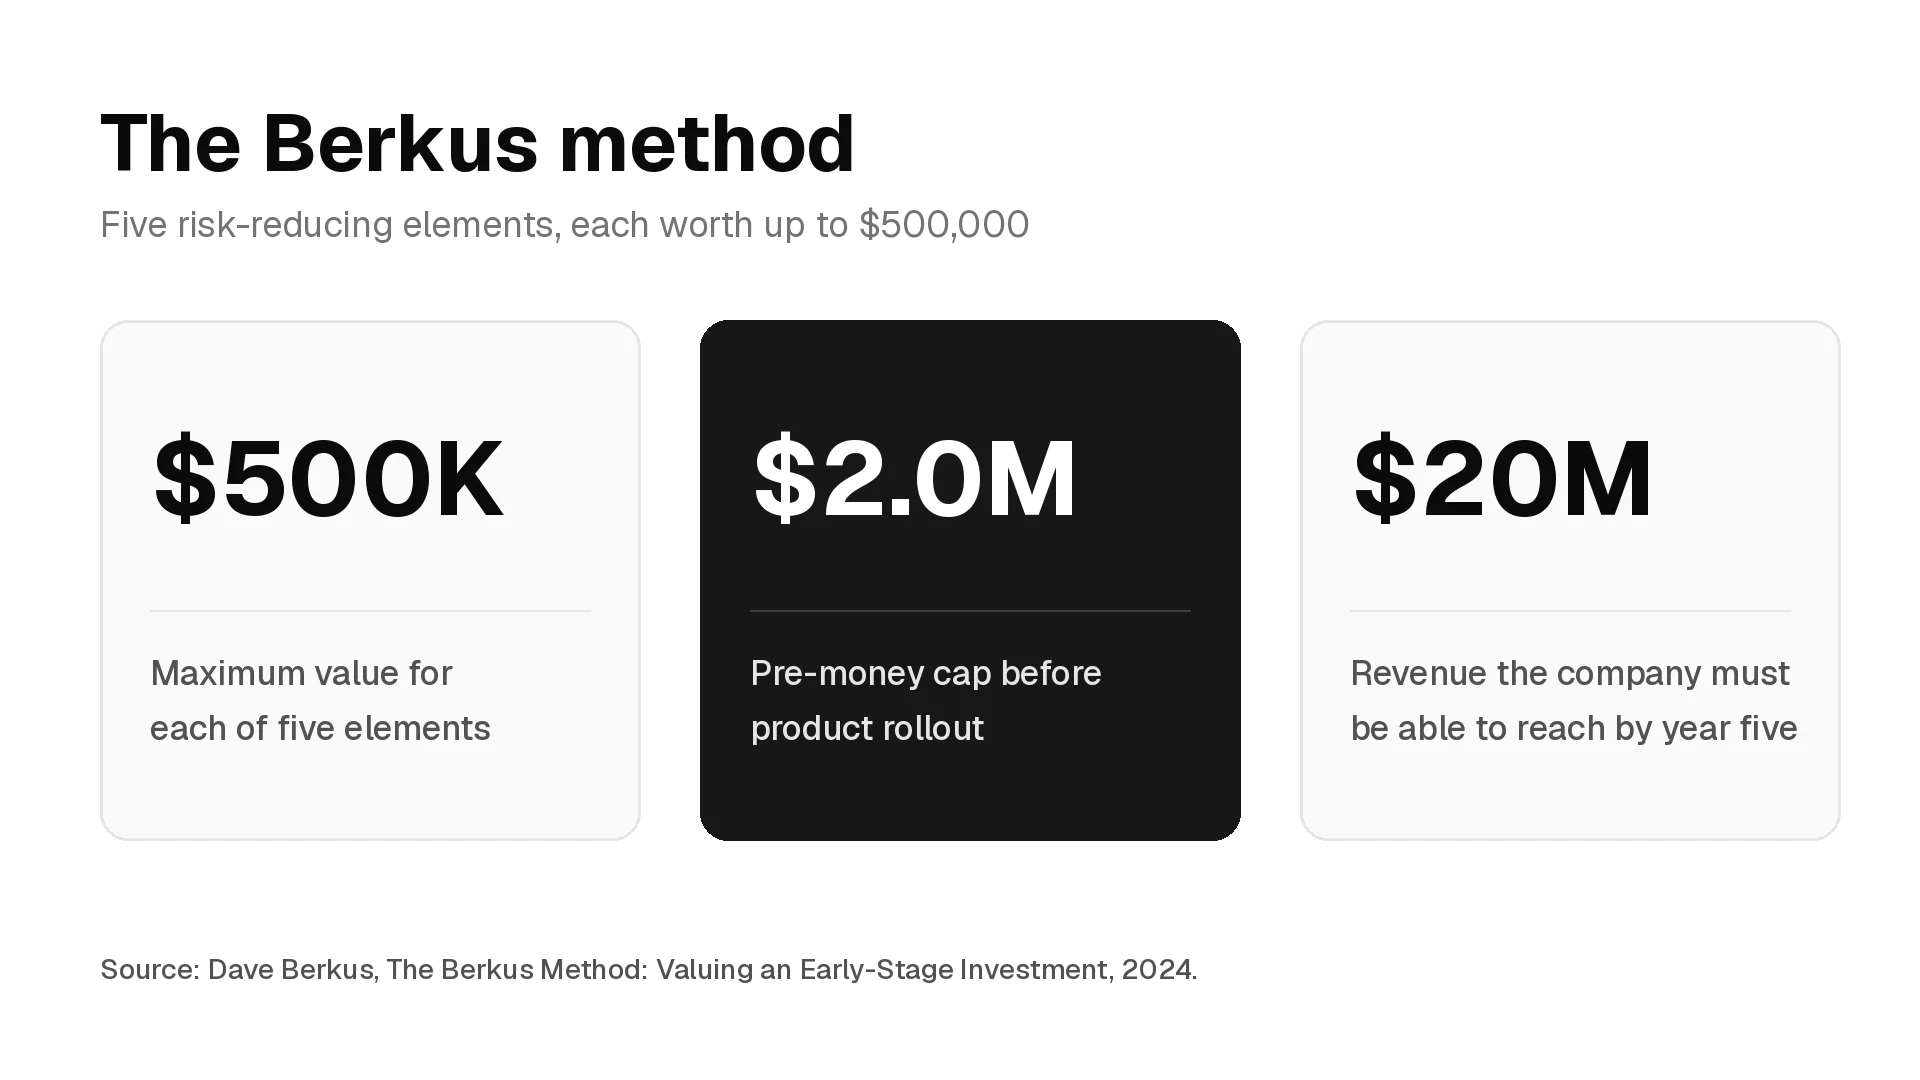
How the Berkus method values a pre-revenue startup, how to score each of the five elements, a worked example with ownership and 10x checks, how the $500,000 caps compare with current seed prices, and how VC analysts use it in memos and interviews.