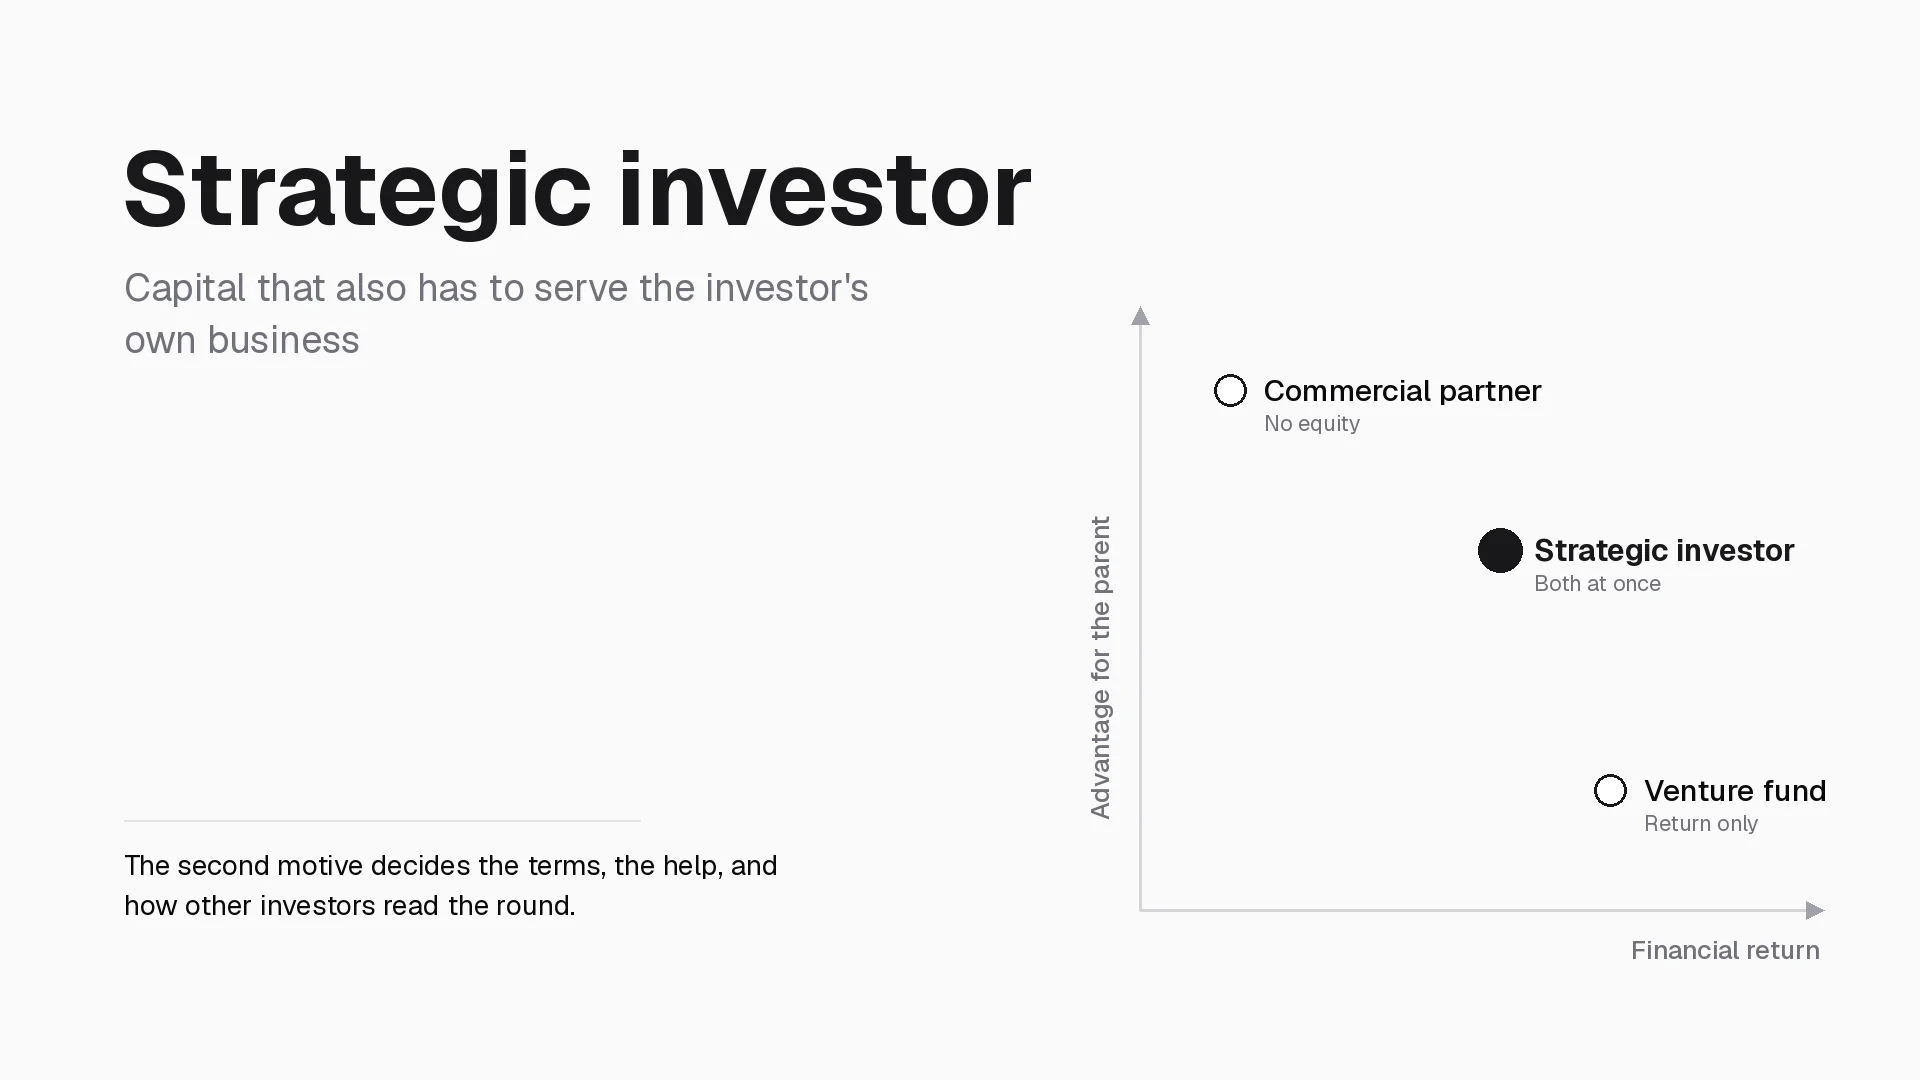
A strategic investor is a company, or an investment arm of one, that buys a minority stake in a startup for two reasons at once. It wants a financial return, and it wants an advantage for its own business, such as a new customer, a sales channel, a technology, a supply line, or a head start on a future acquisition.
That second motive separates strategic money from a venture fund's money. A venture fund asks whether the company can become worth far more than the price paid. A strategic investor asks that too, and then asks what the company can do for its own business. The answer to the second question shapes what the investor asks for in the term sheet, how it behaves on the cap table, and how other investors read its presence.
Strategic capital is common and getting more concentrated. Corporate investors took part in 20.7% of US venture deals in the first nine months of 2026, and those deals held 80.1% of all US venture deal value, according to the Q3 2026 PitchBook-NVCA Venture Monitor.
What is a strategic investor?
A strategic investor is an operating business that invests in another company because that company can strengthen its own strategy, while still expecting the stake to be worth more later. In startup financing the term almost always means a corporation, a corporate venture capital (CVC) unit, or a corporate development team buying preferred stock, a SAFE, or a convertible note.
The money usually arrives in one of three ways:
- Through a dedicated corporate venture capital fund or team, such as Salesforce Ventures or Intel Capital.
- Directly from the corporate balance sheet, approved by a business unit or the finance team.
- Through corporate development, as a minority stake that sits next to a partnership or a possible acquisition.
Three other uses of the phrase cause confusion:
- In M&A, a "strategic buyer" is an operating company that acquires a business, as opposed to a private equity "financial buyer." A strategic investor in a startup round is often the same company at an earlier stage of the relationship.
- "Strategic investment" in corporate finance means any minority stake or partnership investment a company makes for business reasons, not only into startups.
- In personal finance, "strategic investing" describes a long-term, planned approach to a portfolio. It has nothing to do with startup rounds.
Strategic investor vs financial investor
A financial investor, such as a venture fund, angel, or growth equity firm, is paid only by the value of its shares. A strategic investor is paid by the shares and by whatever the relationship does for its core business. Almost every practical difference follows from that.
| Strategic investor | Financial investor (VC fund, angel, growth fund) | |
|---|---|---|
| What it underwrites | Return plus a business outcome for the parent | Return on the shares |
| Source of capital | Corporate balance sheet or a CVC fund, often with one corporate LP | Third-party LPs in a time-limited fund, or personal capital |
| Time horizon | Tied to corporate strategy and budget cycles | Tied to the fund's life, usually around ten years |
| Help it can offer | Customers, distribution, technical depth, regulatory know-how, acquisition path | Fundraising, hiring, board judgment, follow-on capital, investor network |
| Typical extra asks | Commercial agreement, information access, observer seat, rights around a sale | Board seat, protective provisions, pro rata rights |
| Biggest risk to the founder | Conflicts with the parent's interests and signaling to the parent's competitors | Pressure for outsized growth and an exit on the fund's timeline |
Financial investors are the better fit when the company needs neutral capital, wants to sell to everyone in its market, or expects to run a competitive sale process later. A strategic investor fits when one company controls something the startup needs, such as a channel, a certification, an installed base, or supply, and the commercial relationship would make sense even without the equity.
Companies that take strategic money usually also have financial investors. A familiar pattern is a VC lead investor who sets the price and terms, with the strategic joining as a participant.
Types of strategic investors
Strategic investors differ most in how close the investing team sits to the parent's operating business. The closer the team, the more useful the help can be, and the more the parent's interests show up in the terms.
| Type | Main motive | What it usually asks for | What to check |
|---|---|---|---|
| Independent-style CVC fund | Financial return with ecosystem insight | Standard VC terms, sometimes an observer seat | Whether it can invest without business-unit sign-off |
| Business-unit or balance-sheet investor | A product, channel, or technology the unit needs | Commercial agreement, roadmap visibility, observer seat | Who the internal sponsor is and what the unit has committed |
| Customer-investor | Securing a supplier or shaping a product it buys | Pricing, priority access, product commitments | Revenue concentration and whether its rivals will still buy |
| Supplier or supply-chain investor | Locking in demand for its inputs | Volume or sourcing commitments | Whether the commitment limits switching later |
| Platform or ecosystem investor | More usage of its platform, cloud, marketplace, or chips | Integration, co-marketing, credits tied to usage | Dependence on one platform |
| Corporate development | A relationship with a likely acquisition target | Notice or matching rights on a sale, deep information access | Whether rights chill other bidders |
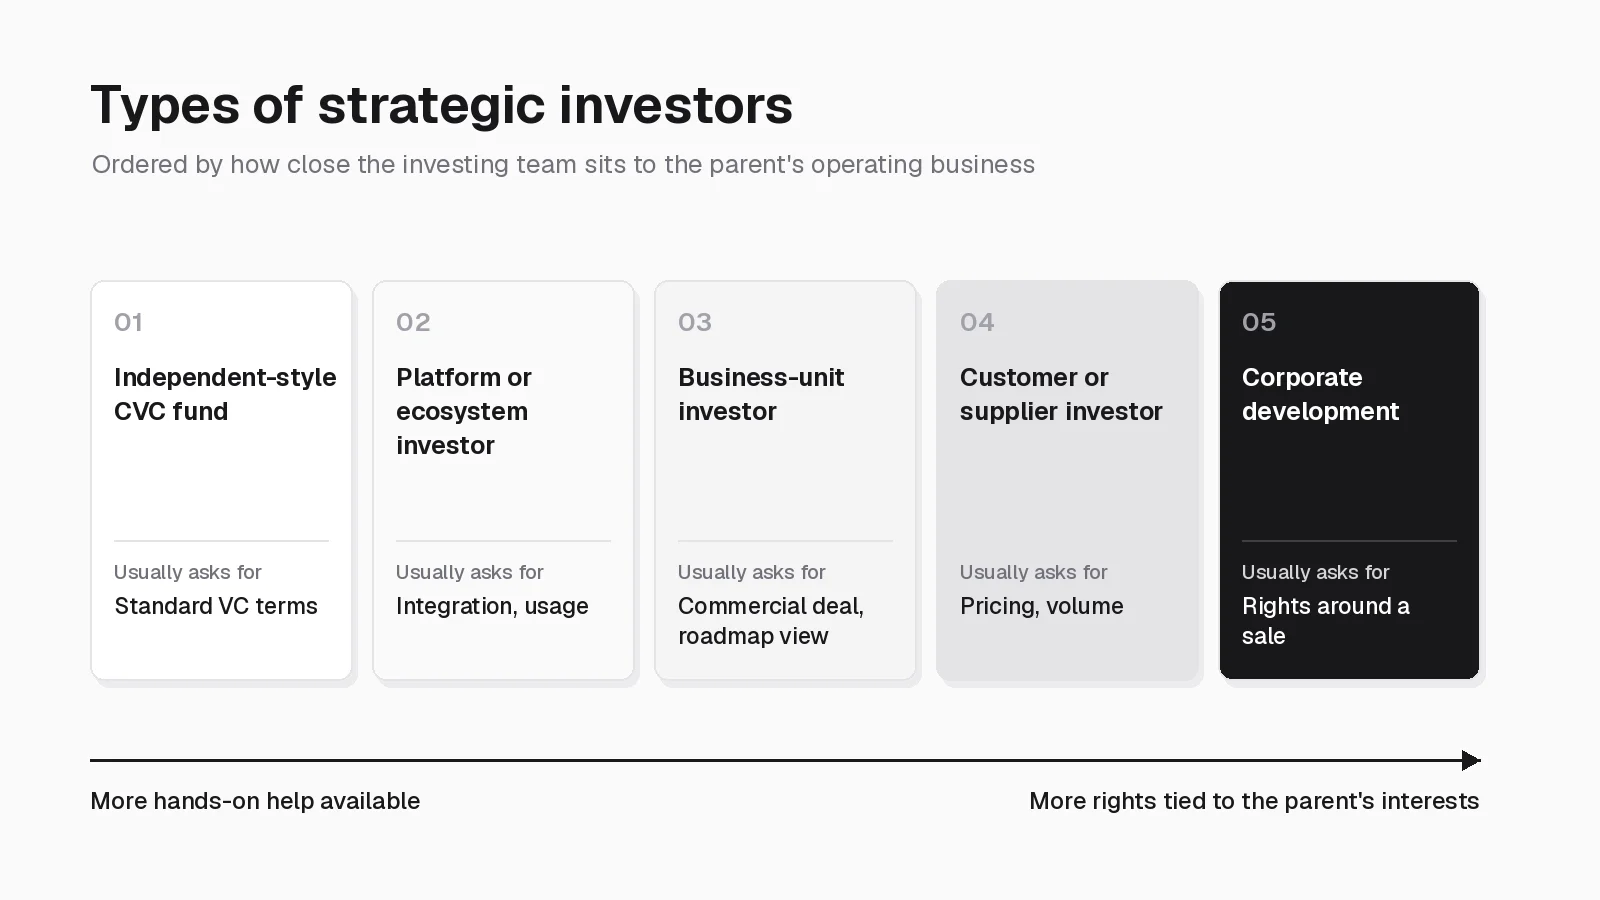
The categories overlap. A cloud provider's venture arm can act like an independent fund in one deal and like a platform investor in the next, depending on how much the parent cares about the outcome.
How a strategic investment is structured
The equity a strategic investor buys usually looks the same as everyone else's in the round. The difference sits in the documents attached to it.
As a participant in a priced round
The cleanest structure is a priced preferred-stock round with a venture firm leading. The strategic signs the same stock purchase agreement, investors' rights agreement, and voting agreement as the other investors. Its special asks, if any, go into a side letter or a separate commercial contract. This is the structure financial investors prefer, because the lead negotiates price and governance and the strategic cannot set terms on its own. The term sheet shows who holds that pen.
Through a SAFE or convertible note
At pre-seed and seed, a strategic may buy a SAFE or a convertible note. These instruments carry few governance rights, so any special treatment lives in a side letter. Read that side letter as closely as a term sheet. Information or sale-related rights granted early can follow the company into every later round.
Paired with a commercial agreement
Many strategic investments come with a customer, reseller, supply, or integration contract signed at the same time. The commercial agreement often matters more than the equity, because exclusivity, pricing, and termination terms sit there. Negotiate it as a separate contract that would stand on its own if the investment fell away.
Balance sheet vs dedicated fund
A dedicated CVC fund usually has a set investment process, its own reserves for follow-on rounds, and a team measured partly on financial return. A balance-sheet investment depends on a business unit's budget and sponsor. Ask which one is writing the check, because that decides who approves the next round and what happens if the sponsor leaves.
How common strategic investors are in 2026
Corporate investors appear in roughly one in five US venture deals, but those deals now hold most of the money. The Q3 2026 PitchBook-NVCA Venture Monitor counts both established CVC arms and direct corporate equity investments in its figures.
| Deals with corporate participation | 2025 (full year) | 2026 (through Sept. 30) |
|---|---|---|
| Deal count | 2,597 | 1,683 |
| Deal value | $192.5B | $397.6B |
| Share of all US VC deal count | 21.0% | 20.7% |
| Share of all US VC deal value | 65.6% | 80.1% |
Source: Q3 2026 PitchBook-NVCA Venture Monitor, data as of September 30, 2026.
Two readings follow from the numbers. First, the value share comes from large AI rounds in which hyperscalers and other corporates wrote the biggest checks, so the 80.1% figure says little about a typical seed or Series A. Second, the deal-count share has held near one in five while the number of corporate-backed deals fell from 4,271 in 2021 to 2,597 in 2025. The same report notes several high-profile closures of corporate venture programs in 2026 and a broad slowdown in deployment among those still active.
For a founder, that makes durability a diligence question. A strategic investor whose parent cuts its venture budget may still hold its shares and its rights, but it may not fund its pro rata in the next round or deliver the help it promised.
What founders gain from a strategic investor
The best strategic investors remove a specific bottleneck that money alone cannot remove. The value is real when it can be named and dated.
Customers and distribution
A strategic can become an anchor customer, open its sales channel, or list the product in its marketplace. This works best when the startup already sells to that buyer type and the investor speeds up a motion that exists.
Technical and regulatory depth
Corporates know their industry's procurement rules, security reviews, certifications, manufacturing constraints, and regulators. For a startup selling into banks, hospitals, utilities, or carmakers, that knowledge can save quarters of trial and error.
Credibility
A recognized industry name on the cap table helps in enterprise sales and recruiting. It helps less with later venture investors, who care more about whether the commercial relationship produces revenue.
A relationship with a likely acquirer
A strategic investor learns the company before any sale process. That can shorten diligence if the parent later wants to buy. It can also cut the other way, as the next section explains.
Risks and how strategic deals go wrong
Strategic deals go wrong in two ways. The relationship the check was supposed to buy never shows up, or the investor's rights narrow the company's options.
Signaling to the parent's competitors
If a large company in your market invests, its rivals may stop buying from you, partnering with you, or considering you as an acquisition. Test this before signing by asking two or three of the investor's competitors, who are also your prospects, how they would read the investment.
Information leakage
A strategic that competes with you, or could, may receive board materials, metrics, and roadmap detail. Even with confidentiality terms, people inside the parent learn what you are building. Limit what flows to the investor, not only what it may disclose.
No internal sponsor
The venture team closes the investment, but the business unit that was supposed to buy, integrate, or distribute never commits. Without a named executive sponsor and dated commitments, the investment is ordinary capital with extra complexity.
Rights that block an exit
A right of first refusal on a sale of the company, or a long notice period before the company can talk to buyers, tells every other acquirer that the strategic can match or delay its offer. Few bidders will spend months on a deal someone else can take.
Terms to negotiate with a strategic investor
Most of the risk in strategic money sits in a handful of rights. Each has a narrower version that gives the investor what it needs without blocking the company's other options. Review the final language with counsel; the middle grounds below are starting points, not legal advice.
| Term | What a strategic may ask for | Why it matters | Common middle ground |
|---|---|---|---|
| Rights around a sale of the company | Right of first refusal, right of first offer, or first look before the company talks to buyers | Chills other bidders and lowers the sale price | Short notice of a sale process only, with no right to match, or no sale right at all |
| Exclusivity | Exclusive supply, distribution, or integration in a market | Can shut the company out of its largest customers | Narrow by product, region, and term; tie it to volume the strategic actually delivers |
| Information rights | Full financials, customer data, roadmap | Leaks competitive information to a possible rival | Standard financial reporting only, with a Competitor carve-out |
| Board observer seat | Attendance at all board meetings and all board materials | Puts a parent employee in sensitive discussions | Observer subject to exclusion for conflicts, trade secrets, and competitive harm |
| Commercial agreement | Pricing, most-favored terms, product commitments | Often more binding than the equity | Arm's-length terms that would make sense without the investment |
| Consent or veto rights | Approval over sales, licensing, or new investors | Gives the parent a lever over strategy | Keep to the round's standard protective provisions; no strategic-only vetoes |
| Pro rata and new-security rights | Right to buy into future rounds | Usually harmless and useful | Grant on the same terms as other major investors; see pro rata rights |
The National Venture Capital Association's model Investors' Rights Agreement already gives founders a starting point for the information problem. The October 2025 version defines a "Competitor" as anyone engaged in a described line of business, excluding financial investment firms that hold less than 20% of a competitor and have no right to name a board member. Optional bracketed language then lets the company withhold financial statements and inspection rights from a Major Investor that is a Competitor, and exclude an observer from meetings or materials that would create competitive harm or a conflict of interest (NVCA model legal documents).
With a strategic investor in the round, the negotiation is often about whether that investor is named a Competitor, or carved out by name, and how broadly the business description is drafted. Extra rights for a single investor commonly sit in a side letter, so read the side letters as carefully as the main documents. Share-transfer rights such as the company's right of first refusal on stock sales are a separate issue from a strategic's rights around selling the whole company.
How to approach a strategic investor
A strategic investor says yes when a business unit wants the startup's product and the venture team can justify the stake. Approach both, in that order.
- Start from the commercial relationship. Identify the business unit that would buy, distribute, or integrate the product. A pilot, partnership, or customer contract in progress is the strongest opening.
- Find the internal sponsor. Ask who in the operating business will own the relationship after the investment. If no executive outside the venture team can be named, treat the conversation as a financing with an ordinary investor.
- Learn how the investing team decides. Ask whether investments come from a fund or the balance sheet, who sits on the investment committee, whether a business unit must sign off, and how long approval takes. Corporate approvals can run longer than a VC partnership vote.
- Sequence it with the lead. Bring the strategic in once a financial lead has set or is setting the terms, or agree up front that it will follow the lead's terms. A strategic that leads alone can set a price and rights that later investors then have to unwind.
- Separate the commercial terms from the equity. Negotiate the customer or partnership contract on its own merits and keep exclusivity out of the stock documents.
- Diligence the investor. Ask founders in its portfolio how the parent behaved when they sold to its competitors, raised a down round, or ran a sale process, and whether it funded its pro rata.
- Write down the help. Put the introductions, pilots, technical reviews, or co-marketing the strategic will deliver in the first 90 days into an email or a commercial schedule that both sides can check later.
To build a target list, start with companies that already buy from you or sell to your customers, then check which of them run a venture arm. The Venture Capital Careers companies directory lists venture firms and corporate venture groups with their profiles.
How VC firms read a strategic investor on the cap table
A financial lead does not object to strategic money by default. It objects to strategic rights that reduce the value of its own shares. When a corporate joins a round, or already sits on the cap table, the deal team works through a short list of questions, and the answers show up in the investment memo.
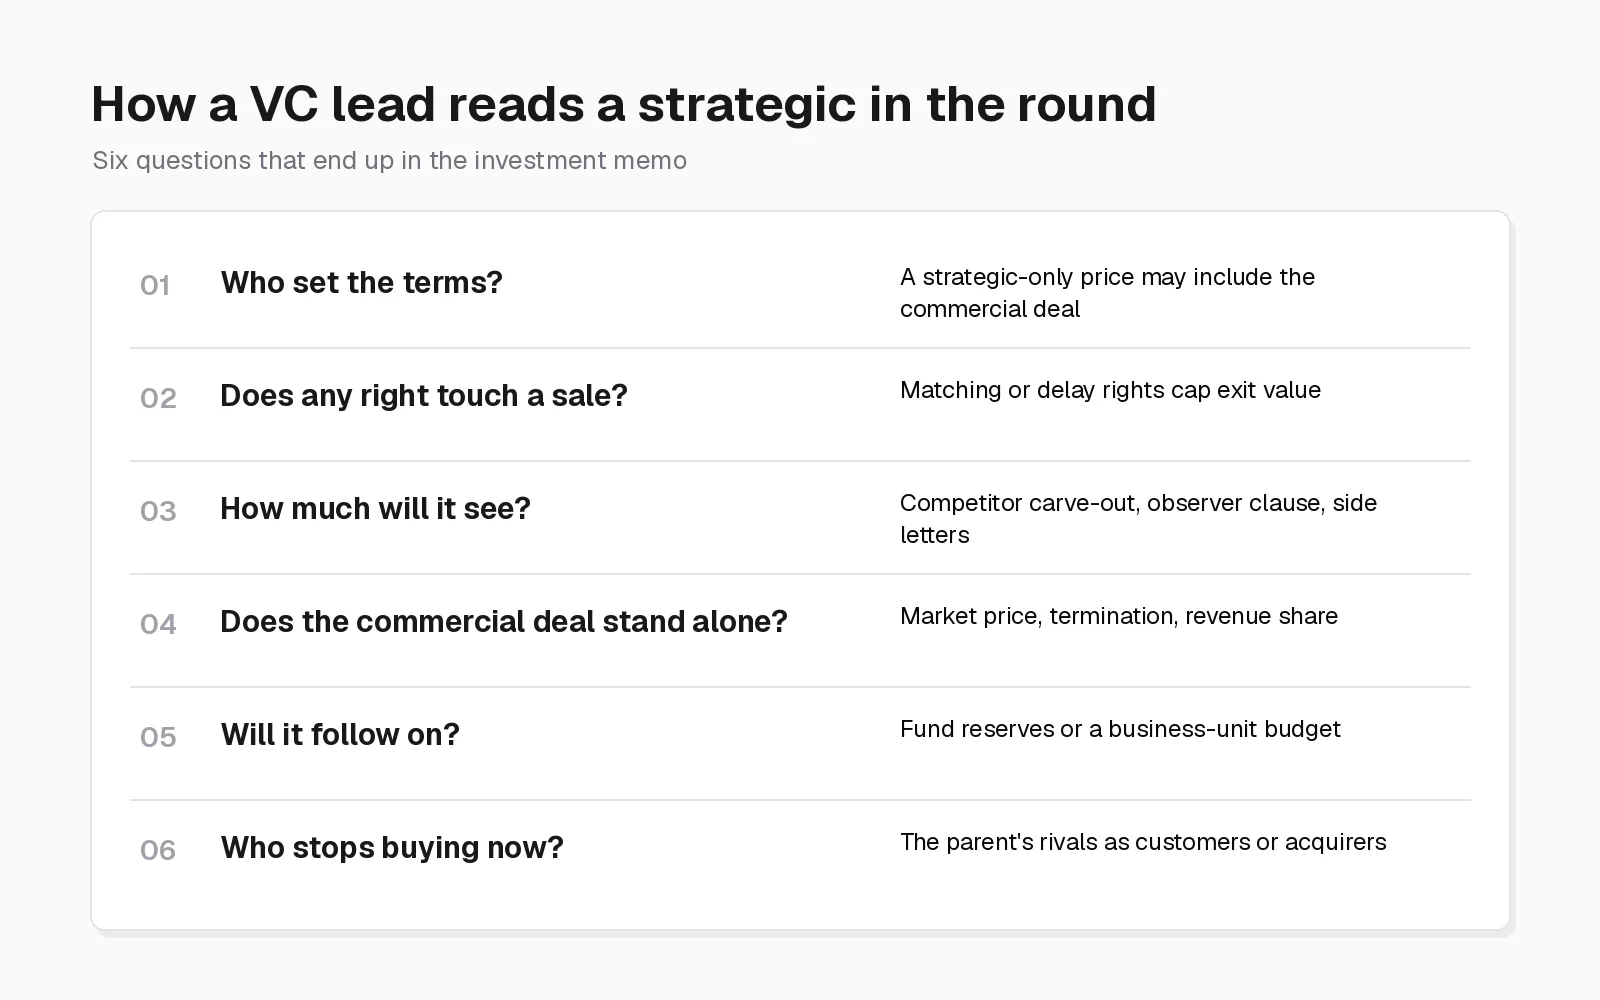
- Who set the terms? A round priced by a financial lead reads as a market price. A round priced by a strategic alone can read as a price paid partly for the commercial relationship, so the next investor may discount it.
- Does any right touch a sale of the company? Any right to match, delay, or receive early notice of an acquisition offer gets flagged, because it can cap the exit value the fund's model depends on.
- How much will the strategic see? The lead checks the investors' rights agreement for a Competitor definition, the observer clause, and any side letter that widens access.
- Does the commercial deal stand on its own? If revenue from the strategic is a large share of the total, diligence asks whether the contract is at market price and how it can be terminated. Diligence also asks how much of that revenue would survive if the strategic sold its stake or its sponsor left.
- Will the strategic follow on? The lead asks whether the strategic invests from a fund with reserves or from a business-unit budget, and how it behaved in other companies' later rounds. In a year with corporate program closures, the safe assumption is that it may not.
- Who else will not buy or invest now? If the strategic's main competitors are the startup's best customers or most likely acquirers, the team weighs that lost upside against what the strategic brings.
For analysts and associates, this is ordinary due diligence work: reading the existing financing documents, flagging non-standard rights, and writing up the strategic's role in the investment memo. Founders who answer these six questions before the next raise shorten that diligence.
Examples of strategic investors
The three investors below show the range from a business-aligned venture arm to an affiliate that runs like an independent fund. The figures come from each firm's own site as of October 2026.
Salesforce Ventures
Salesforce Ventures says it has backed more than 700 enterprise software companies since 2009 and invested more than $7 billion. It describes itself as patient capital with an evergreen funding model and pitches its long-term relationships with decision-makers at thousands of businesses. That makes it a platform-aligned strategic, selling access to the enterprise ecosystem around the parent. Profile: Salesforce Ventures on Venture Capital Careers.
Intel Capital
Intel Capital was founded in 1991 and describes itself as the first corporate venture capital firm. It reports more than $20 billion invested and says it leads 75% of its deals on average, with a focus on compute, cloud, silicon, and AI infrastructure. A CVC that often leads is closer to a financial lead in how it negotiates, while its sector focus tracks the parent's technology roadmap. Profile: Intel Capital on Venture Capital Careers.
GV
GV launched as Google Ventures in 2009. Alphabet is its sole limited partner, and the firm says it was designed with the freedom to invest in Google's direct competitors. GV is corporate-affiliated, but it operates much like an independent venture firm. Treat an affiliate like GV differently from a business unit investing off the balance sheet.
Should you take strategic capital? A decision checklist
Run these questions before signing. Every answer in the warning column is a term to renegotiate, or a reason to fill the allocation with financial investors instead.
| Question | Good sign | Warning sign |
|---|---|---|
| What business outcome does the investor want? | Stated plainly and compatible with your roadmap | Vague "synergy," or the investor will not say |
| Who owns the relationship inside the parent? | A named executive outside the venture team | Only the venture team has met you |
| What happens in the first 90 days? | Dated introductions, pilots, or technical reviews | "Access to our network" |
| Does any right touch a sale of the company? | None, or notice only | Right to match or delay offers |
| What information will it receive? | Standard reporting with a Competitor carve-out | Roadmap, customer data, and every board deck |
| Would the commercial deal work without the equity? | Yes, at market terms | The investment is needed to justify the contract |
| How will your next lead read the cap table? | Easy to explain in one sentence | Requires unwinding rights before a new lead commits |
| Will the parent's rivals still buy from you? | Rivals are not core customers or likely acquirers | Your best customers compete with the investor |
Working at a strategic investor
Corporate venture teams hire analysts, associates, principals, and partners like financial firms do, plus roles that exist only inside a corporation, such as business-unit liaison, portfolio partnerships lead, and corporate development manager. The investing work is the same craft as at a VC fund: sourcing, diligence, memos, and portfolio support. The difference is the second audience. A CVC investor has to justify each deal to the investment committee on return and to the parent on strategy, and spends real time moving portfolio companies through the parent's procurement and partnership teams.
Pay structures, carry, and exit paths also differ between independent-style funds and business-unit teams. The comparison of corporate venture capital vs venture capital careers covers those tradeoffs. Open roles at venture firms and corporate venture groups are listed on the Venture Capital Careers job board.
Frequently asked questions
What is a strategic investor in simple terms?
A company that invests in another company because it expects both a financial return and a benefit for its own business, such as a customer, a technology, or a future acquisition.
What is the difference between a strategic investor and a financial investor?
A financial investor earns money only from the value of its shares. A strategic investor also wants a business outcome for its parent, which is why it often asks for commercial agreements, information access, or rights around a sale that a venture fund would not request.
How do I approach strategic investors?
Start with the business unit that would buy or distribute your product, confirm a named sponsor, and bring the venture team in once a financial lead is setting terms. Negotiate any commercial contract separately from the equity.
Is corporate venture capital the same as a strategic investor?
Corporate venture capital is the best-known form of strategic investing, but not the only one. Corporations also invest directly from the balance sheet or through corporate development, and some corporate-affiliated funds, such as GV, behave much like independent venture firms.
Do strategic investors take board seats?
A strategic that leads a round or buys a large stake may negotiate a voting board seat. A strategic that participates behind a financial lead more often asks for a non-voting observer seat. The NVCA model observer clause lets the company withhold materials and exclude the observer when attendance would create a conflict of interest or competitive harm.
Can a startup have both strategic and financial investors?
Yes. A typical structure is a venture firm leading the round and setting terms, with one or more strategics participating on the same documents.
What does strategic investment mean?
In corporate finance, a strategic investment is a stake or partnership investment a company makes mainly for business reasons, such as access to a market or technology. In startup financing it usually means a minority investment by a corporation in a venture-backed company.
Related posts
How the risk factor summation method values a pre-revenue startup, how to score each of the 12 risks with evidence, a worked example with ownership and 10x checks, whether the $250,000 step still fits current seed prices, and how VC analysts use it in memos and interviews.
Growth equity buys minority stakes in proven, growing companies; venture capital backs startups still proving the market. Compare stage, risk, terms, secondaries, loss ratios, 2026 round sizes and careers.
How the Berkus method values a pre-revenue startup, how to score each of the five elements, a worked example with ownership and 10x checks, how the $500,000 caps compare with current seed prices, and how VC analysts use it in memos and interviews.