A venture capitalist invests other people's money through a venture capital fund. An angel investor invests personal capital, usually at an earlier stage and in a smaller check. The labels sound interchangeable on a pitch deck. They are not. Capital source, diligence depth, board rights, and exit pressure all change with who writes the check.
What a venture capitalist is
A venture capitalist (VC) is a professional investor at a firm that raises a fund from limited partners (LPs). Those LPs are typically institutions such as pension funds, endowments, foundations, corporates, and family offices. The firm's general partners (GPs) select companies, negotiate terms, sit on boards, and try to return capital to LPs within a fund life that is often about ten years.
VCs usually write larger checks once a company shows traction. Seed and Series A checks often start in the low millions; later rounds climb from there. Because the money is institutional, decisions typically run through partner review and an investment committee, with legal, commercial, and reference diligence before a wire.
Venture capital is a form of early-stage private investing focused on high-growth companies. It is related to, but not the same as, private equity or growth equity.
What an angel investor is
An angel investor is usually a high-net-worth individual who invests personal cash into a startup in exchange for equity, a convertible note, or a SAFE. Many angels are former founders or operators. Some invest alone. Others join angel groups or online syndicates that pool smaller checks into one vehicle.
Angel checks commonly sit in the tens of thousands to a few hundred thousand dollars per investor. Syndicates and "super angels" can clear larger rounds, but the capital is still personal (or personally aggregated), not an LP-backed institutional fund with a fixed fund clock.
In US private offerings, many angels are accredited investors under SEC rules. Individuals can qualify through net worth over $1 million excluding a primary residence, income over $200,000 individually or $300,000 with a spouse or partner in each of the prior two years with a reasonable expectation of the same, or certain professional licenses and roles. Accreditation is an eligibility screen for many exemptions. It is not a quality signal about the company.
Side-by-side differences
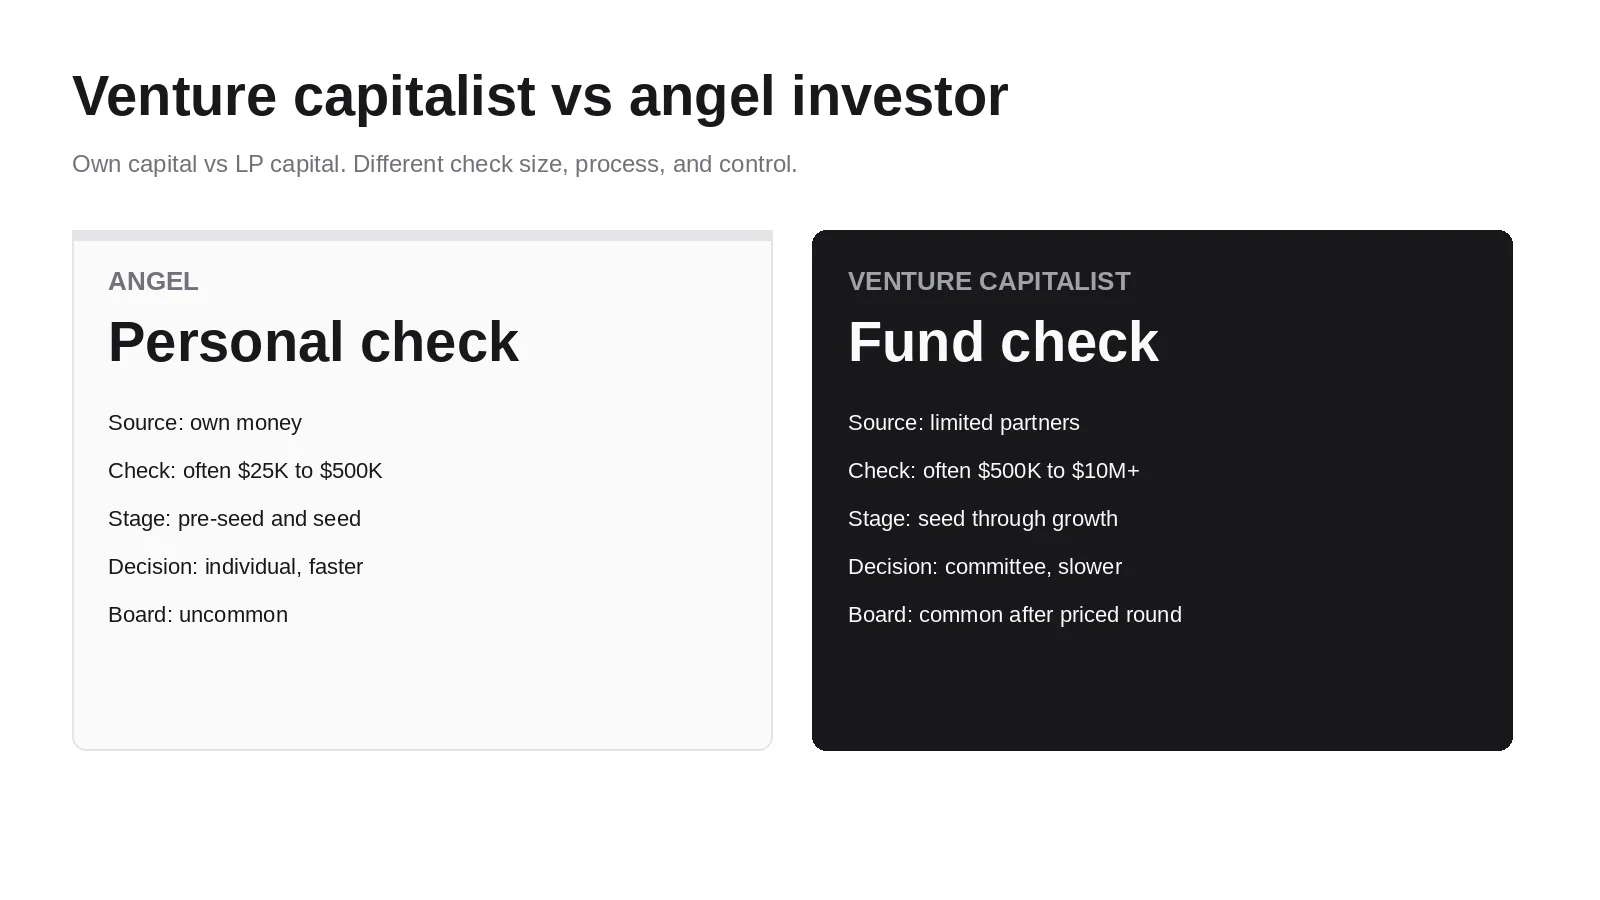
| Dimension | Angel investor | Venture capitalist |
|---|---|---|
| Who they are | Individual investing personally (sometimes via a syndicate/SPV) | Professional at a firm investing a pooled fund |
| Capital source | Own money | Limited partners' capital |
| Typical check | Often ~$25K to $500K per angel; syndicates can aggregate more | Often ~$500K to $10M+ at seed/Series A; larger at later stages |
| Usual stage | Pre-seed and seed; sometimes pre-revenue | Seed through growth, usually after early traction |
| Decision process | Individual conviction; days to weeks when moving fast | Partner + investment committee; often months |
| Diligence | Variable; experience-driven | Structured financial, market, legal, and reference work |
| Post-close role | Mentorship and intros when asked; board seats uncommon | Board seats common after a priced round; formal reporting |
| Return pressure | Flexible personal horizon | Fund life and LP return targets drive exit timing |
These bands are typical, not rules. Micro-VCs write smaller checks. Some angels write seven-figure checks. Seed funds blur the middle. The durable split is still capital source and governance: personal capital with light control versus LP capital with institutional process.
When founders raise from angels vs VCs
Raise from angels when the company is still proving the product, the ask is under roughly $1 to 2M, speed matters more than a brand-name lead, and the founders want to keep board control through the early build.
Raise from VCs when the company needs multi-million-dollar capital to scale, wants institutional follow-on capacity and recruiting networks, and is ready for board governance, preferred stock, and an exit path that can return a fund.
Many companies do both. Angels and scout checks fund the first product and customers. A seed or Series A fund later leads a priced round. Hybrid seed rounds (one institutional lead plus a syndicate of angels) are common. The sequence still matters: messy angel terms, scattered SAFE caps, and no clear lead make the next institutional raise slower and more expensive.
VC money is a tool for a venture-scale outcome. It is not proof the company is finished. Raising before product-market fit locks in growth pressure without the unit economics to absorb it.
Deal terms that usually differ
Angel rounds often use SAFEs or convertible notes. Those instruments delay a full preferred-stock negotiation until a priced round. Information rights are light. Board seats are rare.
VC-led priced rounds usually mean preferred equity with:
- Board composition and observer rights
- Protective provisions (vetoes on major actions)
- Liquidation preference (often 1x non-participating in standard market deals)
- Anti-dilution mechanics on down rounds
- Pro-rata rights for follow-on rounds
None of that is automatically "worse." Institutional capital needs contractual protections because GPs are fiduciaries for LPs. Founders should model the preference stack and the reporting load before treating a VC term sheet as a pure upgrade on angel capital.
What the lead investor type signals
For founders, the lead type sets the operating rhythm of the company. An angel-led seed often means faster closes, lighter reporting, and advice that depends on each angel's available time. A VC-led round usually means a board calendar, monthly or quarterly packs, and a partner who will care about reserve allocation for the next round.
For people building a career around early-stage deals, the same distinction shows up as different jobs:
- On a venture fund desk, analysts and associates screen opportunities against a thesis, build models, run reference calls, and write memos for partners and an investment committee. The check size has to fit fund economics. Passing on a company is often about stage, ownership, or reserves, not personal taste alone.
- On an angel, scout, or syndicate desk, the decision is closer to personal underwriting. Check size is bounded by the individual's or syndicate's wallet. Diligence can be deep, but there is rarely a formal IC. Scouts and angel-group screens still produce written notes; the buyer of the risk is still personal capital.
Reading a round as a candidate or operator:
- Angel-led, no institutional lead: early conviction, often pre-proof. Cap table may be crowded. Ask who sets terms and who will help on the next raise.
- Angel syndicate or rolling fund SPV: looks larger than a single angel, still not a classic LP fund with board machinery unless a lead fund is also in.
- Seed or Series A fund lead: expect preferred terms, board process, and a story that has to survive IC. Roles that touch diligence, platform, or portfolio talent become more formal after this point.
If the question is how venture capital works as an industry, or how it differs from private equity, those are separate pages. This page is only the angel versus VC split.
Frequently asked questions
What is the difference between a venture capitalist and an angel investor?
A venture capitalist invests LP capital through a fund and usually joins later with larger checks and formal governance. An angel investor invests personal capital, usually earlier and in smaller amounts, with lighter control.
Do angel investors or venture capitalists invest more money?
Venture capitalists usually write larger checks because they deploy a pooled fund. Individual angels write smaller checks; angel syndicates can aggregate into larger seed rounds without becoming a traditional VC firm.
Do angels take board seats?
Usually not. Lead angels sometimes ask for observer rights or informal advisory access. Board seats are common for VCs after a priced seed or Series A.
Can a company raise from both angels and VCs?
Yes. Many seed rounds combine an institutional lead with angels filling allocation. Check existing pro-rata and consent rights before adding new investors beside a fund.
Is a venture capitalist the same as a private equity investor?
No. Both are institutional private-market investors, but venture capital targets earlier, higher-growth companies, while private equity more often buys mature businesses. See private equity vs venture capital.
Browse venture capital firms on Venture Capital Careers, or post a role if you hire for a fund or angel platform.
Related posts
Copy-ready VC associate job description template with responsibilities, skills, investing vs sourcing seat signals, interview scorecard, and how candidates should read a posting.
A practical career guide to venture capital fund operations: roles from accountant to CFO or COO, skills and proof of work, and how to evaluate the seat before you apply.
Prepare for analyst and associate VC interviews with 25 questions, answer frameworks, technical priorities, and role-level calibration.