Pre-seed funding is the first outside capital a startup raises, usually before a priced seed round. The money is meant to turn a founding team and a problem into something later investors can diligence: a prototype, early customer evidence, and a company that can take a term sheet. Most of these rounds close on a SAFE or a convertible note rather than preferred stock. The investor is betting on the founders and the insight, not on revenue.
Carta published a founder guide on 12 February 2026 that treats pre-seed as any funding that comes before seed, and says the label is still debated. Historically Carta defined it as funding before a company first prices a round.
What pre-seed funding is
Pre-seed sits after friends-and-family cash or founder savings, and before seed. Some people fold friends and family into the pre-seed label. Others reserve the word for the first institutional check. The useful test is not the name on the deck. It is what evidence exists when the money lands.
At a true pre-seed, the company is usually pre-revenue. It may have a prototype, a set of customer interviews, or a waitlist. It rarely has a repeatable sales motion. The round funds the experiment: incorporation, an MVP, the first hire or two, and enough runway to produce seed-quality evidence.
That is different from a small seed that someone labeled pre-seed to sound earlier. If the company already has paying customers, retention a stranger would believe, and a motion it would scale, the raise is a seed even if the deck says otherwise.
How a pre-seed round works
- Founders decide what proof the next round requires and how many months that takes.
- They pick an instrument, usually a post-money SAFE with a valuation cap.
- They build a list of people who actually write first checks in that sector.
- Checks land over weeks, often from several angels plus one micro-fund or an accelerator.
- Each instrument sits on the cap table as a future claim, not as issued preferred stock.
- The company spends the cash against a short milestone list: product, evidence, team.
The close is usually faster than a priced Series A because there is no full preferred-stock documents package. Speed is the point. So is deferred valuation. Pricing happens when a later investor is willing to set a price per share.
Pre-seed vs friends and family vs seed
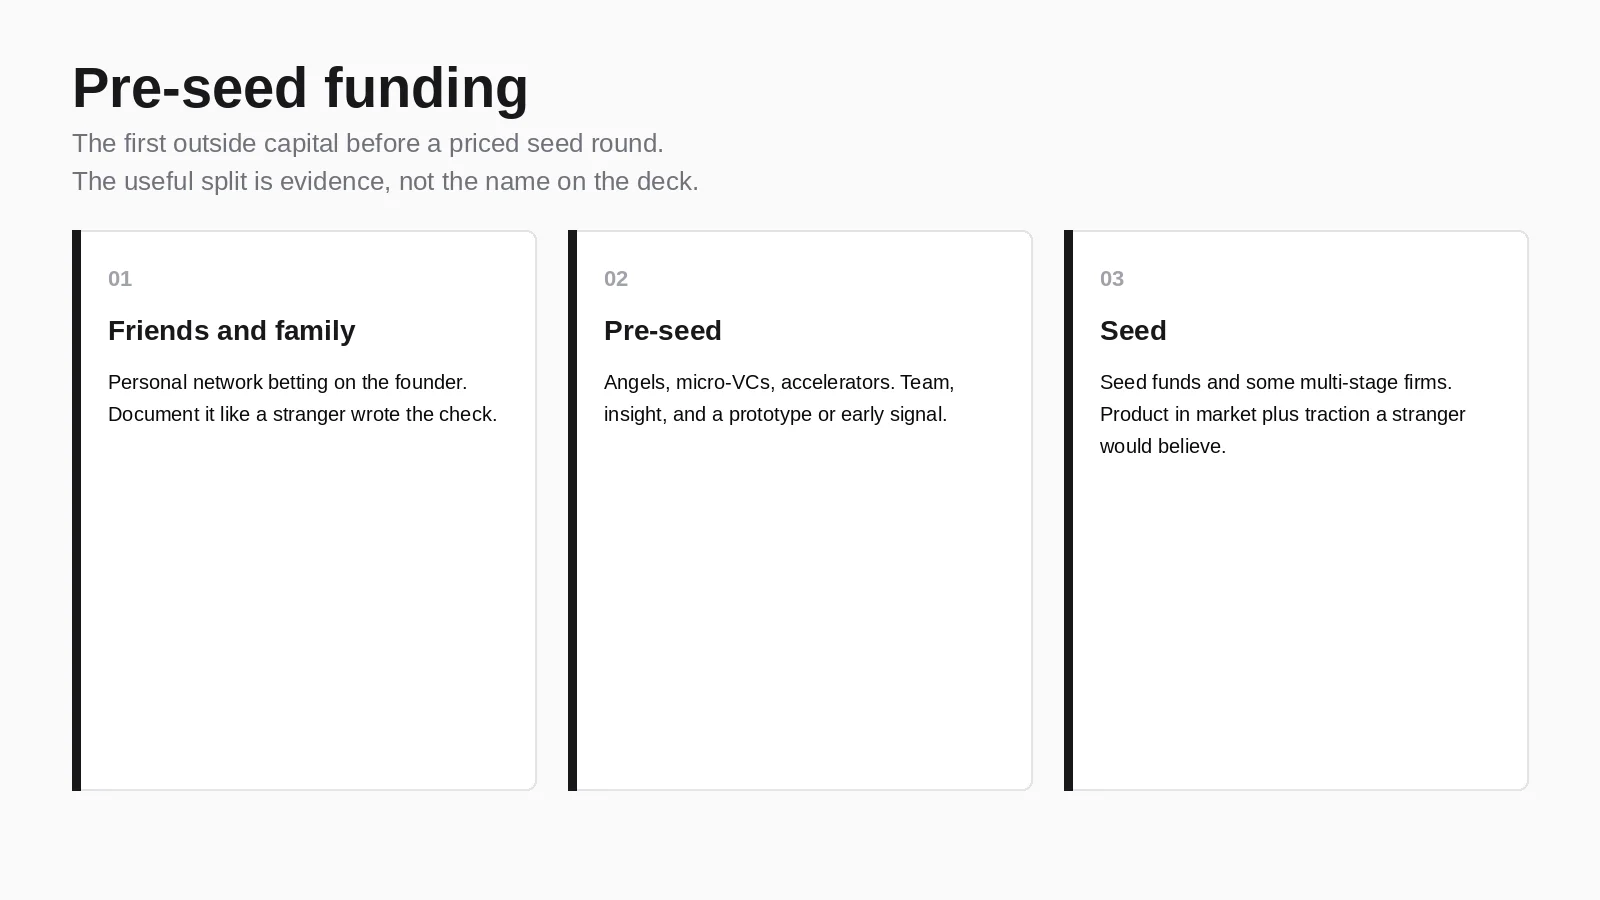
| Friends and family | Pre-seed | Seed | |
|---|---|---|---|
| Who writes | Personal network | Angels, micro-VCs, accelerators | Seed funds, some multi-stage firms |
| Evidence | Belief in the founder | Team, insight, prototype or early signal | Product in market plus traction a stranger would believe |
| Typical instrument | Informal paper or a simple SAFE | SAFE or convertible note | SAFE or priced preferred |
| What the money buys | Time to start | The experiment | Scaling a motion that already works |
Carta's 12 February 2026 guide puts typical pre-seed raises in the few-hundred-thousand range, roughly $250,000 to $1 million, and seed in a wider $500,000 to $5 million band. Treat those as ranges on one cap-table platform, not as a rule for a given company.
Friends-and-family money is often the first cash. It is not required. Many companies never raise it. When it is used, document it with the same instrument you would give a stranger. Informal IOUs become a diligence problem later.
Who writes pre-seed checks
Four sources show up on most first rounds:
- Founders, friends, and family
- Angel investors and syndicates, including checks pooled through an SPV
- Accelerators and incubators, which trade standardized cash and a program for equity
- Pre-seed micro-funds that exist to write the first institutional check
Larger multi-stage firms sometimes appear. They are not the default path for a first-time founder without a prior relationship. Browse firms by stage rather than spraying a brand-name list.
Do not treat a 2026 best-investors article as a target list. Directories go stale. The job is to match the source to the evidence you have.
How much to raise and what the money is for
Raise the cash that buys the next fundable milestone, plus a buffer for the next process. Carta's 12 February 2026 guide says aim for at least a year to a year and a half of runway to the seed milestones. Size from monthly burn, not from a number on a listicle.
Typical uses:
- Company setup and legal
- MVP or prototype
- Customer discovery
- One or two early hires
- Enough operating cash that the company is not raising again in six months
Over-raising at a high cap can make the next round harder if the evidence does not catch up. Under-raising produces a bridge. Neither is a strategy.
Instruments: SAFE, convertible note, or priced equity
Most pre-seed money arrives as a convertible instrument.
A SAFE is a short contract for cash today and shares later. Y Combinator describes it as the right to stock at a later priced round, not a loan. It has no interest and no maturity date. The usual term to negotiate is the valuation cap.
A convertible note is debt that converts. It has principal, interest, and a maturity date. Use it when the investor wants a deadline, or when the legal market still prefers notes.
A priced round issues preferred stock now. It is slower and more expensive. It shows up when the raise is large enough that a lead wants a price and governance, or when the company is already past a true pre-seed.
Conversion math belongs with the instrument you are actually reading.
How a VC screens a pre-seed round
Founder guides stop at bet-on-the-team. The job on an investment committee is more specific.
What the associate actually opens
- Incorporation, founder vesting, and IP assignment
- The SAFE or note schedule: holder, date, amount, cap, discount, MFN, pro rata, side letters
- What the next 12 to 18 months of spend produces that a seed investor would accept
- Whether the market story is bottoms-up (named customers) or a top-down TAM slide
- Who else is in the round and whether the cap table will be workable at seed
The five questions that decide the memo
- Founder-market fit: why these people, on this problem, now.
- Insight: a claim about the market that is specific and checkable.
- Evidence: interviews, prototype, letters of intent, or usage, labeled honestly.
- Capital plan: what this exact raise proves, and what happens if it takes longer.
- Instrument risk: stacked caps, MFN, missing IP, friends-and-family paper that was never documented.
What does not belong in a pre-seed memo
Revenue multiples, CAC to LTV ratios, and three-year models that assume a sales team the company does not have. If those are required to approve the deal, the underwriting is seed, not pre-seed.
People who do this work sit on Venture Capital Careers. The same screen is the core of venture capital due diligence.
When pre-seed is the wrong raise
- The company already has a product customers pay for and a motion it would scale. Raise seed.
- The check is large enough that the lead wants a priced round and board documents.
- Nobody can name the milestone the money buys.
- The only path is dozens of tiny checks with mismatched caps. Clean that up or wait.
Frequently asked questions
What is pre-seed funding?
The first outside capital before a seed round, usually on a SAFE or note, used to build evidence rather than to scale.
How much do companies raise?
Carta's 12 February 2026 guide cites a few hundred thousand dollars as typical, often about $250,000 to $1 million, with smaller and larger outliers. Size from runway to the next milestone.
Is pre-seed the same as friends and family?
Sometimes people use the words interchangeably. Friends-and-family is a source. Pre-seed is a stage. Institutional pre-seed can happen without a friends-and-family round.
Do you need revenue?
No. You need a reason the next investor will believe the experiment is working.
SAFE or convertible note?
SAFE if you want speed and no maturity. Note if the investor wants debt terms.
What should a VC look for?
A readable instrument schedule, founder-market fit, a specific insight, and a capital plan that produces seed evidence.
Next steps
Define the stage, separate it from friends-and-family and seed, and read the paper the way an associate would. Then continue to seed funding, SAFE, convertible note, and open roles for people who work these deals.
Related posts
Copy-ready VC associate job description template with responsibilities, skills, investing vs sourcing seat signals, interview scorecard, and how candidates should read a posting.
A practical career guide to venture capital fund operations: roles from accountant to CFO or COO, skills and proof of work, and how to evaluate the seat before you apply.
Prepare for analyst and associate VC interviews with 25 questions, answer frameworks, technical priorities, and role-level calibration.