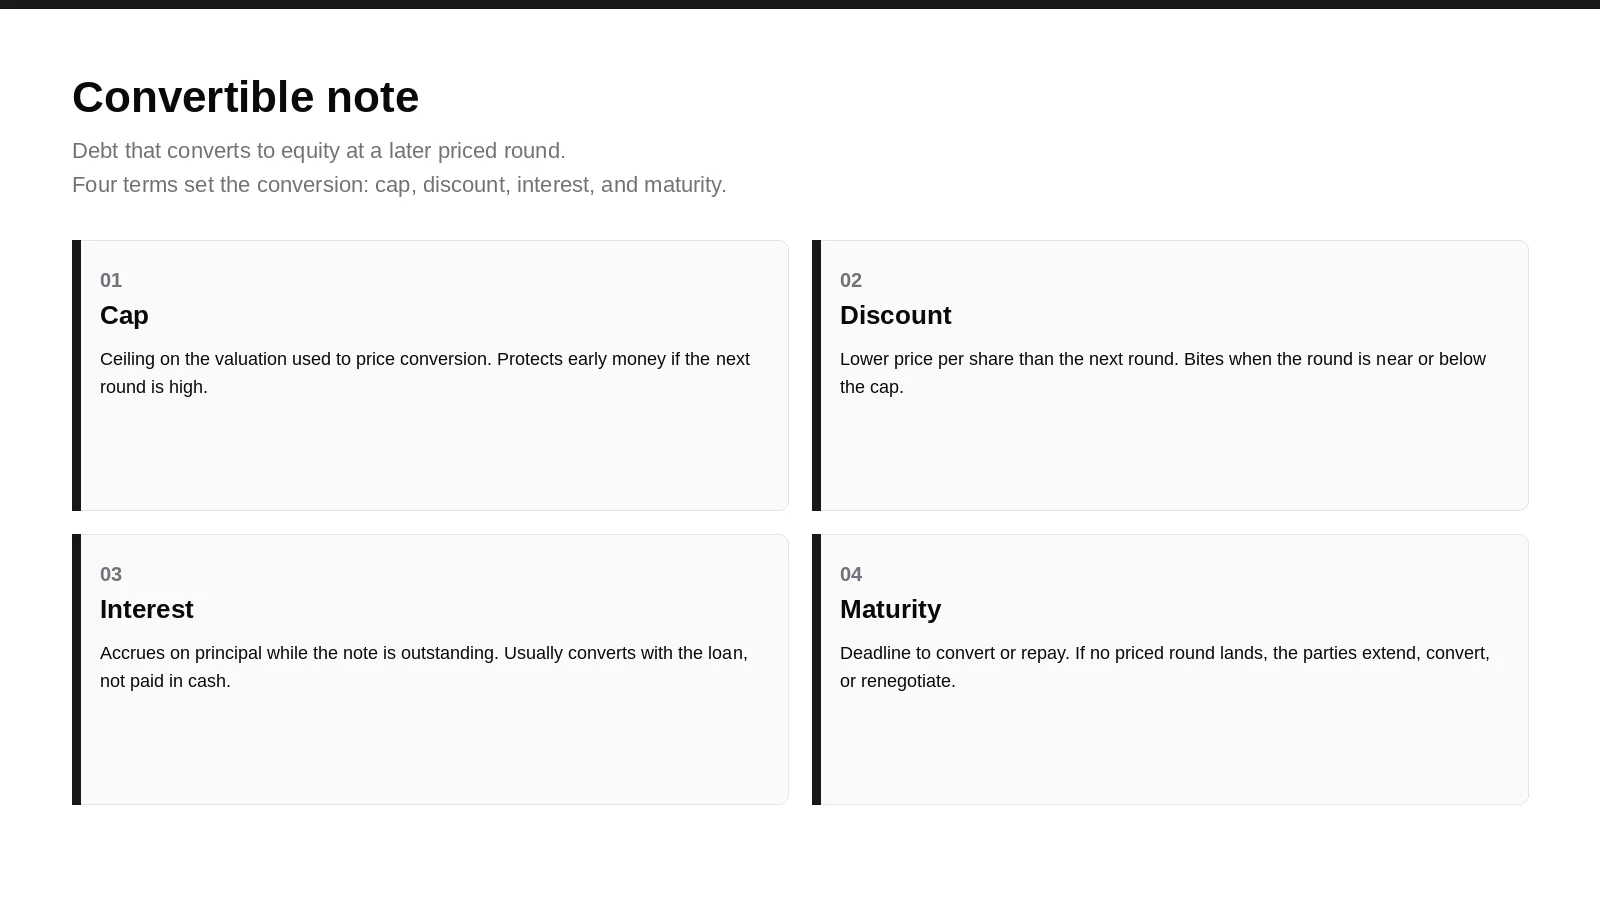
A convertible note is short-term debt that converts into equity, usually when the company later raises a priced round, instead of being repaid in cash. Until conversion, it is a loan: it has a principal, it accrues interest, and it has a maturity date. The conversion price is typically the better of two investor protections, a valuation cap and a discount to the next round.
Startups use notes to take pre-seed or seed capital before they can defend a price in a term sheet. Analysts and associates who screen these deals need the same facts: which term bites, what the cap table looks like after conversion, and what happens if no priced round arrives.
What a convertible note is
A convertible note, also called a convertible promissory note or convertible loan note, is a hybrid instrument. The investor wires cash today. The company issues a promissory note. Later, if a qualified equity financing closes, principal plus accrued interest converts into shares, typically the same preferred stock sold in that round, at a cheaper price than new money pays.
It is not a public convertible bond. Corporate convertibles are longer-term securities issued by established companies and often trade. Startup notes are private, short-form, and designed to convert at the next financing rather than to trade.
Until conversion, the holder is a creditor, not a shareholder. Notes usually carry no voting rights, no board seat, and none of the liquidation preference of preferred stock. After conversion, the holder becomes an equity owner on the terms of the round, or on a specified fallback.
On the balance sheet, an outstanding note is a liability. After conversion it is equity. That is why a stack of unconverted notes shows up in diligence as debt overhang, not as an already-issued share class.
How a convertible note works
- The investor funds the note. Principal is the cash received.
- Interest accrues while the note is outstanding. It is usually added to principal at conversion rather than paid in cash.
- A triggering event occurs. The most common is a qualified priced round, meaning a sale of preferred stock above a dollar threshold defined in the note. A sale of the company can also force conversion or a repayment, depending on the document.
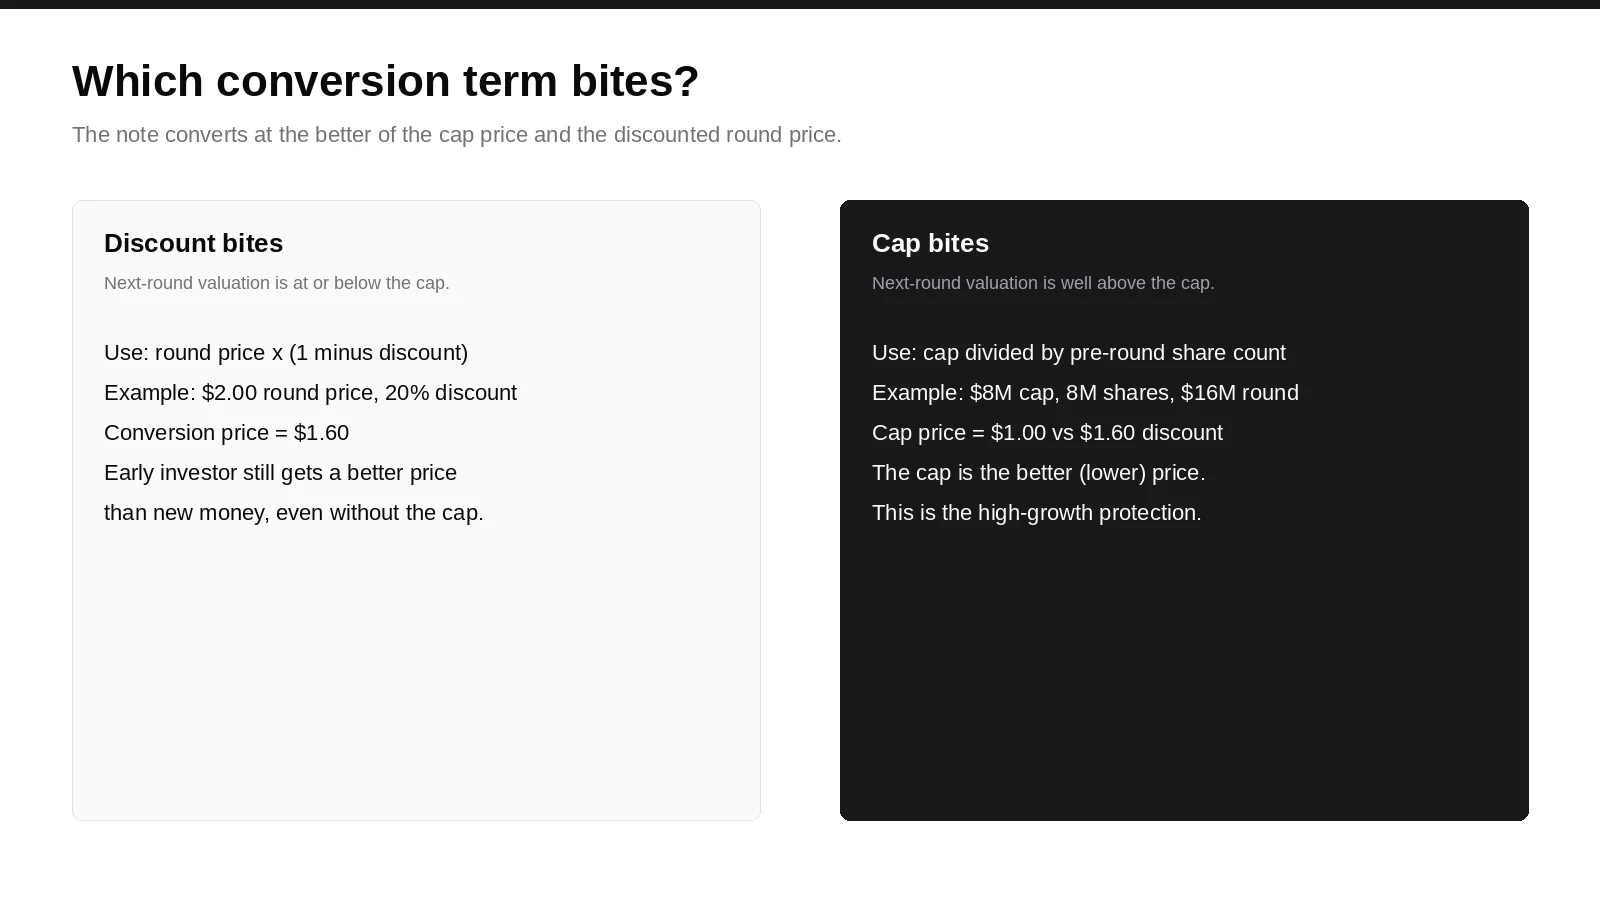
- Conversion math runs. The note typically converts at the better of the cap price and the discounted round price.
- If no trigger occurs by maturity, the note is legally due. In practice the parties usually extend the maturity, convert at an agreed valuation, or amend terms. Cash repayment is rare because early-stage companies rarely have the cash.
The point of the instrument is speed and deferred valuation. A priced seed or Series A round requires agreeing a price per share, updating corporate documents, and issuing preferred stock now. A note lets the company take money first and set the price when later investors price the round.
The four terms that decide conversion
| Term | What it does | Why it matters |
|---|---|---|
| Cap | Ceiling on the company valuation used to price conversion | Protects early investors if the next round is much higher |
| Discount | Percentage off the next round's price per share | Protects early investors when the next round is not far above the cap |
| Interest | Accrual on principal while the note is outstanding | Increases the dollars that convert, so it increases share count |
| Maturity | Date the loan is due if it has not converted | Creates a deadline and a renegotiation point |
A note can include a cap, a discount, both, or (rarely) neither. When both exist, conversion typically uses whichever produces the lower price per share for the noteholder, which means more shares.
Other clauses that change outcomes:
- Qualified financing threshold: the minimum round size and instrument type that trigger automatic conversion. A small insider round may not convert the notes.
- Most favored nation (MFN): if a later note is issued on better terms, earlier notes can step into those terms.
- Change of control: what the holder gets in a sale before a priced round (convert at the cap, a multiple of principal, or a choice).
- Amendment: whether a majority of principal can extend maturity, or every holder must consent.
Do not treat "market" percentages as facts. Interest, discount, cap, and maturity are negotiated in the note you are reading. If a live document states a number, use that number.
How conversion math works
Worked illustration, not a market survey. Interest is ignored so the mechanism is visible.
- Note principal: $250,000
- Valuation cap: $8,000,000 (pre-money)
- Discount: 20%
- Next priced round: $4,000,000 of new money at a $16,000,000 pre-money valuation
- Pre-round fully diluted shares used to set the round price: 8,000,000
New-investor price per share = $16,000,000 / 8,000,000 = $2.00
Discount price = $2.00 x (1 - 0.20) = $1.60
Cap price = $8,000,000 / 8,000,000 = $1.00
The cap is the better price for the noteholder. Shares issued on conversion = $250,000 / $1.00 = 250,000. The same $250,000 in the priced round at $2.00 would have bought 125,000 shares.
If the next round had been at or below the $8,000,000 cap, the discount would have been the term that bites instead.
In a memo, state three things: the conversion price used, why that price won, and the fully diluted ownership after the new round plus conversion. Accrued interest, if any, increases the numerator (dollars converting) and therefore the share count.
How a VC screens a convertible note
Founder-facing explainers stop at deferred valuation and a fast close. The job on an investment team is to read the stack of notes on a live deal.
Build the note schedule
For every outstanding note, capture:
- Holder, date, and principal
- Cap, and whether it is defined as pre-money or another way
- Discount
- Interest rate and whether it is simple or compound
- Maturity date
- Qualified financing definition and dollar threshold
- MFN, pro rata, or information rights
- What happens on a sale
One row per instrument. Mixed caps and staggered maturities are the usual mess.
Model three next-round cases
- Round well above the cap: the cap bites; dilution to founders and new money can be large.
- Round near the cap: the discount often bites; the early-investor reward is modest.
- No round, or a delayed round: maturity risk, amendment risk, possible forced conversion.
If several notes have different caps, run them separately. Do not average caps.
Ask process questions, not only economics
- Will this financing actually be a qualified financing under the notes, or will notes remain outstanding after close?
- Are maturities inside the expected close window?
- Did later notes get a better cap that MFN will pull forward?
- Is interest material on a long-dated stack, or rounding error?
- On a sale tomorrow, does the holder get a repayment multiple or convert at the cap?
Those questions belong in venture capital due diligence and in the investment memo. An associate who can say which term bites, and why, is doing the job.
People who work these deals look at open roles on Venture Capital Careers.
Convertible note vs SAFE vs priced equity
Y Combinator describes a SAFE as a short contract for the right to shares later, not a loan. A SAFE does not accrue interest and does not have a maturity date. A convertible note does both.
| Convertible note | SAFE | Priced equity | |
|---|---|---|---|
| Instrument | Debt that converts | Contract for future equity | Shares issued now |
| Valuation today | Deferred | Deferred | Set now |
| Interest | Yes, negotiated | No | No |
| Maturity / repayment | Yes | No | No |
| Balance sheet | Liability until conversion | Not debt | Equity |
| Governance today | Usually none | None | Preferred rights, often a board seat |
A SAFE is the no-debt version of deferred equity. The side-by-side lives on SAFE vs convertible note. Use a note when investors want a debt wrapper and a deadline. Use a SAFE when both sides want future equity without a loan. Use a priced round when the company can defend a valuation and wants a clean cap table now.
When a convertible note is the right instrument
Notes fit when:
- The company needs capital before it can defend a valuation, typical at pre-seed and early seed
- The raise is a bridge to a named priced round, not a substitute for one
- Speed and simpler documents matter more than installing preferred-stock governance today
- Check sizes are small enough that a full preferred round is not worth the delay
Notes are a poor fit when:
- The company can already defend a valuation and wants a clean cap table
- The raise is large enough that later investors will demand a priced round anyway
- Runway may slip past maturity with no credible path to a qualified financing
- Multiple notes with inconsistent caps, discounts, and MFN clauses have already stacked into a conversion mess
What happens at maturity, sale, or failure
Maturity without a priced round. The note is due. Cash repayment is legally available and rarely realistic. The usual paths are an extension, conversion at an agreed valuation, or a broader amendment. Staggered maturities across several notes multiply the negotiation.
Sale of the company. The note either converts (often at the cap or a specified price) or is repaid, sometimes at a multiple of principal. Read the change-of-control section. Do not assume the holder automatically gets the same outcome as preferred stock.
Failure or insolvency. The holder is a creditor. Most seed notes are unsecured and sit behind any secured lender. In a failed startup there is often little or nothing to recover. Priority over common stock is real in theory and thin in practice.
Frequently asked questions
Is a convertible note debt or equity?
Both, at different times. Until conversion it is debt. After conversion it is equity.
How does a convertible note show up on the balance sheet?
As a liability while outstanding. Interest that accrues increases the amount that will convert. After conversion the liability comes off and shares appear on the cap table.
What is the difference between a convertible note and a convertible bond?
A startup convertible note is a private, short-term promissory note meant to convert at the next financing. A convertible bond is a longer-term security, often issued by a public or later-stage company, that can convert into common stock on stated terms and may trade. They share a conversion idea and almost nothing else in documentation, investors, or process.
Do convertible notes have voting rights?
Usually not before conversion. After conversion the holder has whatever voting and protective rights attach to the stock received.
Can the company repay the note in cash instead of converting?
The document often allows it. In an operating startup the expected outcome is conversion. Cash repayment shows up mainly in a wind-down or a negotiated exit from the instrument.
What should a junior investor put in a memo about a convertible note?
Principal plus accrued interest, cap, discount, which term bites at the proposed round, share count and ownership after conversion, whether the round is a qualified financing, maturity date relative to close, and sale treatment.
Next steps
- Read the actual note. Pull cap, discount, interest, maturity, and the qualified financing definition into one row.
- Run the conversion math at the proposed round price and at the cap. Record which term bites.
- Check the rest of the stack for mixed caps, MFN, and nearby maturities.
- For instrument choice, use the SAFE and SAFE vs convertible note pages. For the round around the note, use term sheets, seed funding, and Series A funding.
- Browse open investing roles on Venture Capital Careers if reading these documents is the job.
Related posts
A VC resume is a one-page evidence document. Structure, bullet formula, path and firm-type tailoring, template, and examples partners actually screen for.
Cap table interview questions test whether you can track ownership through a round without freezing. Practice the math, then practice saying the answer out loud.
A practical system for getting a job in venture capital: paths by background, proof-of-work, how to screen postings, a 90-day plan, outreach, interviews, and how to evaluate a seat.