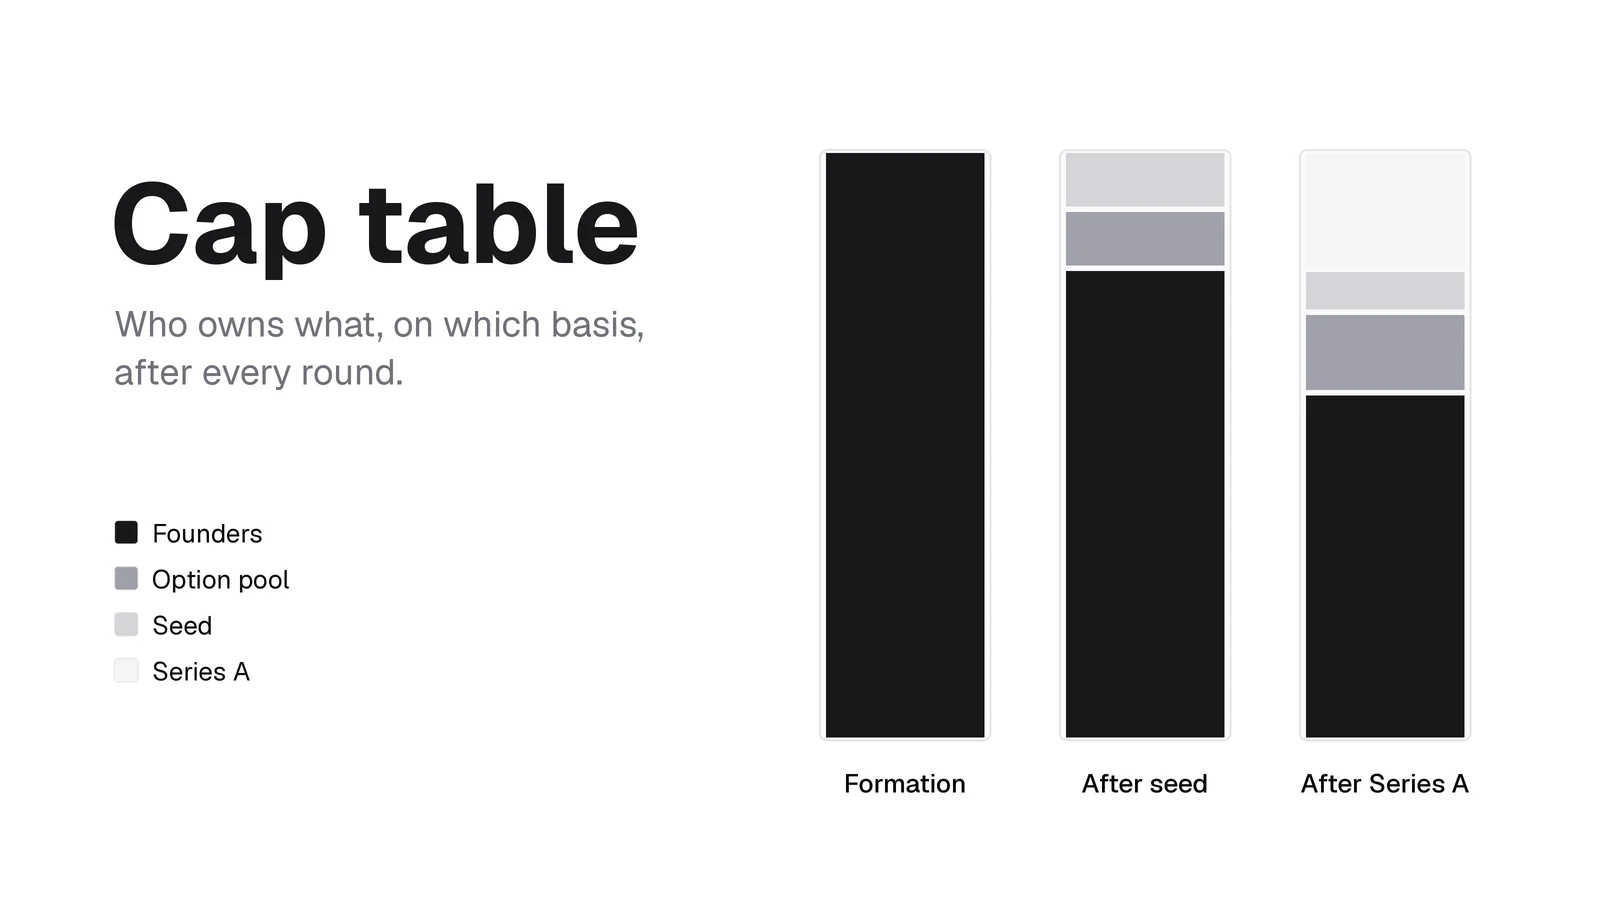
A cap table, short for capitalization table, is the record of who owns a company's equity. It lists every class of stock, every option and warrant, and every SAFE or convertible note that may turn into shares, with each holder's share count and percentage ownership on a stated basis.
Founders use it to track dilution and grant equity. Investors use it to price a round and confirm what they are buying. Employees use it, when they can see it, to translate an option grant into a percentage of the company. A good cap table also ties every number to a signed document, and its ownership column adds up to 100%.
What is a cap table?
Most cap tables have two layers. A summary shows holders or holder groups in rows and security types in columns: common stock, each series of preferred stock, options, warrants, and convertibles, followed by total shares and ownership percentages. A detail layer, often on separate tabs, records each issuance, grant, and instrument with its date, price, and terms.
The cap table matters at specific moments:
- Formation. Founder shares, vesting, and the first equity plan reserve go on the table.
- Hiring. Each option grant comes out of the plan reserve, and the strike price ties to the company's 409A valuation.
- Fundraising. The round price is set by dividing the pre-money valuation by an agreed share count taken from the cap table.
- Exit. Sale proceeds are split according to the cap table and the preferences attached to each class.
Private companies keep their own cap tables. Public companies track holders through transfer agents and brokers, so the term mostly belongs to startups and other private companies.
What a cap table includes
Each line on a cap table should point to a source document. If it does not, it is an assumption, and it should be labeled as one.
| Item | What it records | Source document |
|---|---|---|
| Authorized shares | Maximum shares the company may issue, by class | Certificate of incorporation |
| Common stock | Founder and employee shares, issue dates, vesting | Stock ledger, stock purchase agreements, board approvals |
| Preferred stock | Shares by series, price paid, liquidation preference, conversion ratio | Financing documents and the charter |
| Options and RSUs | Granted, exercised, cancelled, and unissued awards; strike prices | Equity incentive plan, grant notices, board approvals |
| Restricted stock | Shares subject to vesting or repurchase | Restricted stock agreements |
| Warrants | Shares a holder may buy, at what price, until when | Warrant agreements |
| SAFEs and convertible notes | Amount, valuation cap, discount, interest, MFN terms | The instruments and any side letters |
| Ownership percentage | Each holder's share of the total, on a labeled basis | Calculated from the rows above |
Some rights do not show up as a percentage at all. Liquidation preferences, voting rights, protective provisions, and pro rata rights sit in the financing documents. A complete cap table tracks them next to the share counts, because two holders with the same number of shares can have very different economics and control.
Issued, outstanding, and fully diluted ownership
Most cap table arguments start with the denominator. A founder quotes ownership of issued shares, an investor quotes fully diluted ownership, and both think they are talking about the same number.
| View | What it counts | When it is used |
|---|---|---|
| Authorized | Every share the charter allows, issued or not | Checking headroom before a round or a grant |
| Issued and outstanding | Shares actually issued and held today | Voting, stockholder lists, legal ownership |
| Fully diluted | Outstanding shares plus options, the unissued pool, warrants, and convertibles as defined | Pricing a round and quoting investor ownership |
| Pro forma | The fully diluted view after a proposed transaction | Negotiating a term sheet |
Term sheets usually quote price and ownership on a fully diluted basis, and the exact definition is negotiated. It may include the unissued pool, promised grants, or a pool increase that only exists because of the new round. Post-money SAFEs use their own capitalization definitions, set out in the Y Combinator Safe user guide.
The working rule is to put the basis next to every percentage. "Founders own 60%" is ambiguous. "Founders own 60% of post-money fully diluted capitalization, including a 10% unissued pool" can be checked.
Cap table example: formation to seed
The example below follows one hypothetical company. The numbers are illustrative and every table sums to 100%.
Two founders incorporate and each buys 4,000,000 shares of common stock. The board adopts an equity plan reserving 1,000,000 shares and grants 500,000 options to the first hires.
| Holder | Security | Shares | Fully diluted ownership |
|---|---|---|---|
| Founder A | Common | 4,000,000 | 44.44% |
| Founder B | Common | 4,000,000 | 44.44% |
| Employees | Granted options | 500,000 | 5.56% |
| Unissued pool | Reserved options | 500,000 | 5.56% |
| Total | 9,000,000 | 100.00% |
The company then raises a $1.5 million priced seed round at a $13.5 million pre-money valuation. The price per share is $13.5 million divided by 9,000,000 fully diluted shares, or $1.50. The seed investor buys 1,000,000 shares of Series Seed preferred for $1.5 million, and the post-money valuation is $15 million.
| Holder | Security | Shares | Fully diluted ownership |
|---|---|---|---|
| Founder A | Common | 4,000,000 | 40.00% |
| Founder B | Common | 4,000,000 | 40.00% |
| Employees | Granted options | 500,000 | 5.00% |
| Unissued pool | Reserved options | 500,000 | 5.00% |
| Seed investor | Series Seed preferred, 1x non-participating | 1,000,000 | 10.00% |
| Total | 10,000,000 | 100.00% |
If the seed had been a SAFE instead, the cap table would show the SAFE as an outstanding instrument with its amount, cap, and discount, but no share count. It converts into preferred stock at the next priced round, and the pro forma for that round has to model the conversion. The SAFE vs convertible note guide covers how the two instruments convert.
How to read this cap table
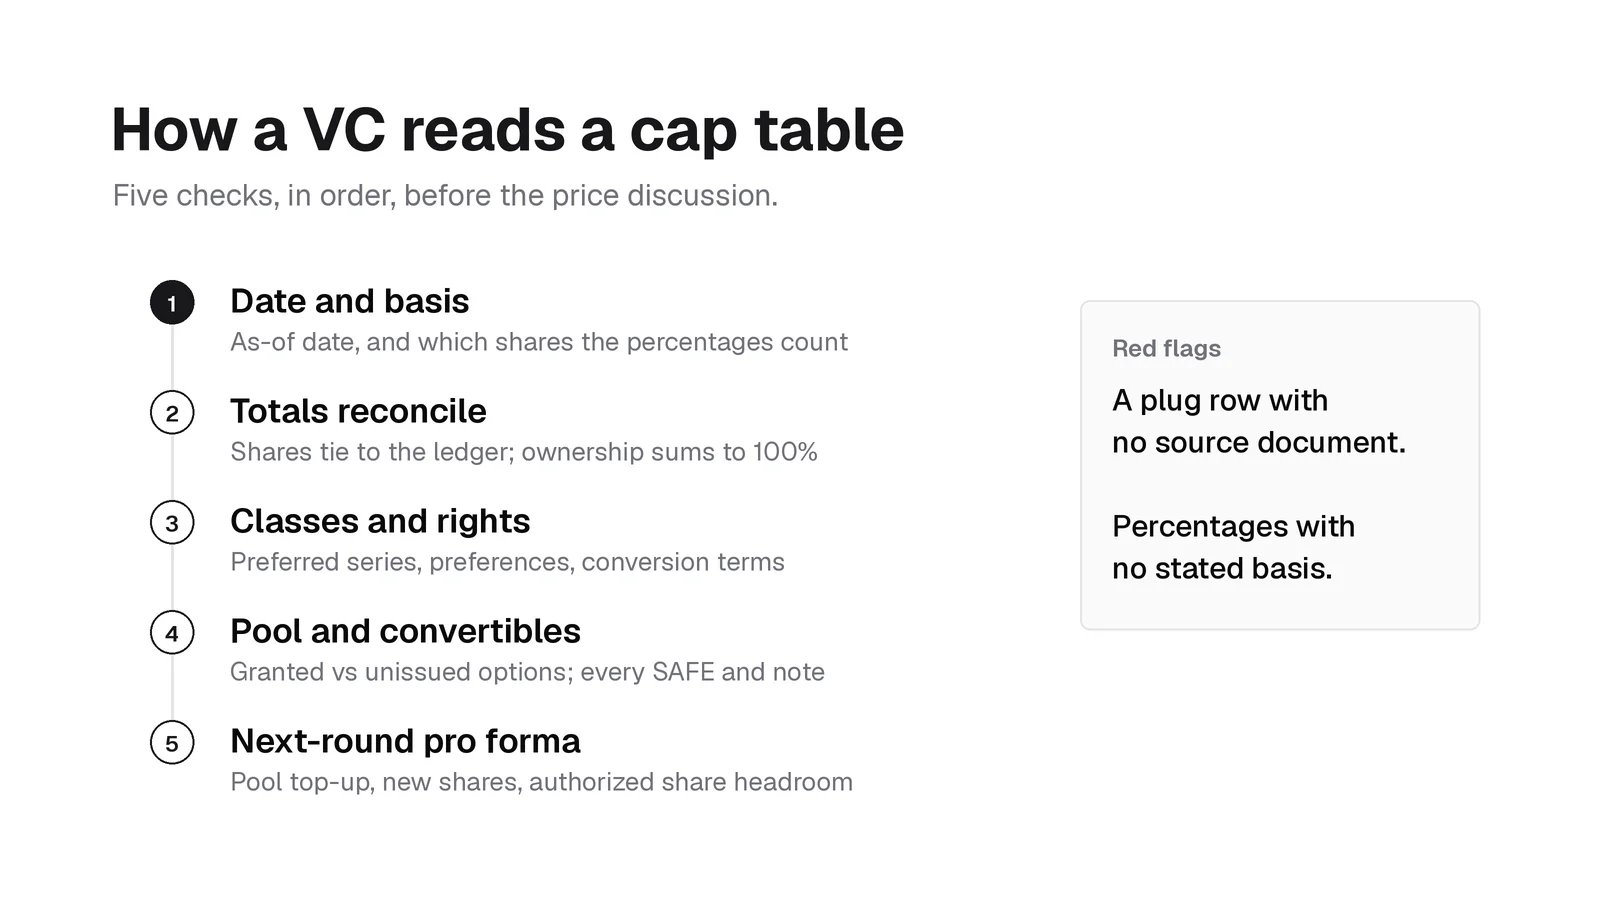
Read a cap table in the same order every time:
- Date and basis. Find the as-of date and confirm which shares the percentages count. This table is fully diluted, so the unissued pool is in the denominator.
- Totals. Check that shares add up and ownership sums to 100%. Rounding differences should be disclosed, not buried.
- Classes. Separate common from preferred. The seed investor's 10% comes with a 1x preference that common does not have.
- Pool. Split granted options from the unissued reserve. Only the unissued 500,000 shares are available for new hires.
- Convertibles. Look for SAFEs, notes, and warrants that have not converted. Each one will change the next round's math.
- What is missing. Ask about promised grants, side letters, and transfers that have not been recorded yet.
How to create a cap table
1. Start from the charter and the stock ledger
Record authorized shares by class from the certificate of incorporation, then every issuance from the stock ledger and board approvals. The cap table should never contain shares the ledger does not.
2. Add founder stock and vesting
Enter each founder's shares, purchase price, issue date, and vesting schedule. Note whether each founder filed an 83(b) election, because diligence will ask.
3. Add the equity plan in three parts
Show granted, exercised, and unissued awards separately. The plan total should equal the board-approved reserve. A grant promised in an offer letter but not yet approved goes on a separate, labeled line.
4. Add investors and convertibles as separate rows
Give each series of preferred stock its own column with price, shares, and preference. List each SAFE, note, and warrant separately until identical terms are confirmed. Grouping instruments with different caps or discounts hides the conversion math.
5. Label the basis and check the totals
State the as-of date and whether each percentage is issued, outstanding, or fully diluted. Confirm that shares reconcile to the ledger and percentages sum to 100%.
6. Update after every equity event
These events change a cap table and should be recorded when they happen:
- New share issuances and financing closings
- Option grants, exercises, cancellations, and forfeitures when employees leave
- Repurchases of unvested founder or employee stock
- Transfers and secondary sales between holders
- SAFE, note, and warrant conversions
- Equity plan increases approved by the board and stockholders
How dilution shows up round by round
In the example, the founders own 88.89% fully diluted after the plan is adopted and 80% after the seed. A Series A pushes that toward 60%, as the next section shows. Percentage ownership falls every time new shares are issued, but the value of each share can rise. The founders' 8,000,000 shares were priced at $1.50 in the seed and are priced at about $1.84 in the Series A modeled below.
Real companies dilute faster than this tidy example. Carta's Founder Ownership Report 2026 found that the median founding team retained about 56% of fully diluted equity after a seed round and about 36% after a Series A, based on rounds raised on Carta from 2021 through 2025. The same report put the median employee pool at 12.1% at seed, and found that by Series C the median employee pool (16.8%) is larger than median founder ownership (16.1%).
The useful habit is to model the next two rounds before agreeing to the current one. A pool size or valuation that looks harmless in isolation can compound across rounds.
Pro forma cap table: modeling the next round
A pro forma cap table shows what the cap table would look like after a proposed transaction, usually the next priced round. It starts from the current fully diluted cap table and applies the term sheet. For a simple priced round:
- Post-money valuation = pre-money valuation + new investment
- Price per share = pre-money valuation / agreed pre-money fully diluted shares
- New investor shares = new investment / price per share
- Post-money ownership = holder's shares / post-money fully diluted shares
Assume the company from the example raises a $5 million Series A at a $20 million pre-money valuation, with no change to the option pool. The price is $20 million divided by 10,000,000 shares, or $2.00. The investor gets 2,500,000 shares, and the post-money share count is 12,500,000.
| Holder | Shares | Post-money ownership |
|---|---|---|
| Founders | 8,000,000 | 64.00% |
| Granted options | 500,000 | 4.00% |
| Unissued pool | 500,000 | 4.00% |
| Seed investor | 1,000,000 | 8.00% |
| Series A investor | 2,500,000 | 20.00% |
| Total | 12,500,000 | 100.00% |
Now assume the term sheet requires the unissued pool to equal 10% of post-money fully diluted shares, with the increase counted in the pre-money share count. The model has to solve for the pool top-up first. Let T be the new pool shares. Because the investor owns 20% post-money, post-money shares are 1.25 times the adjusted pre-money shares:
(500,000 + T) / [1.25 × (10,000,000 + T)] = 10%
That gives a top-up of about 857,143 shares. The adjusted pre-money share count is 10,857,143, the price falls to about $1.8421, and the Series A investor receives about 2,714,286 shares.
| Holder | Shares | Post-money ownership |
|---|---|---|
| Founders | 8,000,000 | 58.95% |
| Granted options | 500,000 | 3.68% |
| Unissued pool | 1,357,143 | 10.00% |
| Seed investor | 1,000,000 | 7.37% |
| Series A investor | 2,714,286 | 20.00% |
| Total | 13,571,429 | 100.00% |
The investor still owns 20%. The founders drop from 64% to about 58.95%, and the seed investor from 8% to about 7.37%. Putting the pool increase in the pre-money share count means existing holders absorb all of the new pool. Before agreeing to a pool target, size it against an actual hiring plan and confirm whether the target refers to the total pool or only the unissued portion.
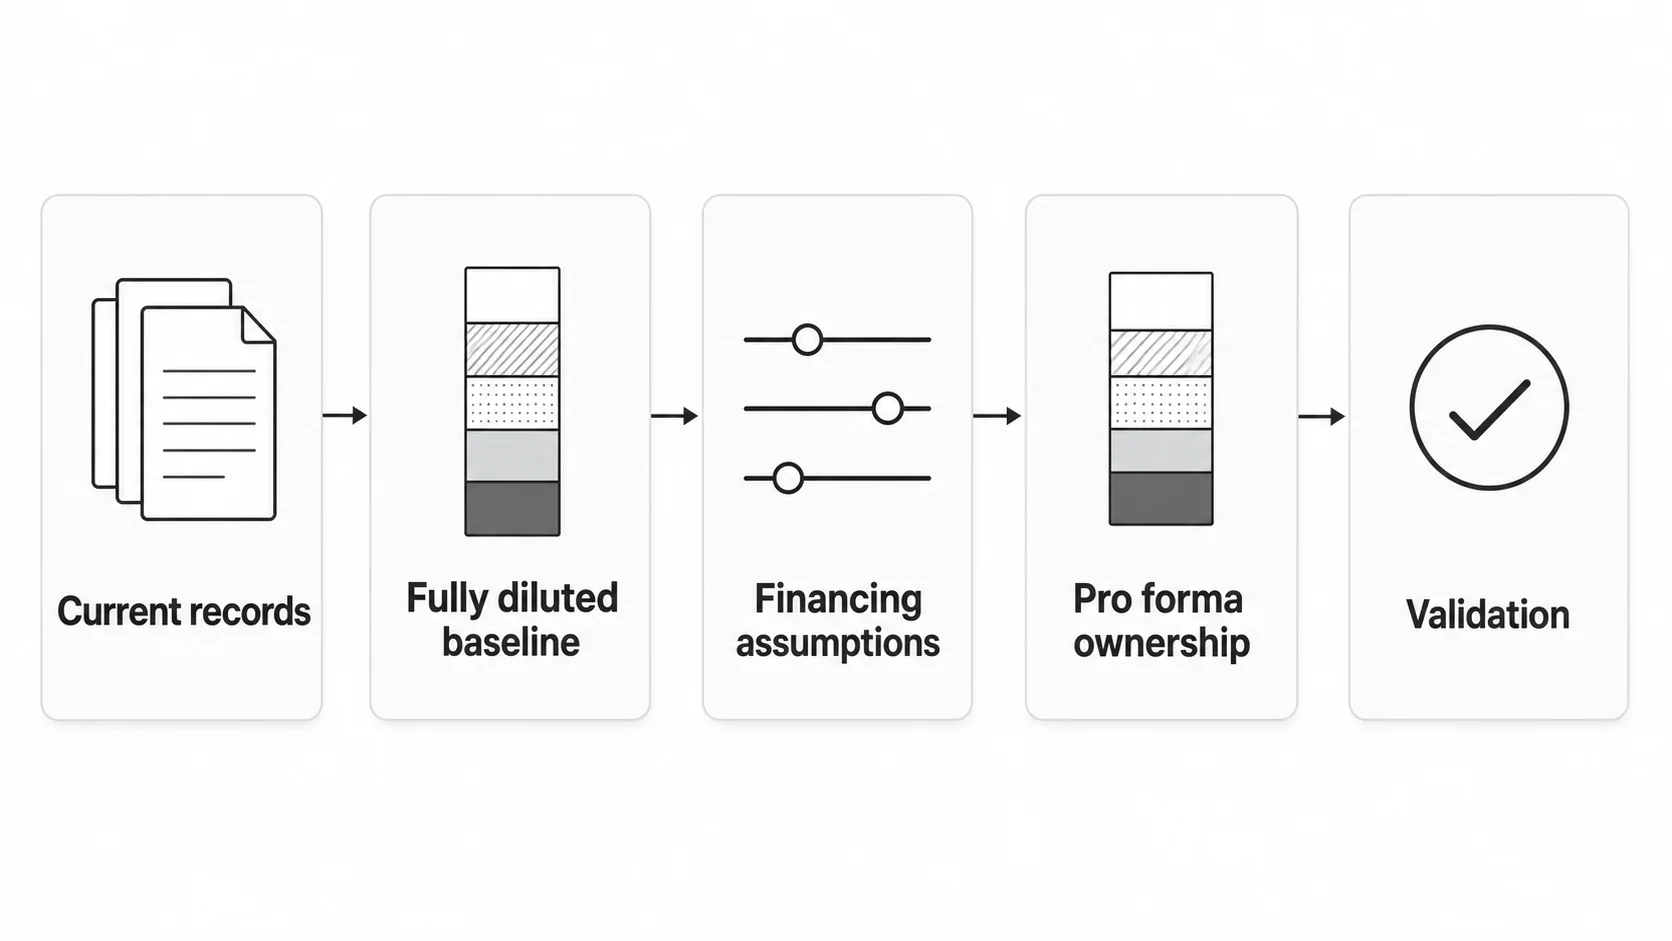
Two checks close the model. Confirm the charter authorizes enough shares for the new series, conversions, and the pool, and change one assumption at a time to see which inputs move ownership most. Company counsel usually prepares the closing version. The Cooley GO sample pro forma cap table is one law-firm template for the layout.
Cap table vs waterfall: ownership is not payout
A cap table shows ownership. A waterfall shows who gets paid, and how much, at a given exit value. The two diverge when preferred stock carries a liquidation preference.
Take the Series A cap table above and count only issued shares: founders 8,000,000, the seed investor 1,000,000, and the Series A investor 2,714,286. Both preferred classes have a 1x non-participating preference, paid side by side. Options and the unissued pool are left out to keep the math readable.
| Holder | Ownership of issued shares | Payout at a $15M exit | Payout at a $100M exit |
|---|---|---|---|
| Founders | 68.3% | $8.5M (56.7%) | $68.3M |
| Seed investor | 8.5% | $1.5M preference | $8.5M as converted |
| Series A investor | 23.2% | $5.0M preference | $23.2M as converted |
At $15 million, converting to common would give the Series A investor less than $3.5 million, so it takes its $5 million preference. The seed investor does the same. Founders own 68.3% of the issued shares but receive 56.7% of the proceeds. At $100 million, both investors convert and payouts match ownership. Participation rights, preference multiples above 1x, and stacked seniority widen the gap. The liquidation preference guide walks through those terms.
Is the cap table the legal record?
Usually not on its own. For a Delaware corporation, the legal record of who holds shares is the stock ledger. Section 219(c) of the Delaware General Corporation Law defines the stock ledger as the records listing all stockholders of record, their shares, and all issuances and transfers, and says it is the only evidence of which stockholders may examine the stockholder list or vote. Section 224 lets companies keep that ledger electronically, including in databases.
In practice, cap table software often holds the stock ledger, so the two can live in the same system. A spreadsheet model emailed between founders and investors is not the ledger. When the two disagree, fix the ledger and the board approvals first, then the model. Companies incorporated outside Delaware should check their own state's corporate law.
How a VC reads a cap table
An investor's first pass is a consistency test. The question is whether the ownership story is clean, and whether anything in it could change price, dilution, control, or the ability to close.
| Check | Question | Red flag |
|---|---|---|
| Baseline | Does the cap table tie to the ledger, option records, and every outstanding instrument? | A "plug" row with no source document |
| Denominator | Is the same fully diluted definition used for price and ownership? | Issued-share percentages next to a fully diluted price |
| Convertibles | Is each SAFE, note, and warrant modeled from its own terms? | All convertibles grouped at one assumed rate |
| Option pool | Is the target pre- or post-money, and total or unissued? | A pool top-up presented as free |
| Secondaries | Are secondary sales kept apart from primary cash? | Secondary proceeds counted as company cash |
| Authorized shares | Does the charter cover conversions, the new series, and the pool? | Post-closing shares above the authorized total |
| Rights | Are preferences, voting, and board seats tracked outside the percentages? | One percentage used as a proxy for every right |
This review sits inside broader venture capital due diligence, next to the term sheet negotiation.
What analysts and associates do with a cap table
At a VC firm, the cap table is working material for junior investors, not a founder document they glance at once.
- Ownership targets. A fund that wants 20% at entry checks whether the check size and the post-money valuation get there on the firm's fully diluted definition. In the example, $5 million into a $25 million post-money valuation is exactly 20%.
- Pro rata and reserves. The cap table shows how much the firm must invest in later rounds to hold its stake, which feeds follow-on investment and reserve planning.
- Portfolio monitoring. After each round, the firm updates its fully diluted ownership for fund reporting and for the next board discussion.
- Interviews and tests. Recruiting processes often include a cap table exercise. The cap table interview questions guide and the VC modeling test guide show what firms ask.
Candidates who can rebuild the Series A table above from a term sheet, and explain who absorbed the pool increase, are ready for that part of the process. Open analyst and associate roles are listed on the VC job board, and the companies directory profiles the firms hiring.
Common cap table mistakes
- Mixing bases. Quoting issued-share ownership in one place and fully diluted ownership in another without labels.
- Plug rows. Forcing totals to 100% with an unexplained line instead of finding the missing security.
- Grouping convertibles. Treating SAFEs or notes with different caps, discounts, or MFN terms as one instrument.
- Missing promised grants. Leaving out options promised in offer letters but not yet approved by the board.
- Unmodeled pool increases. Agreeing to a pool target without running the pro forma that shows who pays for it.
- Secondary sales as company cash. A secondary moves shares between holders and adds no money to the company.
- Authorized share shortfalls. A model that works on paper but needs a charter amendment the company has not approved.
- Stale versions. Several spreadsheet copies with different dates and no single owner.
Spreadsheet or cap table software?
A spreadsheet is fine while the company has only founders, and it remains the normal tool for modeling a proposed round. Once the company has an equity plan with grants, a priced round, or several convertibles, the record of ownership is better kept in cap table management software or by counsel, with spreadsheets used only for scenarios.
| Tool | Works for | Main risk |
|---|---|---|
| Spreadsheet | Founder-only companies; one-off round and pool scenarios | Broken formulas, hard-coded overrides, version sprawl |
| Cap table software | Ongoing ledger, grants, vesting, 409A records, investor access | Bad data entered at setup carries forward |
| Counsel-maintained ledger | Closing sets and formal records | Slower updates between financings |
Whichever tool holds the record, keep one owner, one current version, and a change log that ties to board approvals.
Frequently asked questions
Who maintains the cap table?
At an early-stage startup, a founder or the finance lead usually maintains it, often in cap table software, with company counsel reviewing issuances. Later-stage companies assign it to finance or legal operations. Investors keep their own copy of their ownership but rely on the company's records.
How often should a cap table be updated?
After every equity event: a grant, exercise, transfer, repurchase, conversion, or financing. A quarterly reconciliation against the ledger and board minutes catches anything missed.
Are cap tables public?
Private companies generally do not publish their cap tables. Investors see them during diligence and through information rights, and employees may see their own holdings. Public companies disclose major holders through securities filings instead.
Do SAFEs belong on a cap table before they convert?
Yes. A SAFE has no share count until it converts, but it should appear as an outstanding instrument with its amount, cap, discount, and any MFN term, so the fully diluted view and the next pro forma account for it. The pre-money vs post-money SAFE guide explains how each type converts.
What is a fully diluted cap table?
A fully diluted cap table counts outstanding shares plus every option, the unissued pool, warrants, and convertibles as defined in the relevant documents. It is the basis most term sheets use for price and ownership.
Is a pro forma cap table legally binding?
No. It is a model of a proposed transaction. The executed financing documents, the charter, board approvals, and the stock ledger determine actual ownership. The closing pro forma is usually prepared or checked by company counsel.
Related posts
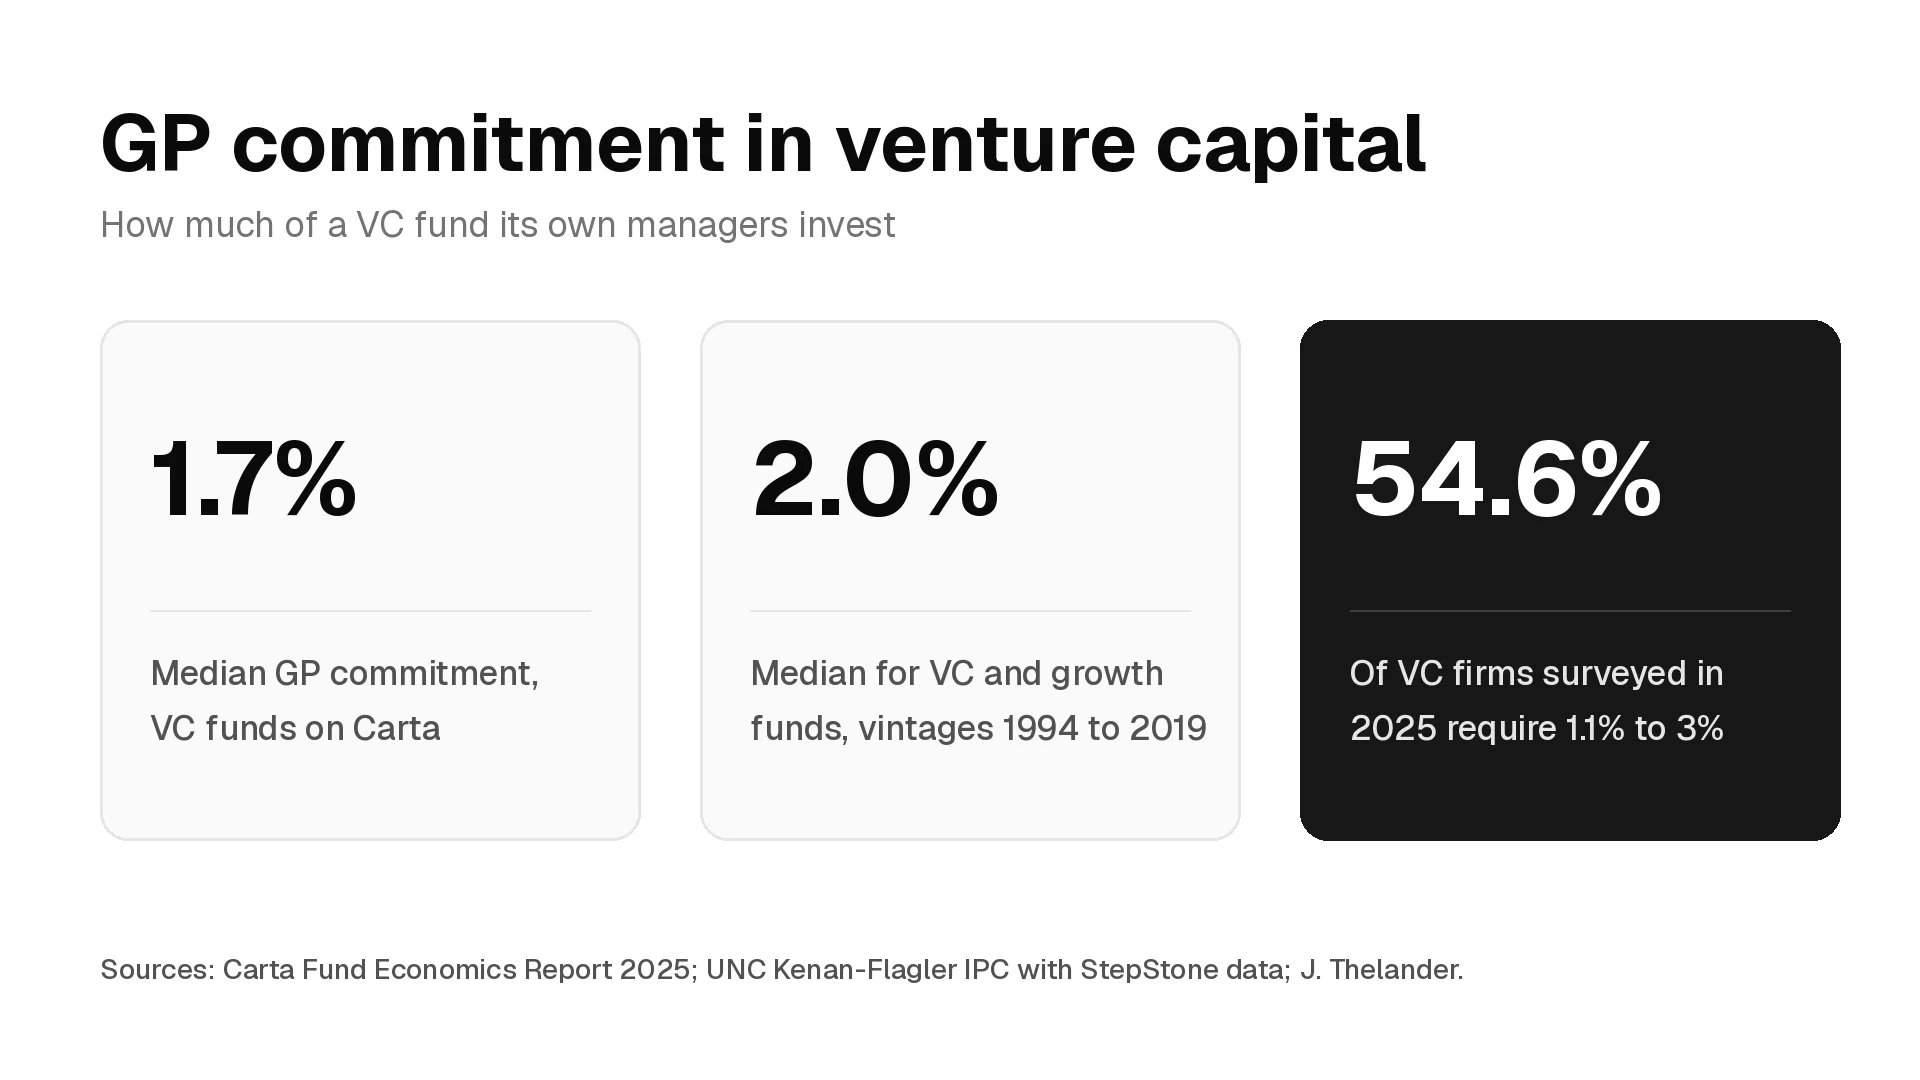
What a GP commitment is, how large it is in venture capital, how GPs fund it, where it sits in the LPA, what the returns evidence says, how firms split it across partners and principals, and what to ask before you accept a role with carry.
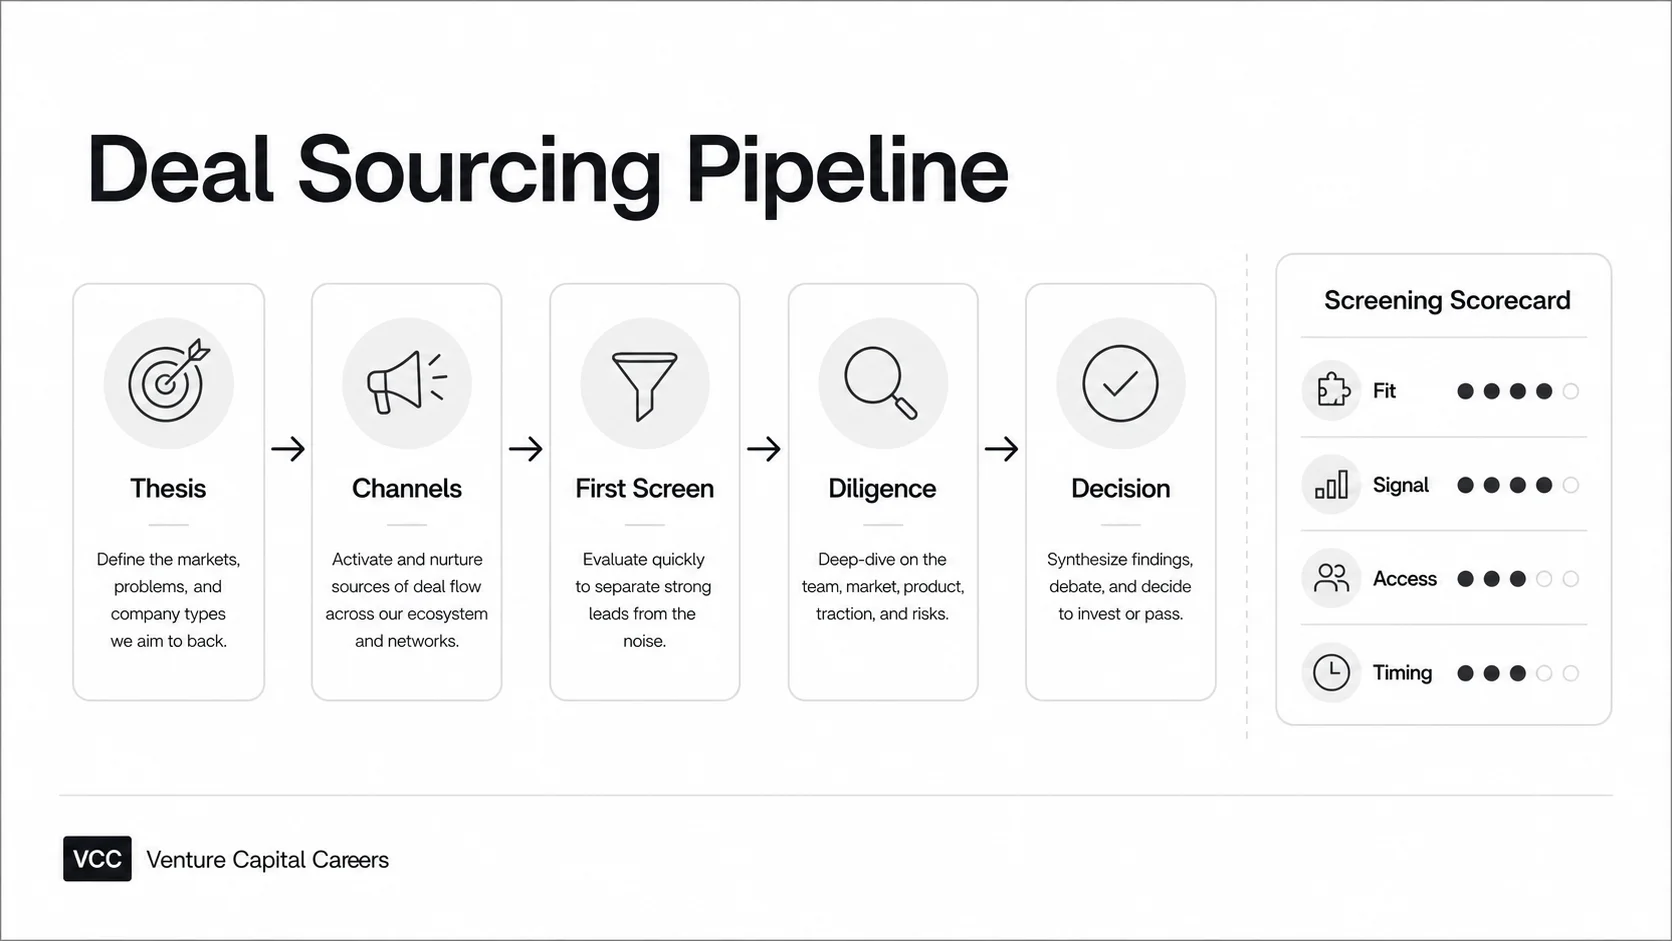
Most closed VC deals start with a relationship. See where deals come from by stage, how to work each sourcing channel, which signals show up early, and how analysts run a weekly sourcing process.
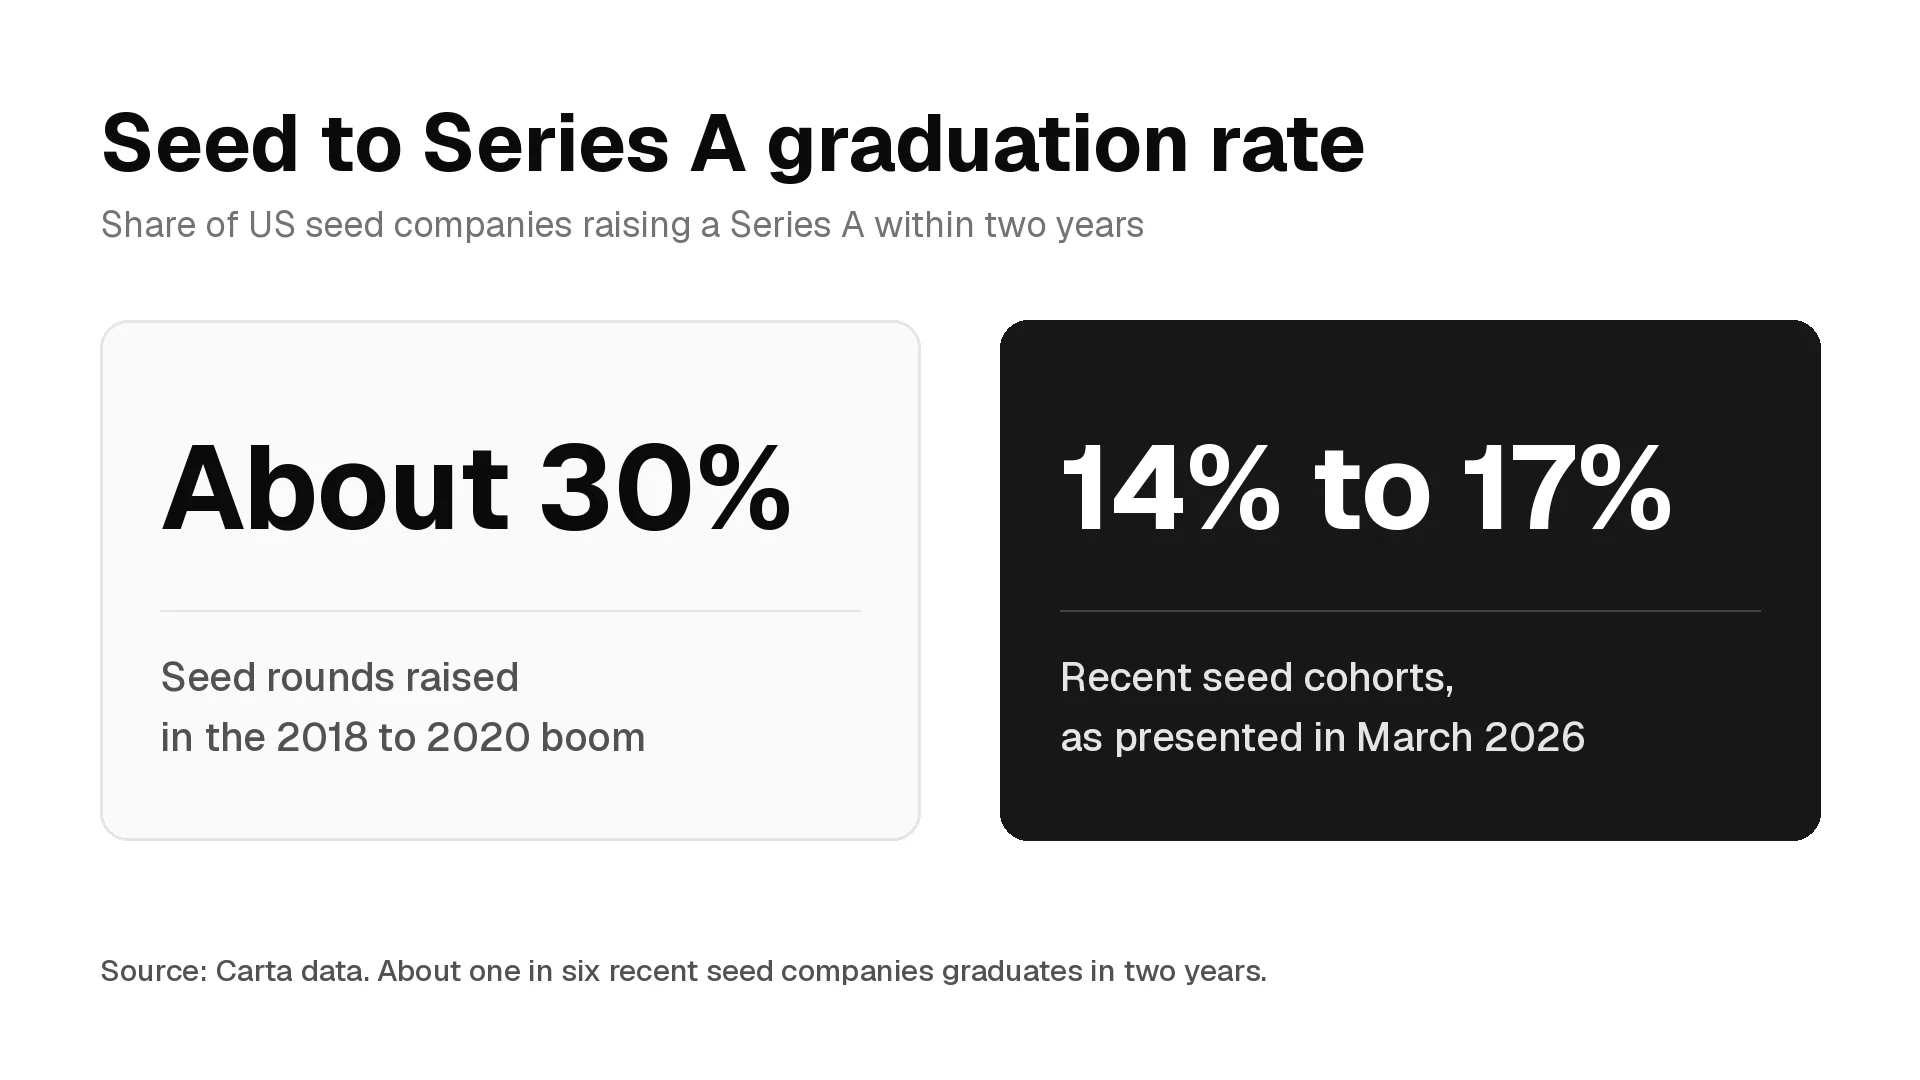
Seed to Series A graduation rates by cohort from Carta and Crunchbase, how long the jump takes, why rates fell after 2021, why published figures disagree, and how seed and Series A firms use the rate for reserves, LP reporting, portfolio reviews and interviews.