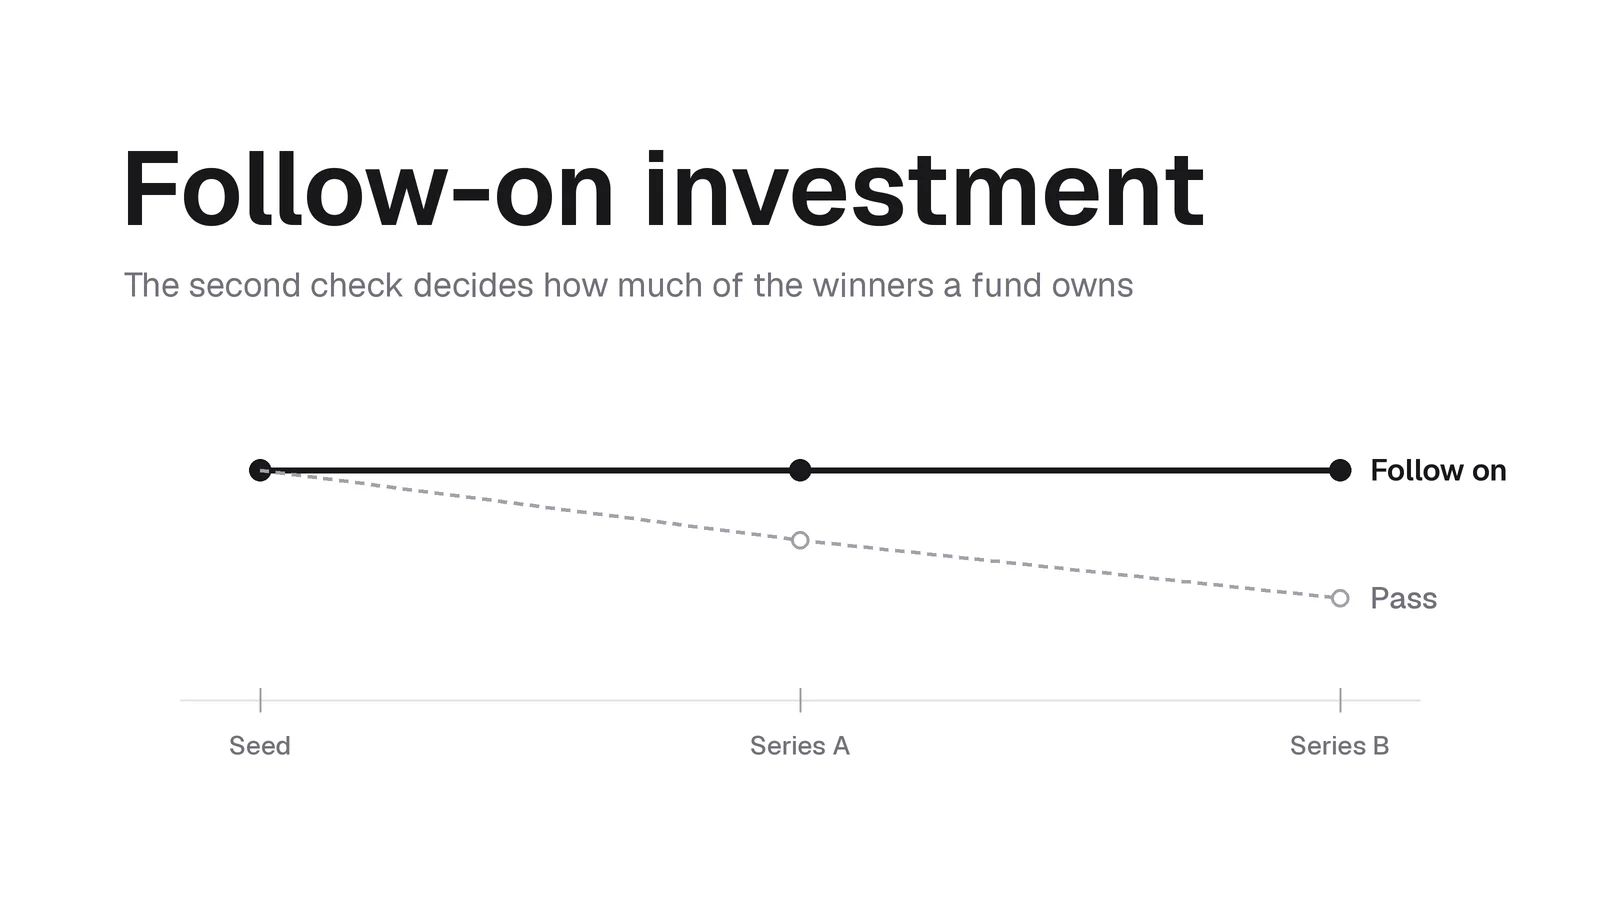
A follow-on investment is additional capital an investor puts into a company it already backs, after the first check. In venture capital, it usually means a fund buying more shares in a portfolio company's next round, most often through pro rata rights, so its ownership does not shrink as the company raises more money.
Funds plan for follow-ons before they invest by holding back part of the fund as reserves. Each later round then forces a fresh decision: take the full pro rata allocation, buy more, buy less, or pass. That decision decides how much of the winners a fund owns at exit, and it is one of the most common pieces of analyst and associate work inside a VC firm.
What is a follow-on investment?
A follow-on investment is any investment an existing investor makes in a company after its initial investment. If a fund leads a seed round and then buys shares in the Series A, the Series A check is that fund's follow-on.
Follow-ons come in several forms:
- Pro rata follow-on. The investor buys its share of the new round, enough to keep its ownership percentage flat.
- Super pro rata follow-on. The investor buys more than its share to increase ownership. The company and the new lead have to make room for it.
- Partial follow-on. The investor takes less than its full allocation, often because of reserve limits or a crowded round.
- Inside round or bridge. Existing investors fund the company without a new outside lead, often through a SAFE or convertible note, to reach the next milestone.
- SPV or opportunity fund check. The manager invests through a separate vehicle when the main fund is out of reserves or at its concentration limit.
The phrase "follow-on funding" is also used from the company's side to mean any later round after the first one. In practice, the investor meaning is the one that changes economics, because it is the investor's ownership that the check protects.
How a follow-on investment works, from notice to wire
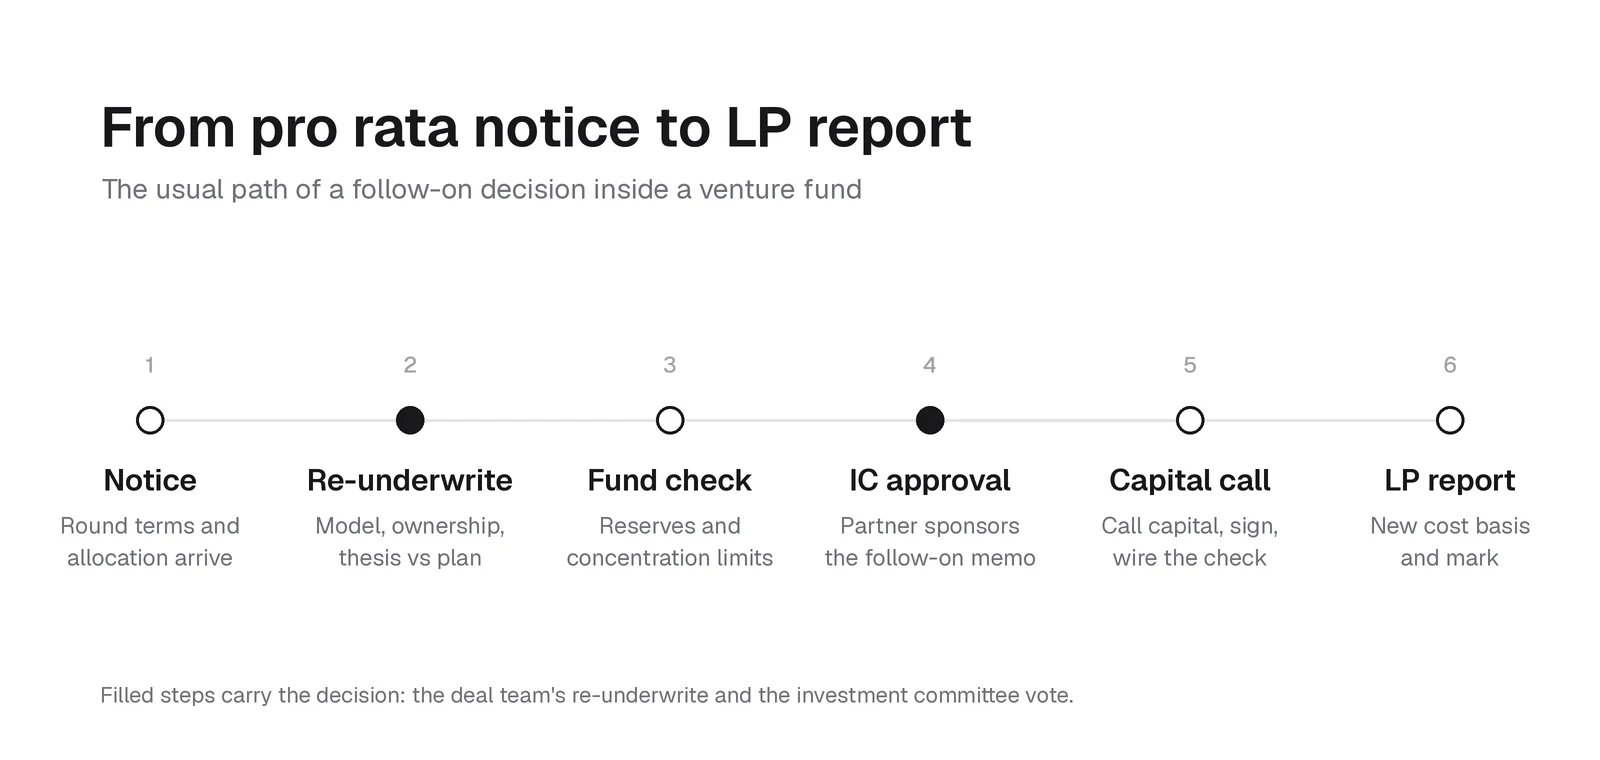
A follow-on starts when the company announces a new round and sends existing investors a notice of their allocation. From there, most funds run the same sequence.
| Step | What happens | Who usually owns it |
|---|---|---|
| 1. Notice | The company or its counsel sends the round terms and each investor's pro rata allocation | Partner on the board, fund counsel |
| 2. Allocation check | The fund confirms what it is entitled to under the financing documents and what the new lead will allow | Associate, fund counsel |
| 3. Re-underwrite | The deal team updates the model, ownership math, and thesis against the plan the first check funded | Analyst and associate |
| 4. Fund check | Finance confirms reserves, concentration limits in the limited partnership agreement, and cash timing | CFO or fund operations |
| 5. Approval | The sponsoring partner takes a follow-on memo to the investment committee | Partner, investment committee |
| 6. Funding | The fund issues a capital call or draws on a credit line, signs the documents, and wires the money | Fund operations |
| 7. Reporting | The new cost basis, ownership, and mark from the round go into the next quarterly LP report | Finance, investor relations |
The deadline matters. Allocation notices often give investors a short window to confirm, and a fund that has not tracked its reserves ahead of time can end up deciding under pressure.
Follow-on investment example: ownership with and without the check
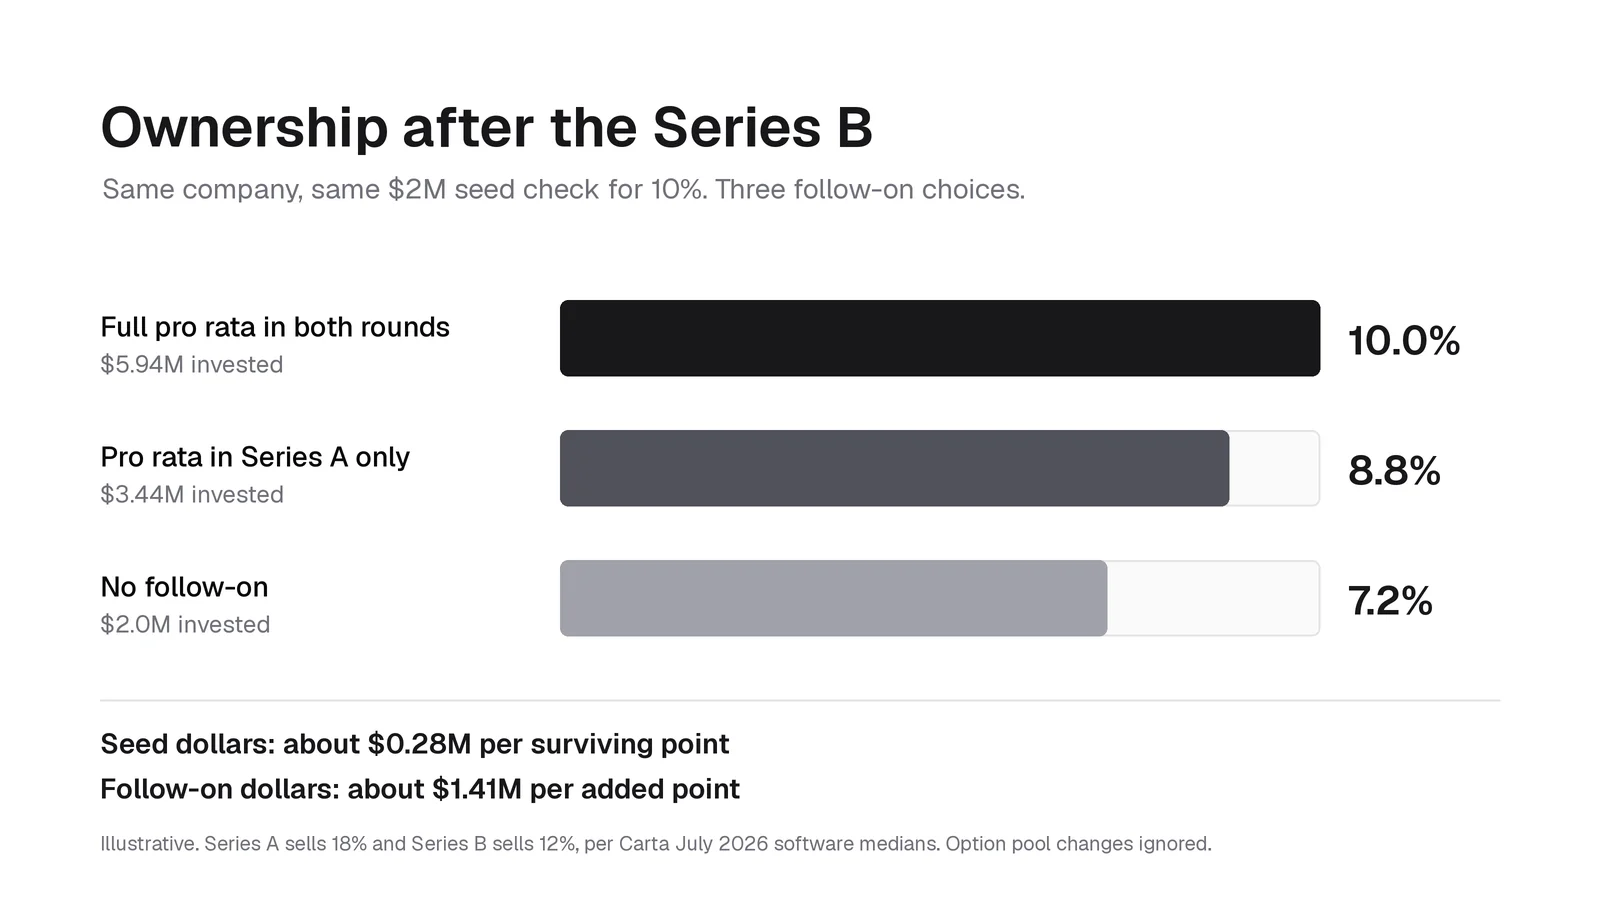
The cleanest way to see what a follow-on buys is to track one stake through two rounds. The example below is simplified. It ignores option pool increases and borrows round sizes and dilution from Carta's July 2026 benchmarks for software companies: a median Series A of $14.4M selling 18% of the company, and a median Series B of $25M selling 12%.
A seed fund invests $2M for 10% of a company. The company then raises a Series A and a Series B at those median sizes.
| Path | Series A check | Series B check | Total invested | Ownership after Series B |
|---|---|---|---|---|
| Full pro rata in both rounds | $1.44M | $2.5M | $5.94M | 10.0% |
| Pro rata in Series A, pass on Series B | $1.44M | $0 | $3.44M | 8.8% |
| No follow-on | $0 | $0 | $2.0M | 7.2% |
The math behind each row:
- Passing on a round that sells 18% leaves the fund with 82% of its prior stake, so 10% becomes 8.2%. Passing on a round that sells 12% leaves 88%, so 8.2% becomes 7.2%.
- Pro rata means buying the same share of the new round as the fund already owns. Ten percent of a $14.4M round is $1.44M, and 10% of a $25M round is $2.5M.
The key number is the price of each ownership point. In this example the original $2M check produces 7.2 points that survive to the Series B, about $0.28M per point. The $3.94M of follow-on capital adds 2.8 points, about $1.41M per point. Follow-on dollars bought ownership at roughly five times the cost of seed dollars, because the company is worth more by then.
That is the whole debate in one line. A follow-on is a bet that the company will grow by much more than the step-up the fund just paid.
Pro rata, super pro rata, and what a fund is actually entitled to
Pro rata is a right to participate, not an obligation to invest. Its value depends entirely on the documents and on the next lead.
Three practical limits shape what a fund can actually buy:
- Thresholds. In the NVCA model Investors' Rights Agreement, the right to buy a share of new securities usually goes to "Major Investors" above a holding threshold set in the agreement. Smaller holders may have no contractual right at all. The same threshold often controls information rights.
- SAFE side letters. At the earliest stage, pro rata rights often sit in a separate side letter rather than in the SAFE itself. Post-money SAFE forms and the optional pro rata side letter are in the Y Combinator documents library.
- Lead cutbacks. A new lead that wants a fixed ownership target may ask existing investors to waive or cut back their allocation. A contractual right can still lose to a hot round.
Super pro rata is a negotiation, not a right. It works when the company wants the insider's money more than the new lead wants the extra shares, which usually means a less competitive round. In the most competitive rounds, the follow-on a fund most wants is the one it is least able to get.
Offensive vs defensive follow-on investments
Funds usually describe a follow-on by its purpose.
| Type | When it happens | What the fund is buying | Main risk |
|---|---|---|---|
| Offensive | The company is working and raising on strong terms | More ownership in a likely winner | Paying a price that already assumes the win |
| Defensive | A good company hits a slow market or a missed milestone | Time to reach the next value inflection point | Funding a company that will not recover |
| Protective | Terms punish non-participants, as with a pay-to-play provision or a down round | Keeping preferred rights and avoiding conversion to common | Sending good money after bad to protect a past check |
Offensive follow-ons are what reserves are meant for. Defensive and protective follow-ons are where funds lose discipline, because the money goes in to rescue the original decision rather than to buy new upside. A bridge round can be either, depending on whether it funds a specific milestone.
How VC funds size follow-on reserves
Reserves are the share of a fund held back for follow-on investments instead of first checks. The reserve ratio compares the two. A 1:1 ratio means one dollar held for follow-ons for every dollar of initial investment.
Common reference points come from managers and LPs who publish their own numbers:
- Sapphire Partners, an LP in many venture funds, wrote in 2022 that most of the managers in its portfolio cluster around a 1:1 initial-to-reserves ratio.
- Homebrew co-founder Hunter Walk wrote in July 2026 that the conventional wisdom when Homebrew started was to hold 20% to 50% of capital for follow-ons, and that funds of $100M or less should now hold almost none.
Reserves change the exit a fund needs. In Sapphire's example, a $50M fund that owns 7.5% at exit needs a $666M exit to return the fund. Add 1:1 reserves and the fund becomes $100M. Even if the follow-ons lift ownership to 10%, the company now needs a $1B exit to return it.
The same post models where reserve dollars go. When reserves are concentrated in the eventual winners, net TVPI rises from 4.0x to 5.0x. Spread evenly across every company that raises a Series A, it falls to 3.3x. Spread evenly and miss the biggest winner, it falls to 2.5x. Because returns follow a power law, a reserve policy is only as good as the fund's ability to pick which companies get the money.
A working reserve plan usually answers four questions:
- How many companies in the portfolio are expected to raise a next round?
- In how many of those will the fund take full pro rata, partial, or none?
- What will those rounds likely cost at the fund's target ownership?
- What happens when a winner needs more than the plan allows?
The answer to the fourth question is usually recycling early proceeds, an SPV, or offering the allocation to LPs as a co-investment. Walk writes that Homebrew got to more than 120% invested in each of its first two funds by recycling. Uncalled reserves also show up in industry totals of dry powder, which is why reserve capital and new-deal capital are not the same thing even when both are uninvested.
The wider portfolio construction choices sit in venture capital portfolio strategy.
How VCs decide whether to follow on
The core test is simple to say and hard to apply. Would the fund make this investment today, at this price, if it had never met the company? Already owning shares is not a reason to buy more.
| Question | What a strong answer looks like | What should slow the decision |
|---|---|---|
| Did the company hit the plan the last check funded? | Revenue, retention, and burn close to or ahead of the original memo | Missed milestones with a new explanation every quarter |
| Who is leading and pricing the round? | A credible outside lead investor set the price | An inside-only round where the fund is setting the price itself |
| What is the step-up? | Price increase supported by progress, not just market heat | Valuation that already prices in the next two rounds |
| What does the fund own with and without the check? | Ownership math done for each path, as in the example above | No model, only a feeling that the price is high or low |
| What exit does this need to matter? | A plausible exit that moves the fund, not just the deal | An exit size the market has rarely produced |
| What does this capital displace? | Clear reason it beats a new first check or another follow-on | Reserves spent first come, first served |
| Are the terms clean? | Standard liquidation preference and protections | Heavy preferences, warrants, or structure that will hurt the next round |
Two failure modes show up again and again. Funds double down on struggling companies because of sunk cost, and they pass on winners because the price looks expensive next to the seed price. The re-underwrite test is designed to catch both.
Good funds write the decision down either way. A memo explaining a pass is useful when an LP later asks why the fund owns less of its best company.
Signaling risk: what a pass tells the next investor
An existing investor has more information about a company than any new investor. That makes its follow-on decision a signal.
When a well-known insider takes full pro rata, a new lead reads it as confidence. When a large insider passes, the new lead will ask why, and the answer can slow or reprice the round. Signaling risk tends to be highest for large multistage funds whose seed checks are small relative to their reserves, because a pass from them looks like a judgment rather than a budget limit.
There are ways to soften a pass:
- Say plainly when the reason is fund-level, such as reserves, concentration limits, or fund life, rather than company performance.
- Take a partial allocation instead of zero when the fund still believes in the company.
- Offer the allocation to LPs or an SPV so capital still arrives from the same manager.
Walk calls signaling risk minimal and overblown, partly because so many new firms now lead rounds. Both views can hold. The signal is weakest when the fund is small and its limits are public, and strongest when the fund is large and could easily have invested.
Why founders seek follow-on funding and how to find follow-on investors
For a founder, existing investors are the fastest capital to raise. They already know the board materials, the burn, and the pipeline.
Follow-on funding from insiders helps when:
- The company has hit real milestones and insiders want to commit before a new lead prices the round.
- The company needs a bridge to a specific revenue, product, or regulatory milestone.
- Insider commitments make an outside lead more comfortable underwriting the round.
The most useful question a founder can ask an early investor is how much it reserves per company and how it decides who gets it. A seed fund that led the round may have little capacity at the Series A. A multistage fund may have plenty but attach a strong signal to every decision.
Finding follow-on investors usually means finding the next lead, with insiders filling out the round. That search starts with firms that invest at the next stage and in the sector, then warm introductions from existing investors. The Venture Capital Careers companies directory lists VC and growth firms to build that target list.
Follow-on investment in private equity
In private equity, a follow-on investment is additional equity a sponsor puts into a company it already controls after the original buyout. The mechanics differ from venture because the sponsor usually owns a majority and does not depend on a separate lead or pro rata rights.
Private equity follow-ons commonly fund:
- Add-on acquisitions in a buy-and-build strategy.
- Capital expenditure or expansion the company's debt cannot cover.
- A covenant cure or liquidity need when the company underperforms.
The decision still comes back to re-underwriting. The fund asks whether the new equity earns its own return, and how it changes concentration in the fund. The career and deal differences between the two asset classes are covered in private equity vs venture capital.
Follow-on investor vs lead investor vs follow investor
These terms overlap and are often used loosely.
| Role | Meaning | What they usually do |
|---|---|---|
| Existing investor | Already invested in a prior round | Decides whether to invest again, take pro rata, or support a bridge |
| Follow-on investor | An existing investor investing again in a later round | Adds capital after the company has a track record |
| Follow investor | A non-lead investor that joins a round after another investor sets the terms | Takes an allocation in the syndicate without negotiating terms |
| Lead investor | Negotiates price and terms and often takes a board seat | Anchors the round so others can underwrite it |
An existing investor can lead a follow-on round. A new investor can be a follow investor without being a follow-on investor. The role depends on who sets the price, who negotiates the documents, and who writes the largest check.
Follow-on investment vs follow-on offering
A follow-on offering is a public company selling more shares after its IPO. It can be dilutive, when the company issues new shares, or non-dilutive, when existing holders sell shares they already own.
A follow-on investment in venture capital happens while the company is private and runs through financing documents such as a stock purchase agreement or a SAFE. The overlap is only the word "follow-on." For anyone working in or around VC, the private meaning is the relevant one.
When a follow-on round is a warning sign
A follow-on round can mean strength or stress. The difference is usually visible in who is paying and on what terms.
Watch for:
- No outside lead. Insider-only rounds are normal for bridges, but repeated inside rounds suggest the market will not price the company.
- Missing insiders. If a major existing investor does not participate, new investors will ask why.
- Bridge with no milestone. A bridge should fund a specific outcome. One that only extends runway delays a harder conversation.
- Punitive terms. Senior preferences, warrants, and pay-to-play can close a round and damage incentives for the next one.
- Vague use of proceeds. The money should tie to hiring, product, revenue, or market expansion that changes the next financing.
A good follow-on round buys progress. A weak one buys time without changing the story.
Follow-on work inside a VC firm
After a fund's investment period ends, new investments usually stop but follow-ons continue. In a fund's later years, reserve decisions can be most of the deal work.
| Role | Follow-on work |
|---|---|
| Analyst | Updates the cap table and pro rata calculation, pulls comparable rounds, tracks KPIs against plan |
| Associate | Drafts the follow-on memo, runs ownership and exit scenarios, gathers founder and customer updates |
| Principal or partner | Forms the view, negotiates the allocation with the company and new lead, sponsors the decision at IC |
| Investment committee | Approves or rejects the check and sets any conditions |
| CFO or fund operations | Tracks reserves and concentration limits, calls capital, books the investment, updates LP reporting |
A follow-on memo is shorter than a first-check investment memo but asks harder questions. A strong one covers:
- The original thesis and what has proven true or false since.
- Progress against the plan the last check funded.
- The new round's terms, lead, and step-up.
- Ownership with and without the check, and the exit needed for it to matter.
- Reserve impact and what else the capital could fund.
- A clear recommendation: full pro rata, partial, super pro rata, or pass.
The same thinking shows up in recruiting. Case interviews and modeling tests often ask candidates to decide whether a fund should follow on, then defend the ownership math. Candidates who can explain the price-per-point tradeoff from the example above stand out. The venture capital case study interview guide covers how those prompts are structured, and the quarterly portfolio review is where most follow-on candidates first get flagged.
Analyst, associate, and fund operations roles that include portfolio and reserve work are listed on the Venture Capital Careers job board.
FAQ
What does follow-on investment mean?
Follow-on investment means additional investment in a company by an investor that has already invested in it. In venture capital, it usually refers to an existing fund buying shares in the company's next round.
Is follow-on funding the same as a bridge round?
No. A bridge round is one type of follow-on funding, usually from insiders, meant to carry the company to a milestone. Follow-on investment also happens in normal priced rounds such as a Series A or Series B.
Is follow-on investment dilutive?
The new round is dilutive to every shareholder when the company issues new shares. A follow-on lets an existing investor offset that dilution by buying its share of the new shares.
How much do VC funds reserve for follow-ons?
It varies by fund. Sapphire Partners reported in 2022 that most managers it backs cluster near a 1:1 ratio of initial checks to reserves, which is about half the investable fund. Some small-fund managers now argue for far lower reserves.
Why would an investor not follow on?
Common reasons are missed milestones, a price that already assumes the outcome, a lack of reserves, a concentration limit, a new lead cutting back allocations, or a judgment that the capital earns more in a new company.
What happens if a VC does not follow on?
Its ownership falls with each new round, and new investors may read the pass as a negative signal. A clear explanation, a partial allocation, or an SPV can reduce the damage.
What is the difference between a follow-on investment and an SPV?
A follow-on from the main fund uses LP capital already committed to the fund. An SPV is a separate vehicle raised for one company, often used when the main fund is out of reserves or at its concentration limit.
What is a follow investor?
A follow investor is a non-lead investor that joins a round after another investor sets the price and terms.
Related posts
PME asks whether a venture fund beat a public index on the same cash-flow dates. A worked KS-PME and direct alpha example, five methods compared, current Cambridge Associates data, and what it means if you work at a VC firm.
U.S. venture funds usually avoid Investment Company Act registration through 3(c)(1) or 3(c)(7). One caps how many people can own the fund. The other admits only qualified purchasers. Here is the difference, a worked slot example, and what it means for people who work at VC firms.
Write a concise VC analyst cover letter that ties your background to fund fit, sourcing, research, and investment analysis. Includes a template, sample letter, channel lengths, alternate application prompts, and checklist.